
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Indian Growth Stocks With Revenue Growth Up To 27%
Higher for longer interest rates, flagged recently by former Fed official Kevin Warsh, have pushed many investors towards safer yields and away from growth stories. That creates a gap where fast growing Indian businesses with meaningful insider ownership can attract patient capital. This article walks through three such stocks from our screener, explaining what they do, why insiders matter, and how today’s rate backdrop can shape the opportunity.
The three stocks below are only a starting sample from this theme. The full screen surfaced 106 more Indian businesses with strong growth profiles and meaningful insider ownership that are not covered here.
If you want to identify and analyze those additional stories with the most conviction potential, head straight into the Fast Growing Stocks With High Insider Ownership screener.
Rubicon Research (NSEI:RUBICON)
Overview: Rubicon Research develops specialty pharmaceutical products using its RubiReten and RubiSRL drug delivery platforms across high-growth therapy areas globally.
Operations: Rubicon Research generates about ₹19,358 million in revenue from pharmaceutical products, including generics, specialty formulations, APIs, and related services.
Market Cap: ₹277.5 billion
Rubicon Research matters for this screener theme because its proprietary drug delivery platforms give management a clear lever for higher value product launches that align with growth-focused insider confidence.
"Expansion of US manufacturing capacity through the New Jersey facility and preparation of the Pithampur site in India is expected to support a higher own manufacturing share and can support gross margin resilience and operating EBITDA over time."
What happens to Rubicon Research’s earnings profile depends heavily on how one unseen pressure on future pricing and product mix evolves.
That hidden pressure is exactly what the full narrative for Rubicon Research unpacks, showing where pricing power could accelerate, stall, or quietly decouple from headline revenue.

Atlanta Electricals (NSEI:ATLANTAELE)
Overview: Atlanta Electricals manufactures power and solar-related transformers for transmission and industrial customers across India, tying directly into grid and renewable expansion.
Operations: Atlanta Electricals generates about ₹20,027 million in revenue from manufacturing power and special duty transformers, almost entirely within India.
Market Cap: ₹125.0 billion
Atlanta Electricals aligns tightly with the fast growing insider-backed theme, with earnings forecast to rise 31.27% a year and revenue expected to increase 24.7% annually, supported by transformer demand in transmission and solar projects. However, that growth outlook could change significantly if a single key assumption around funding costs and leverage shifts.
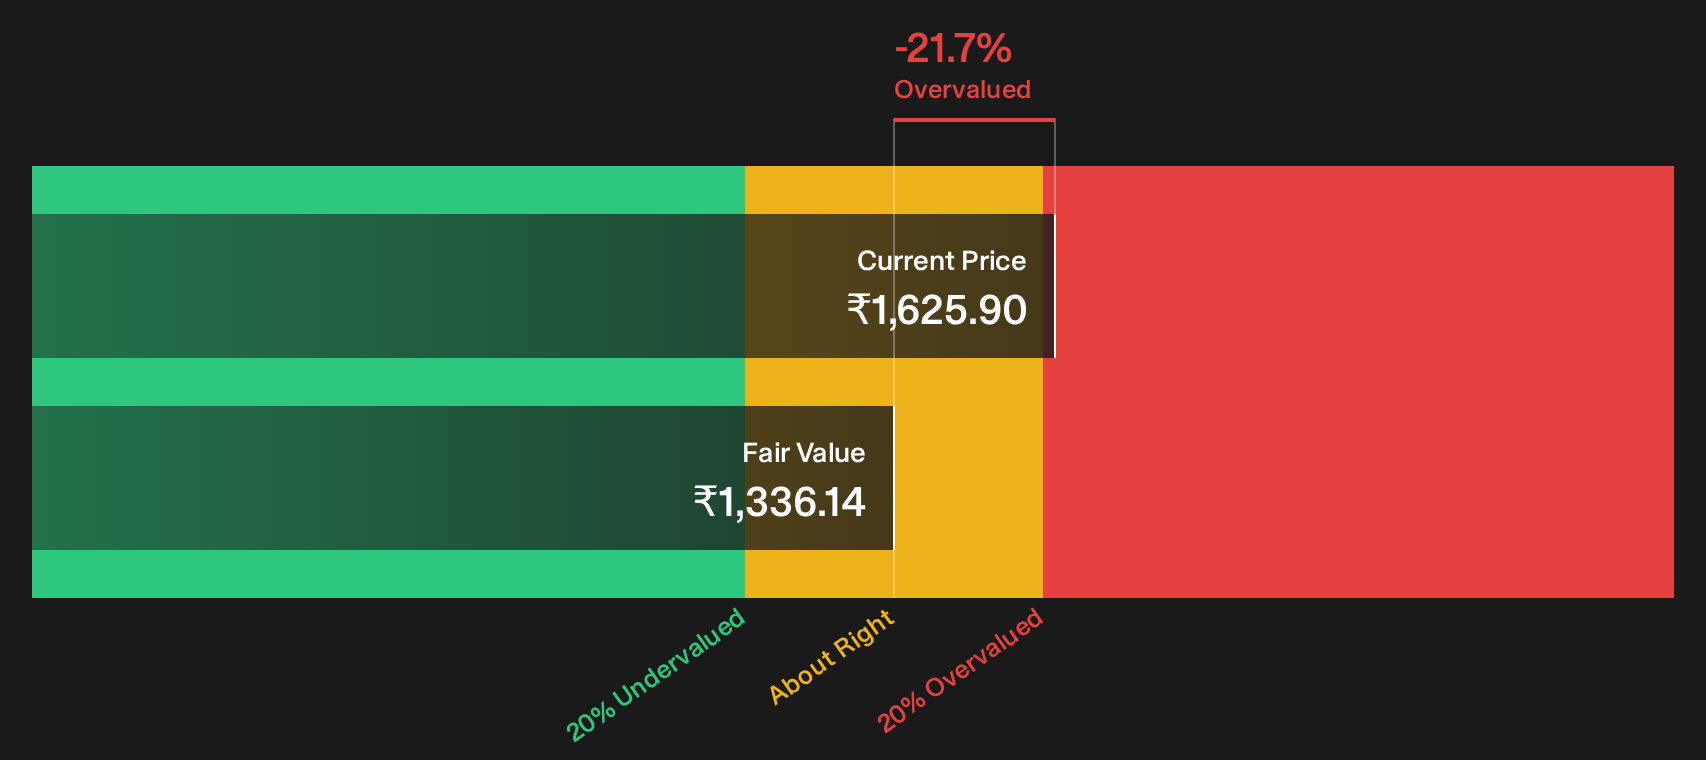
That single assumption is exactly what the DCF valuation analysis for Atlanta Electricals unpacks for Atlanta Electricals, showing where funding costs could quietly reshape the growth story.
Bajel Projects (NSEI:BAJEL)
Overview: Bajel Projects focuses on EPC work for extra high voltage transmission lines and substations, directly serving India’s power grid expansion.
Operations: Bajel Projects generates about ₹27,508 million in revenue from power transmission and power distribution EPC projects.
Market Cap: ₹20.0 billion
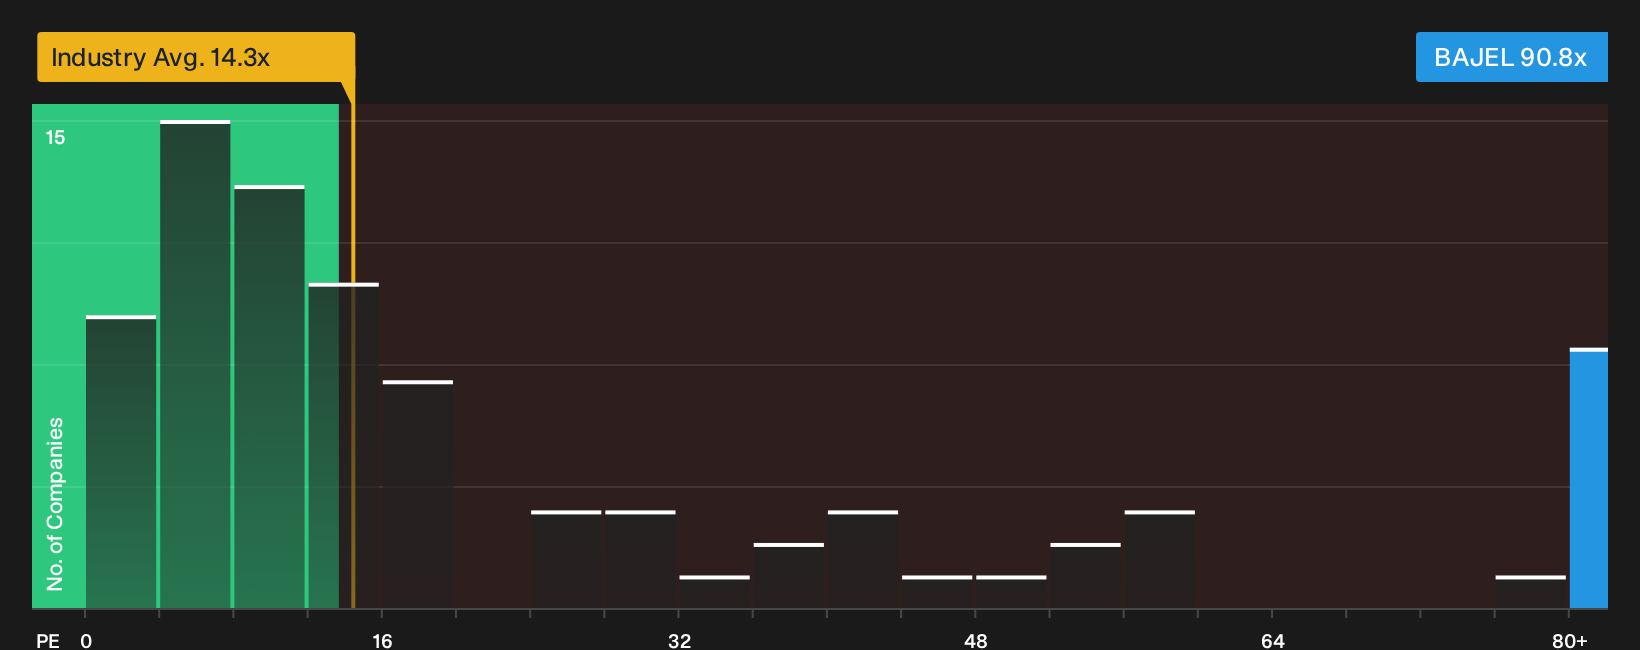
Bajel Projects fits into the screener theme through large EPC contracts in 765 kV lines and substations, with earnings forecast to grow 57.7% a year and revenue expected to rise about 27% annually. Investors considering that growth-linked insider confidence still have to weigh the potential impact if pressures related to its high P/E and external borrowing funding model play out differently than expected.
Those funding and valuation pressures are exactly what the 2 key rewards and 1 important warning sign lays bare, where accelerating contracts could be masking one crucial pressure point.
Curious About Alternative Stock Paths?
Fresh breakout candidates rarely stay quiet for long. Some gain momentum fast, others get caught dropping just as the crowd notices. Scan these under the radar ideas while it matters and act now.
- Spot resilient cash generators before the crowd and run them through the list of solid balance sheet and fundamentals (201 results). Do it while these fundamentals still sit under most radars.
- Track cash rich AI momentum that is already flying and pressure test those prospects with the 37 profitable AI stocks that aren't just burning cash. Do not wait for headlines to catch up.
- Position ahead of a potential nuclear build out and comb through the 19 nuclear energy infrastructure stocks to see which operators still trade like forgotten infrastructure plays.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com