
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Logistics Venture Might Change The Case For Investing In Ares Management Stock
- Ares Management reported that an Ares Real Estate fund and the Public Sector Pension Investment Board formed a joint venture to invest up to US$2.4b in U.S. logistics properties, starting with a 5.2 million square foot seed portfolio of 14 assets in California, Texas and New Jersey.
- This partnership concentrates fresh capital and operating expertise into income focused logistics real estate, giving Ares Management another scaled pool of long duration fee potential in a sector where modern distribution space remains in high demand.
- We will now look at how this large US$2.4b logistics venture could influence Ares Management’s broader investment narrative and earnings mix.
Ares Management Investment Narrative Recap
Ares Management appeals to investors who want an expanding alternative asset platform with multiple fee streams across credit, real assets and private equity. The key near term swing factor is execution on deploying its dry powder into fee paying strategies while handling current valuation expectations, given a P/E of 56.9x and earnings that include large one off items.
The new US$2.4b logistics partnership fits that thesis by adding income focused real estate backed fees, but it does not remove core risks. Debt coverage by operating cash flow remains tight and the dividend is not well covered by earnings or free cash flow, so funding discipline and payout policy stay front of mind.
The logistics joint venture announced in mid September is the clearest operational link to Ares Management’s growth story right now. It directly builds on the Real Assets Group, which generated US$962.7m of revenue, and leans on Marq Logistics to manage modern distribution facilities in large US industrial hubs.
For catalysts, investors may watch how quickly this US$2.4b commitment converts into fee paying AUM and how stable cash flows from these high occupancy focused properties are over time. The main risk is that heavier real estate exposure, combined with already pressured cash coverage of debt and dividends, could limit flexibility if fundraising or transaction activity slows.
Ares Management's narrative projects US$6.9b revenue and US$1.9b earnings by 2029. Analysts are assuming 5.2% yearly revenue growth, which implies an earnings increase of about US$1.3b from US$561.7m today.
Uncover why Ares Management's fair value indicates a 19% potential upside to its current price that could narrow quickly.
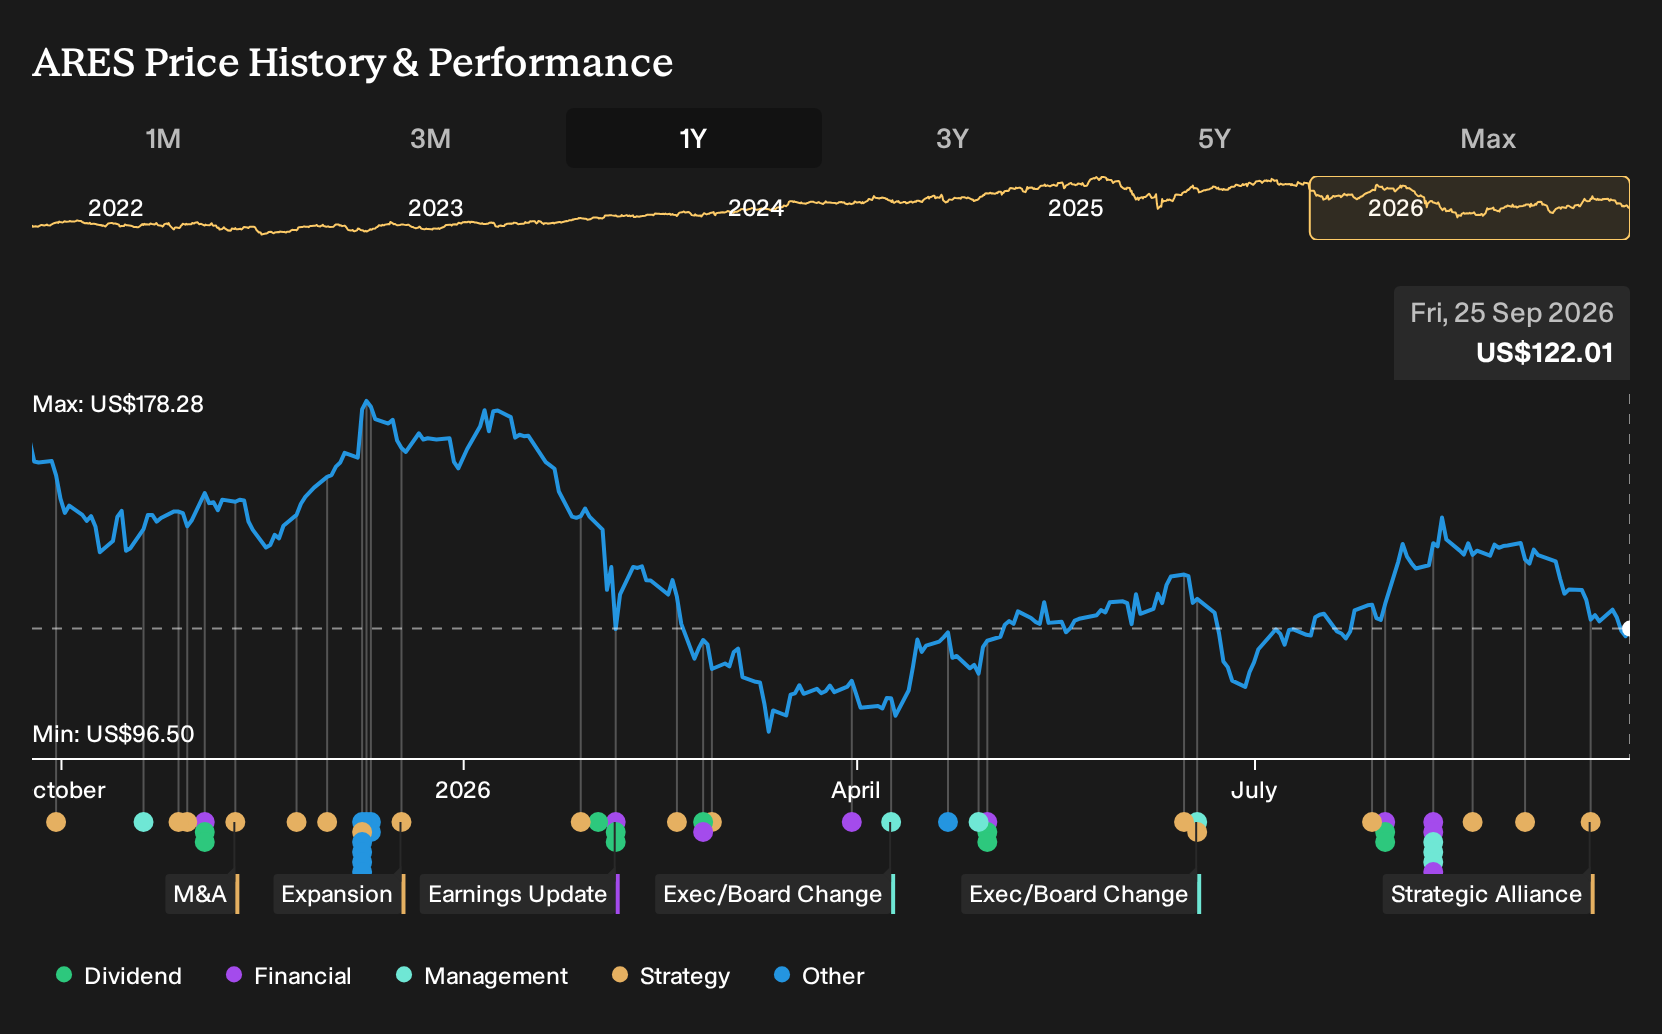
Exploring Other Perspectives
One alternate angle on Ares Management focuses more on upside from logistics and infrastructure deployment than on fee pressure. The most optimistic analysts were already penciling in about US$7.2b of revenue and US$2.7b of earnings by 2029 before this joint venture, so views clearly vary. Use this new deal as a prompt to compare those competing stories.
Explore 2 other Ares Management fair value estimates, including one that suggests up to 38% potential upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis.
- A great starting point for your Ares Management research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Ares Management. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ares Management's overall financial health at a glance.
Looking for more investment ideas beyond Ares Management?
Once you have a view on Ares Management, it helps to widen the lens and compare it with other opportunities that fit different income, quality and risk preferences. The Simply Wall St Screener lets you scan the market quickly and filter for the types of businesses that match your own framework.
- If capital preservation sits high on your list, you can narrow the field to companies that combine resilient operations with lower measured risk using our 30 resilient stocks with low risk scores.
- For investors who prefer quality assets that may be overlooked by the market, you can surface candidates with what you consider strong fundamentals and room for a potential rerating through our 16 high quality undiscovered gems.
- Income focused readers can concentrate on payout potential by screening for high yielding businesses with robust balance sheets via the 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com