
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Astrana Health (ASTH) Rebound Meets A Narrative That Still Sees Undervalued Shares
Astrana Health (ASTH) has been under the spotlight since rebranding from Apollo Medical Holdings in February 2024, with investors now weighing its three-segment healthcare model against recent share price swings.
Recent trading paints a mixed picture for Astrana Health. The 1-day share price return of 5.60% and 7-day gain of 5.85% come after a 90-day share price decline of 19.23%. The 1-year total shareholder return of 22.54% contrasts with a 5-year total shareholder loss of 59.33%, suggesting short term momentum has improved even as longer term holders still sit on sizeable drawdowns.
Compare Astrana Health's recent swing in momentum with other hand-picked healthcare names moving on fundamentals using the list of solid balance sheet and fundamentals (24 results).
Astrana Health has just bounced, yet longer term holders still sit on deep losses. Do you lean into this reset now, or wait for a cleaner entry on the numbers ahead?
Most Popular Narrative: 27% Undervalued
Astrana Health's most followed narrative pegs fair value at about $50 per share compared with the recent $36.37 close, which raises a clear question about whether the current price fully reflects its value based care focus and integration efforts.
Continued transition to full risk, value-based care contracts (now 78% of revenue, up from 60% YoY) is driving recurring, higher-quality revenue streams and improved patient retention. This is positioning Astrana to benefit from rising demand for coordinated, efficient healthcare as the U.S. population ages, which is likely supporting both revenue growth and sustainable margin expansion over time.
See why 6 investors see Astrana Health as 27% undervalued.
Result: Fair Value of $50 (UNDERVALUED)
Still, the Astrana Health story hinges on cleaner Prospect integration and stable government reimbursement. Any setback could quickly challenge that 27% undervaluation pitch.
Find out about the key risks to this Astrana Health narrative.
Another View on Astrana Health’s Valuation
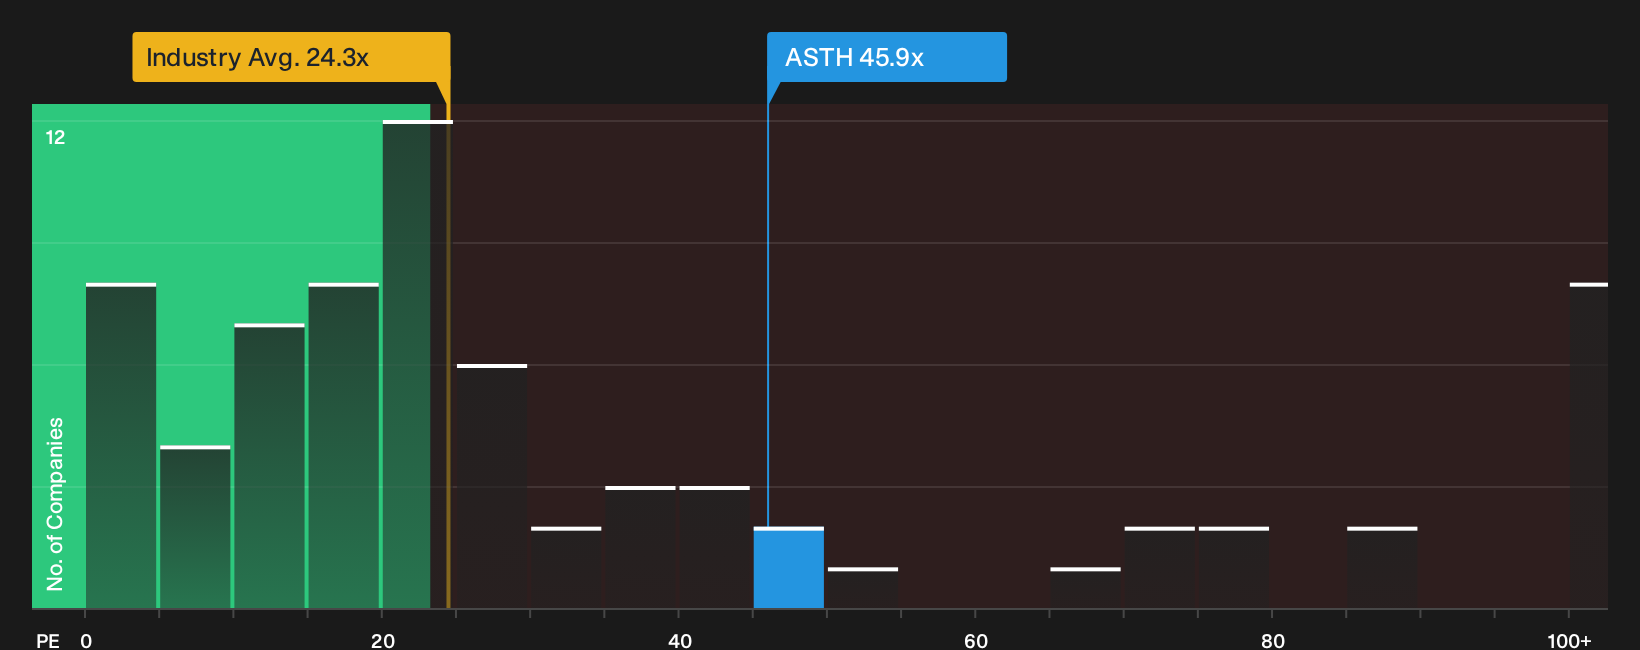
The first lens on Astrana Health leans on future earnings and fair value targets. A second angle comes from the P/E ratio. The stock trades at about 45.9x earnings, compared with a fair ratio of 37.3x and a US Healthcare average of 24.3x, while peers sit around 48.2x.
That mix suggests the share price carries richer expectations than the broader industry, yet is roughly in line with closer comparables. This can mean less room for error if growth or margins fall short. Does that risk profile feel acceptable given your own view of Astrana Health’s execution and balance sheet?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Astrana Health can pull you either way, so move quickly, stress test the data for yourself, then weigh the 4 key rewards and 1 important warning sign.
Looking for more Astrana Health sized ideas?
If Astrana Health has sharpened your appetite for focused research, do not stop here. Broaden your watchlist now or risk missing cleaner setups elsewhere.
- Target stronger value with a tighter quality filter by checking companies on the 32 high quality undervalued stocks.
- Protect your downside first and let upside surprise you by reviewing the 30 resilient stocks with low risk scores.
- Spot potential future favorites before the crowd catches on by scanning the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com