
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
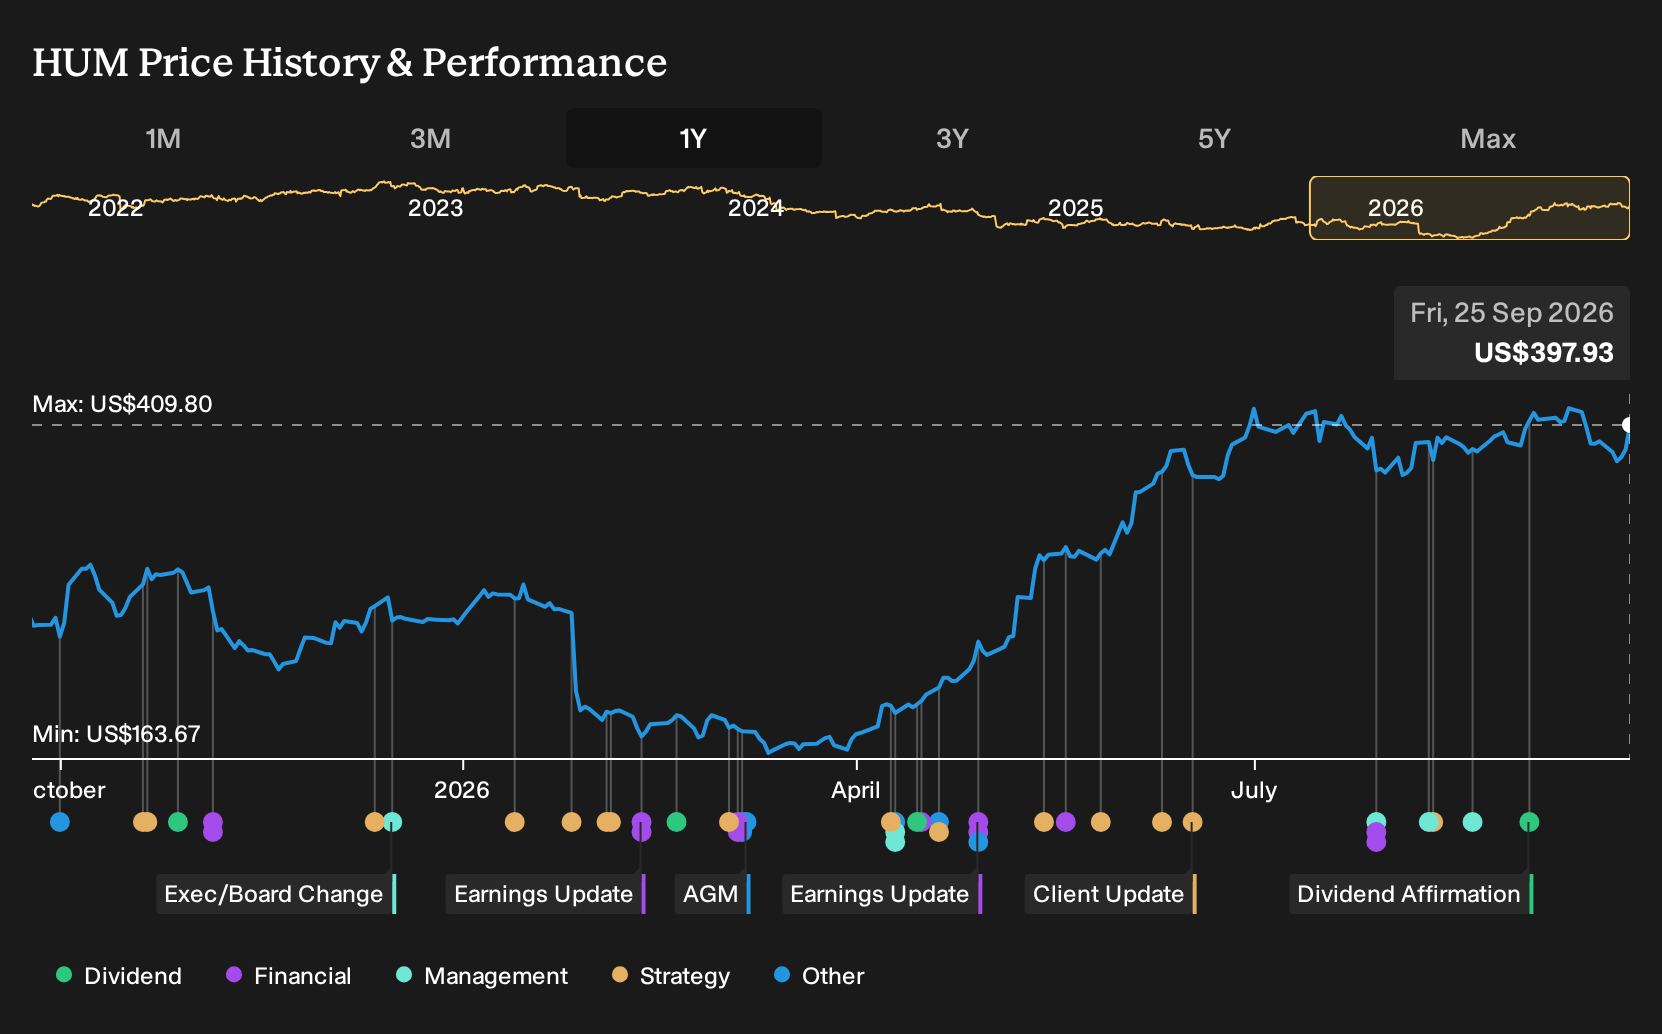
Does Barclays Upgrade Change The Bull Case For Humana Stock (HUM)?
- Humana recently drew attention after expectations strengthened that its Medicare Advantage contracts could achieve higher quality bonus status ahead of upcoming Medicare Star ratings.
- The potential conversion of key contracts, such as H5216, to bonus status matters because it may influence Humana’s Medicare profitability mix and competitive position.
- We will now look at how Humana's investment narrative could be affected by confidence in upcoming Medicare Star ratings performance.
Scan how other insurers and healthcare names are positioned for similar rating or upgrade catalysts by reviewing our curated list of list of solid balance sheet and fundamentals (24 results).
Humana Investment Narrative Recap
To own Humana, you need to believe that the Medicare Advantage margin restoration plan and CenterWell expansion can offset recent pressure on profitability and regulatory scrutiny. The near term hinge point remains Medicare Star ratings and the migration of members out of lower return plans. The Barclays upgrade does not change that core thesis; instead, it signals higher confidence that execution could support that story.
The biggest risk today is still operational. Exits from Medicare Advantage products covering about 600,000 members could weigh on revenue if fewer than expected stay with Humana in higher value plans. Ongoing oversight of coding and Stars litigation could also affect reimbursement, quality bonuses, and the timing of any margin rebuild.
The Barclays move to an Overweight rating, and the decision to raise the price target, ties directly to expectations for better Medicare Star outcomes and potential conversion of contracts like H5216 to bonus status. That call connects closely to Humana’s multiyear plan to reach at least a 3% pretax Medicare Advantage margin by 2028, where quality scores and reimbursement terms play an essential role.
For you, the useful takeaway is not the rating label itself but what it implies about operational expectations. The upgrade leans on an assumption that Stars performance, bid discipline for 2027, and member retention as 600,000 lower return plans are pruned can support earnings and net margins. If Stars or member recapture disappoint, that same thesis can unwind quickly.
Humana's current analyst narrative points to revenues of US$187.3b and earnings of US$3.4b by 2029, anchored to an assumed 8.7% yearly revenue growth rate. That path implies an earnings increase of about US$2.1b from US$1.3b today.
Discover how Humana's fair value indicates a 5% potential upside to its current price before this gap closes.
Exploring Other Perspectives
Some of the most optimistic analysts focus heavily on Medicare Advantage and CenterWell as long term demand drivers for Humana. Before this Barclays upgrade, the bullish camp was penciling in about US$207.8b of revenue and US$4.2b of earnings by 2029. That is far above consensus and could shift again once this news fully sinks in.
Explore 5 other Humana fair value estimates, including one that suggests as much as 154% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Humana research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Humana. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Humana's overall financial health at a glance.
Looking For More Ideas Beyond Humana?
Once you are clear on how Humana fits into your portfolio, it can help to cross check your thesis against other stocks with different risk and income profiles using the Simply Wall St screener.
- For investors who want quality on sale, scan a curated set of companies trading at what may be attractive valuations with 32 high quality undervalued stocks.
- If steady income matters most to you, filter for businesses with strong yields and a focus on resilience using 8 dividend fortresses.
- For a focus on durable balance sheets and fundamentals, broaden your research with a diversified 30 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com