
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Learn Why The Bull Case For Loblaw Stock Could Change Following AI Warehouse Automation
- Loblaw Companies and EAIGLE expanded their partnership in September 2026 to roll out Vision AI gate automation across multiple distribution centres, using AVAC technology to digitize vehicle access control, capture freight data in real time and integrate with WMS, TMS, YMS and ERP systems.
- The move turns Loblaw Companies' distribution gates into live data hubs rather than choke points, giving operations teams richer visibility into yard activity, tighter control of processing times and more accurate information to manage costs and keep goods moving efficiently.
- The next section examines how Loblaw Companies' wider investment narrative may be influenced by this AI driven yard automation initiative.
Scan how Loblaw Companies' AI heavy yard upgrade compares with other logistics and infrastructure plays by reviewing a hand picked group of 85 AI infrastructure stocks in one place.
Loblaw Companies Investment Narrative Recap
To own Loblaw Companies, you need to be comfortable with a mature grocer and pharmacy operator that leans on operational execution, steady earnings and cost control rather than rapid expansion. The near term story centers on whether management can keep margins resilient as consumers chase value formats and online rivals pressure pricing. The EAIGLE rollout supports that cost discipline but does not transform the thesis on its own.
The bigger near term risk still sits in margin compression and regulatory scrutiny on food pricing, not whether yard gates are automated. Heavier capital spending on distribution and digital projects can also weigh on returns if demand softens or cost savings arrive slowly. The AI gate project plugs into this broader capital expenditure cycle and slightly increases the execution bar around logistics efficiency.
The recent EAIGLE partnership extension is the clearest operational announcement tied to this theme. Loblaw Companies is scaling Vision AI and AVAC across several yards to cut processing times, improve data quality and reduce friction at distribution centers. For an investor, this fits neatly into the existing supply chain automation catalyst already highlighted in the broader narrative.
Yard automation sits in the same category as automated distribution centers, discount format expansion and digital tools such as PC Optimum. It touches key swing factors for the stock, including logistics costs, inventory reliability and the risk that online and global competitors pressure Loblaw on price and service levels. Execution quality on this rollout, and evidence that it supports stable margins, will likely matter more than the headline itself.
Loblaw Companies is currently modeled by analysts to reach CA$71.4b in revenue and CA$2.8b in earnings by 2029. That profile lines up with a 3.1% yearly revenue growth assumption and an earnings increase of about CA$0.1b from CA$2.7b today, based on the latest consensus figures.
Discover how Loblaw Companies' fair value indicates a 10% potential upside to its current price that may not last much longer.
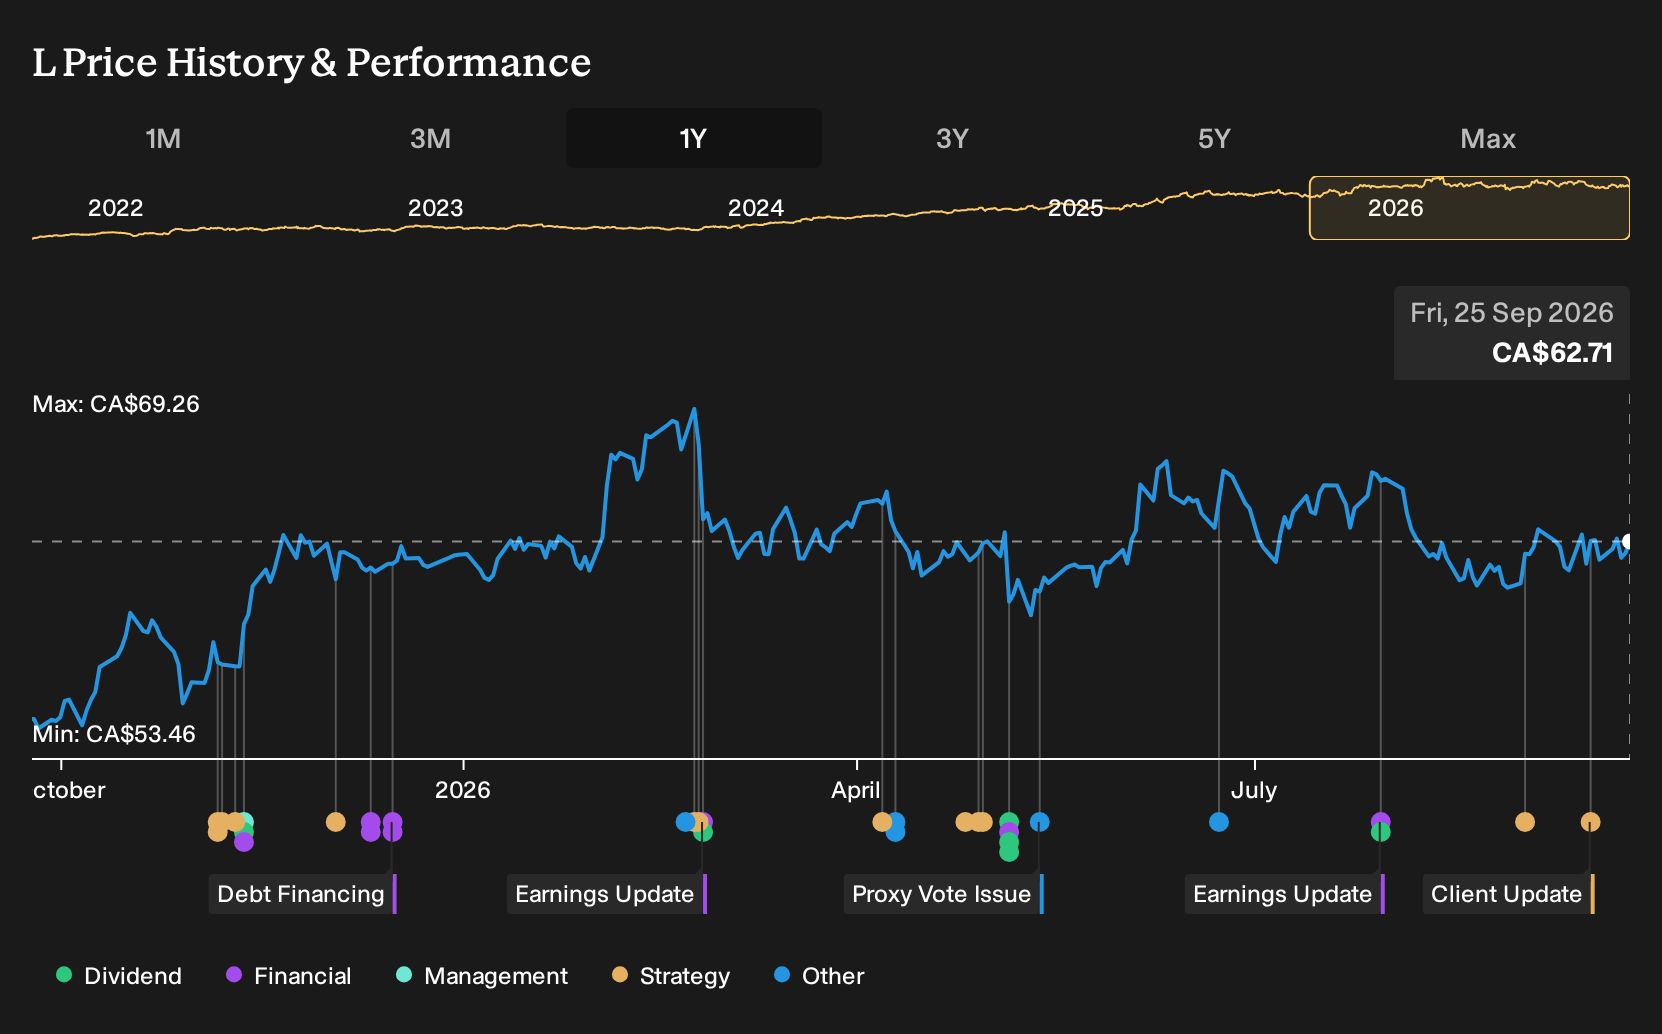
Exploring Other Perspectives
One alternate view focuses less on Loblaw Companies' AI yard upgrades and more on e-commerce risk. The most cautious analysts were already pencilling in revenue of about CA$70.6b and earnings near CA$3.5b by 2029, yet still saw a price target of CA$53.58. That illustrates how sharply opinions can differ and why fresh news like this might eventually influence those narratives.
Explore 4 other Loblaw Companies fair value estimates, including one that suggests as much as 21% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Loblaw Companies research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Loblaw Companies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Loblaw Companies' overall financial health at a glance.
Looking For More Investment Ideas Beyond Loblaw Companies?
If the Loblaw Companies story has you thinking about where to put the next dollar of your portfolio, it can help to scan a broader set of businesses with clear financial traits rather than just chasing the latest headline.
- For investors who want potential upside without ignoring balance sheet strength, consider a curated 9 high quality undiscovered gems that already show solid fundamentals and room to grow.
- If resilience matters more than excitement, filter for companies with steadier profiles using a 8 resilient stocks with low risk scores that screens out weaker financial structures and fragile earnings profiles.
- Income focused investors can zero in on cash returns by checking a list of 1 dividend fortresses that combine higher yields with an emphasis on sustainability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com