
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What Starbucks Store Closures Mean For Shareholders
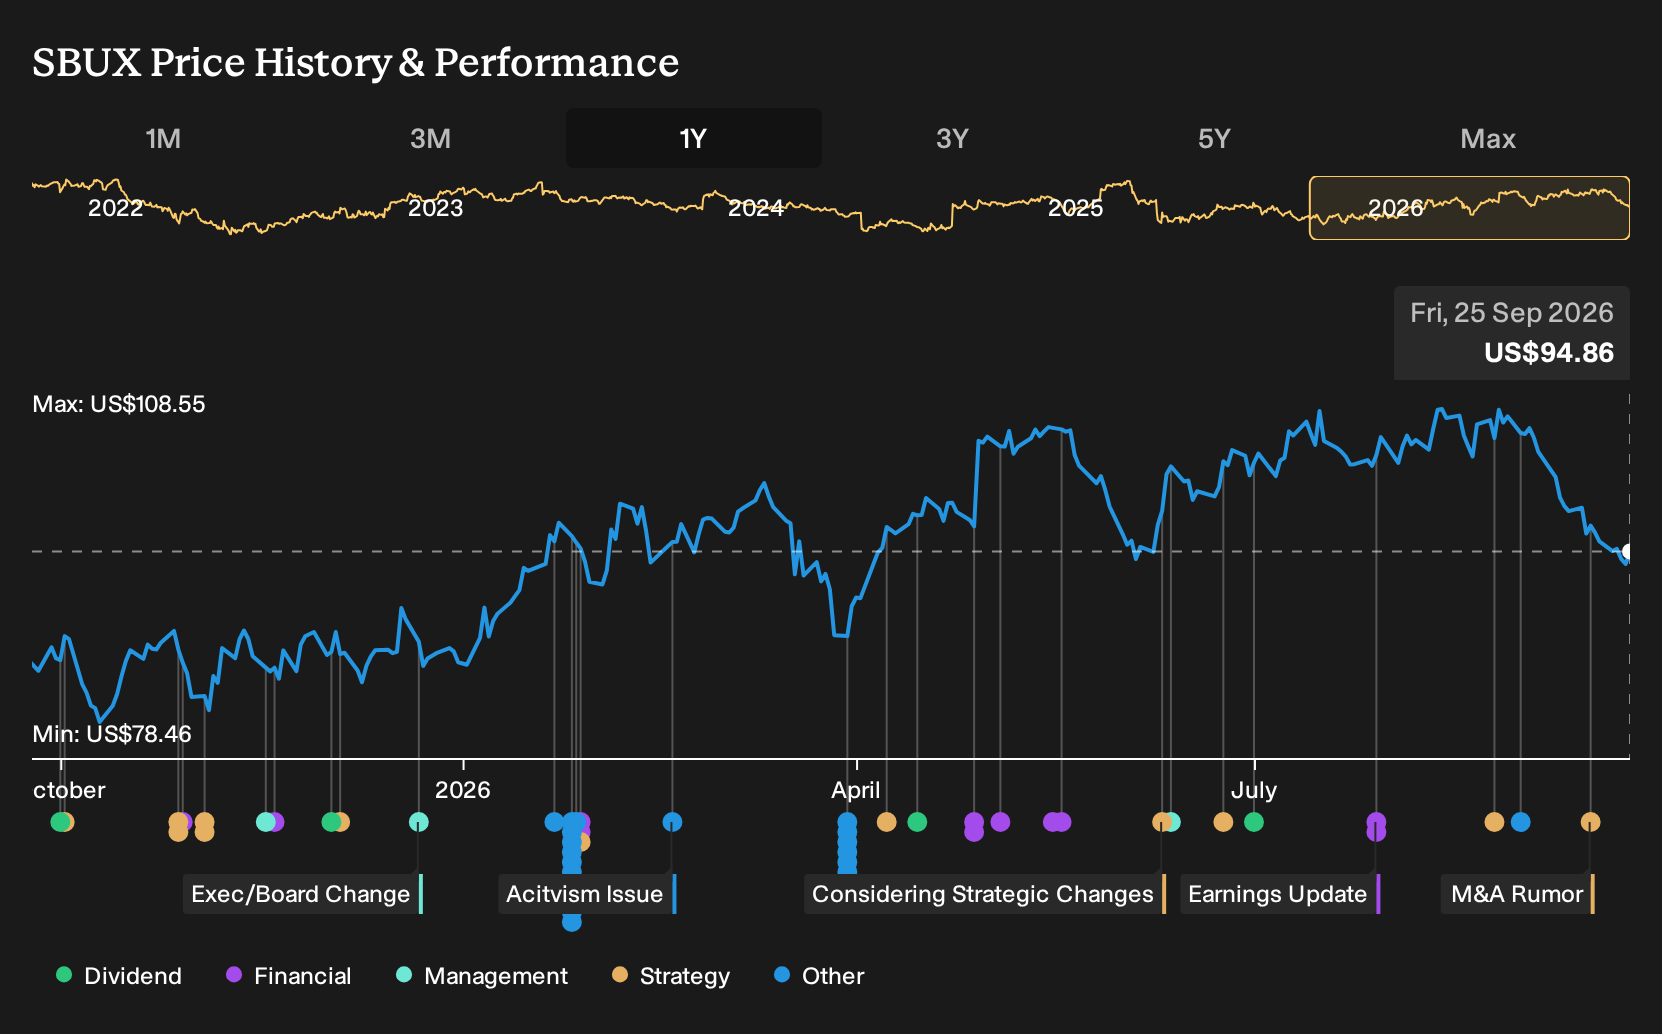
- Starbucks plans to close about 250 underperforming North American stores, roughly 1% of its regional footprint, as part of the Back to Starbucks turnaround plan. The plan also includes café remodels, a new India tech hub and an estimated US$300 million in restructuring charges.
- The same push to trim weaker locations sits alongside a potential majority sale of Starbucks Japan and a US$1 million hiring practices settlement. Together, these moves show management is reshaping both the store base and corporate structure to focus resources on higher returning markets and tighter cost control.
- We will look at how Starbucks' investment narrative is affected by closing 250 underperforming North American stores under the turnaround plan.
Scan how Starbucks' restructuring playbook compares with other businesses that are tightening up their portfolios by reviewing a curated list of 30 resilient stocks with low risk scores.
Starbucks Investment Narrative Recap
To own Starbucks today, you need to believe the Back to Starbucks plan can lift profitability from a still compressed 5.2% net margin and translate the US$2b cost program, store uplifts and tech spend into cleaner execution. The near term swing factor is whether store closures, remodels and labor initiatives actually show up as steadier earnings rather than just noise.
The biggest risk remains cost pressure from unionisation, compensation upgrades and legal or regulatory challenges that raise compliance and wage bills. The 250 closures look material for local workers but modest against an 18,000 plus North American base, so the headline sounds bigger than the likely immediate hit to overall economics.
The potential majority sale of Starbucks Japan is the announcement that matters most alongside these North American cuts. Japan accounts for 1,883 stores and nearly 9% of the global footprint, so any move toward a capital light model there would echo the recent China shift and could reshape how investors think about the mix between owned and partnered markets.
For catalysts, a Japan deal would test Starbucks’ ability to convert mature international assets into cash and fee streams while keeping brand strength and same store momentum intact. The execution risk is real. Management would be juggling a complex carve out while still trying to close the margin gap, fund thousands of US remodels and keep labor relations from eroding progress.
Starbucks' current story assumes revenue will grow by 3.7% per year and that earnings will rise from US$2.0b today to US$4.7b by 2029, a US$2.7b increase. This implies the business would be generating US$42.8b in revenue and US$4.7b in earnings by that same 2029 forecast year.
Uncover why Starbucks' fair value indicates an 18% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts were already betting that Starbucks could reach about US$43.2b in revenue and US$5.6b in earnings by 2029, largely on faster international and digital expansion. You can now weigh those upbeat expectations against the fresh Japan stake sale talk and new store closures, and decide which story feels more realistic.
Explore 4 other Starbucks fair value estimates, including one that suggests as much as 46% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Starbucks research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Starbucks. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Starbucks' overall financial health at a glance.
Looking for more investment ideas beyond Starbucks?
If the Starbucks story has sharpened your thinking, you can use that same lens across the wider market. A targeted screener can help you quickly surface stocks that fit the risk, quality and income profile you care about most.
- For investors who want potential upside with a margin of safety, you can start with companies that screen well on quality and valuation by running a search across 32 high quality undervalued stocks.
- If balance sheet strength matters most to you, you can focus on businesses with robust financial footing by filtering for a list of solid balance sheet and fundamentals (24 results).
- For those building a more conservative core around stability and risk control, you can narrow your watchlist to a set of 30 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com