
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Insurance Stocks Tied To British Airways Crew Legal Risk
Legal risk around airline crew contracts is moving from the footnotes of annual reports to courtroom headlines, and insurers that touch aviation liability such as British Airways related cover are suddenly in sharper focus. For investors, that kind of spotlight can reshape how the market prices risk. This piece examines the British Airways dispute and then outlines three stocks exposed to the same legal theme that could matter for a diversified portfolio.
The insurers highlighted below are just a starter set, and the wider screen surfaced 5 more UK and European aviation labour liability specialists with equally compelling stories that are not covered here. To go straight to the full list, use the UK & European Aviation Labour-Liability Insurers screener to identify, analyze, and focus on the highest conviction ideas.
Hannover Rück (XTRA:HNR1)
Overview: Hannover Rück is a global reinsurer that covers property, casualty, and life and health risks, including aviation and employers’ liability.
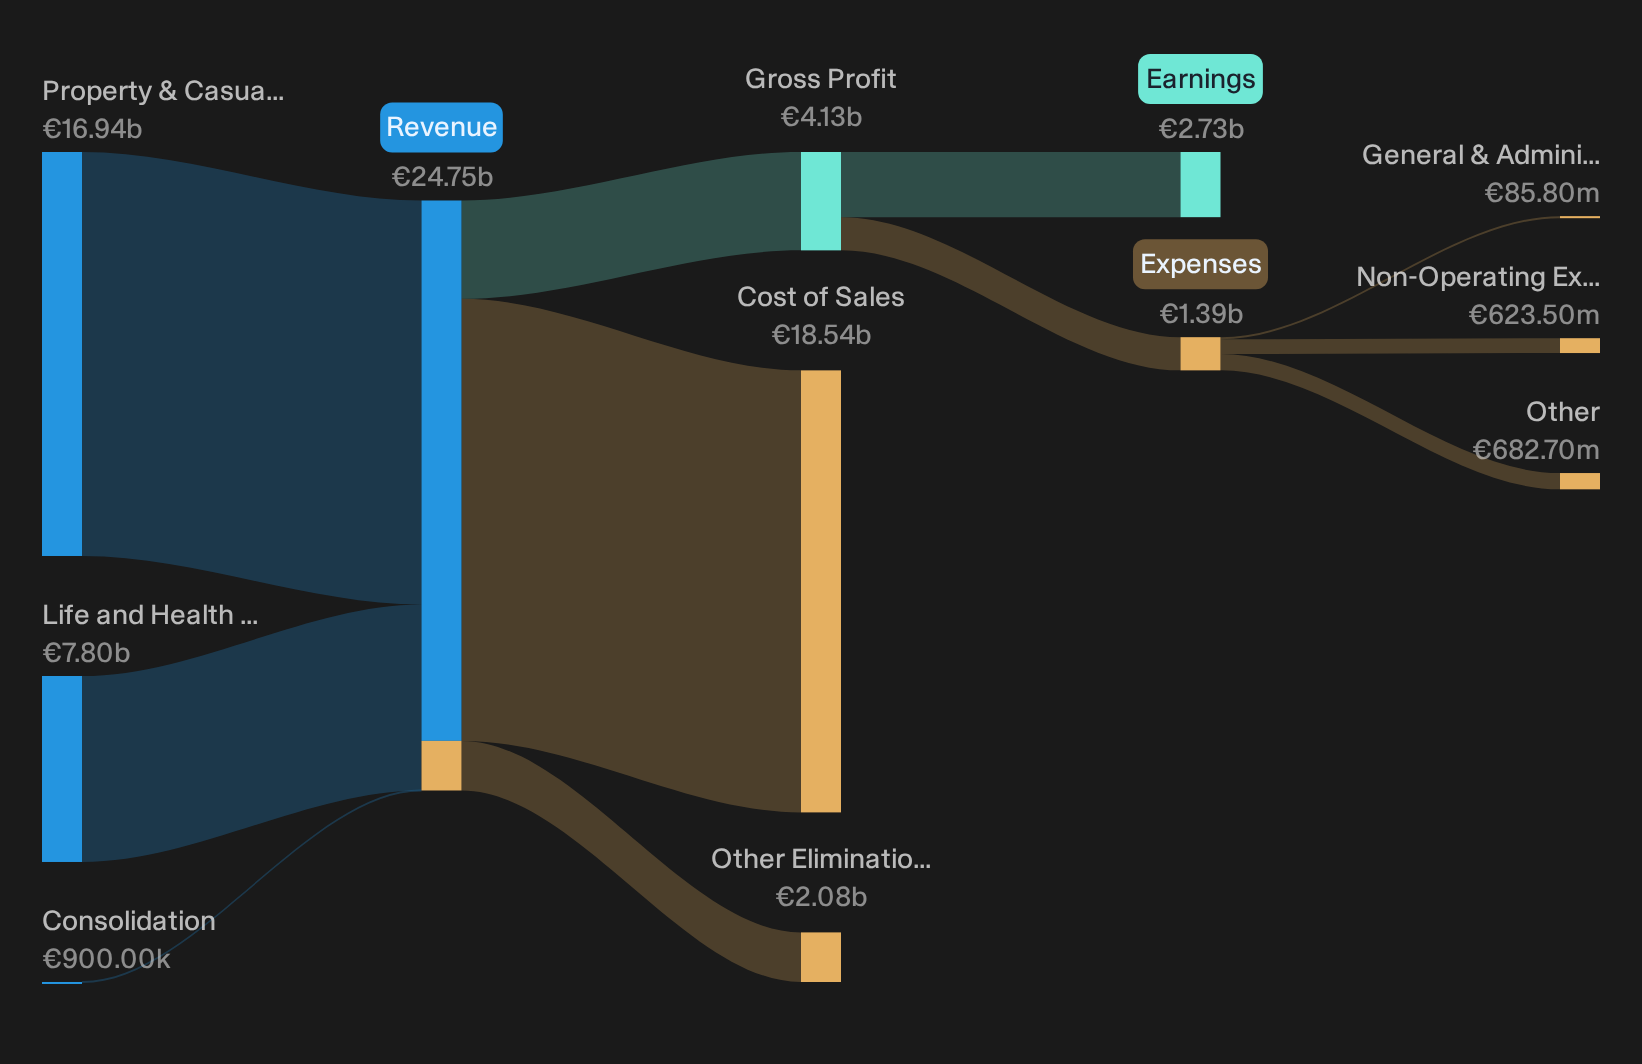
Operations: Hannover Rück generates about €16.9b from Property & Casualty Reinsurance and €7.8b from Life and Health Reinsurance, with minimal consolidation effects.
Market Cap: €31.1b
Hannover Rück matters in this aviation labour-liability screen because its broad reinsurance book can absorb and reprice exactly the kind of crew-related risks now facing European airlines, including British Airways.
"The company's disciplined expansion into high-value specialty lines and emerging risk sectors, such as cyber and health reinsurance, offers an untapped runway for diversified premium growth, which could accelerate total revenue growth and raise earnings quality as the global demand for such solutions expands."
What investors will watch closely is how one quiet shift in liability pricing power feeds through to Hannover Rück’s margins and capital flexibility.
If that shift in pricing power is what you care about, read the full narrative for Hannover Rück to see how reinsurance cycles, capital strength and crew risks intersect.
Lancashire Holdings (LSE:LRE)
Overview: Lancashire Holdings is a specialty insurer and reinsurer focused on complex property, energy, marine and aviation liability risks across global markets.
Operations: Lancashire generates about $673 million from Insurance and $666 million from Reinsurance, with an additional $161 million from investment returns across mainly US, multi territory and European business.
Market Cap: £1.6b
Lancashire Holdings matters for this aviation labour-liability theme because its London market franchise already prices complex airline and crew-related cover where legal risk is rising.
"Ongoing demand for specialty (re)insurance products, influenced by the increasing frequency and severity of natural catastrophes globally, has supported growth in premium revenues and created opportunities for disciplined margin management as Lancashire has focused on underwriting resilience and adaptability."
A key factor that could affect the story for Lancashire Holdings is how one emerging pressure on specialty pricing ultimately filters through to underwriting margins.
That pressure point on margins is exactly what the full narrative for Lancashire Holdings unpacks, showing where Lancashire Holdings could see pricing power accelerate or quietly stall.

AXA (ENXTPA:CS)
Overview: AXA is a global insurer and asset manager that covers everyday risks through to complex commercial and aviation-related liability cover.
Operations: AXA generates about €37.3b from Europe, €25.1b from France, €19.4b from AXA XL, and €14.0b from Asia, Africa and EME LATAM.
Market Cap: €89.0b
AXA matters in this aviation labour-liability screen because its large European commercial book can absorb and share the kind of workplace and aviation-related crew risks now testing airlines like British Airways.
"Strong momentum in digitalization, AI adoption, and streamlined direct distribution (bolstered by the Prima acquisition) is expected to support future efforts to enhance cost efficiencies, customer acquisition, and presence among digitally focused, price-sensitive, and underserved customer segments."
What could really shift the AXA story is how one unseen cost and claims pressure interacts with that efficiency push to shape long term margins.
That margin story is just the start, and the full narrative for AXA shows how AXA’s pricing power, digital push and crew risk exposure could be quietly decoupling.

Seeking Alternatives Before The Crowd
Fresh momentum can fly past fast. Some of the most interesting ideas move from under the radar to fully priced while it still matters. Do not get caught dropping in late; get in early.
- Target reliable cash generators and strengthen your core holdings with a curated list of solid balance sheet and fundamentals (201 results) that helps you focus on financial resilience while prices still look reasonable.
- Ride potential income momentum by scanning a hand picked pool of 159 dividend fortresses that could keep portfolios paid while others chase stories without cash returns.
- Position ahead of the next infrastructure breakout using a filtered set of 40 power grid technology and infrastructure stocks that connect real assets, energy demand and long term capital deployment.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com