
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Panasonic Holdings (TSE:6752) Pushes NMC Battery Investment, Is The Stock Too Pricey?
Panasonic Holdings (TSE:6752) is ramping up investment in Nickel Manganese Cobalt battery technology, tying that commitment to deeper partnerships with automakers and grid storage providers as electrification demand shapes long-term revenue opportunities.
Panasonic Holdings has ridden a strong wave of optimism, with the share price at ¥4,588, a year-to-date share price return of 120.74%, and a 1-year total shareholder return of 180.93%. Together, these figures point to powerful momentum rather than a short-lived bounce.
Scan beyond Panasonic Holdings and spot other electrification plays with strong momentum by reviewing the hand picked 85 AI infrastructure stocks shaping the grid and EV supply chain.
After a 180.93% 1-year total return, Panasonic Holdings now sits at ¥4,588, and a clear fork in the road appears. Is the better move to step in at this level or wait for a cooler entry point as the valuation picture comes into focus next?
Most Popular Narrative: 4% Undervalued
Panasonic Holdings is trading at ¥4,588 against a widely followed fair value estimate of ¥4,783, which points to a modest valuation gap that investors are weighing against the recent share price surge.
Demand for industrial energy storage systems is accelerating beyond initial expectations due to large-scale data center investment driven by generative AI adoption, which is likely to support revenue growth and improve recurring earnings quality in the Energy segment.
Despite a near-term EV slowdown in North America from policy headwinds (IRA tax credit termination, tariffs), Panasonic's locally produced, IRA-compliant battery cells and new high-capacity cell technology are sustaining strong customer demand, positioning the company for volume growth and higher net margins as electrification resumes its long-term trend.
See why 23 investors see Panasonic Holdings as 4% undervalued.
Result: Fair Value of ¥4,782.79 (UNDERVALUED)
Still, slower EV uptake in North America and delays in portfolio restructuring, including underperforming assets like Blue Yonder, could quickly challenge this Panasonic Holdings upside story.
Find out about the key risks to this Panasonic Holdings narrative.
Another View On Panasonic Holdings Valuation
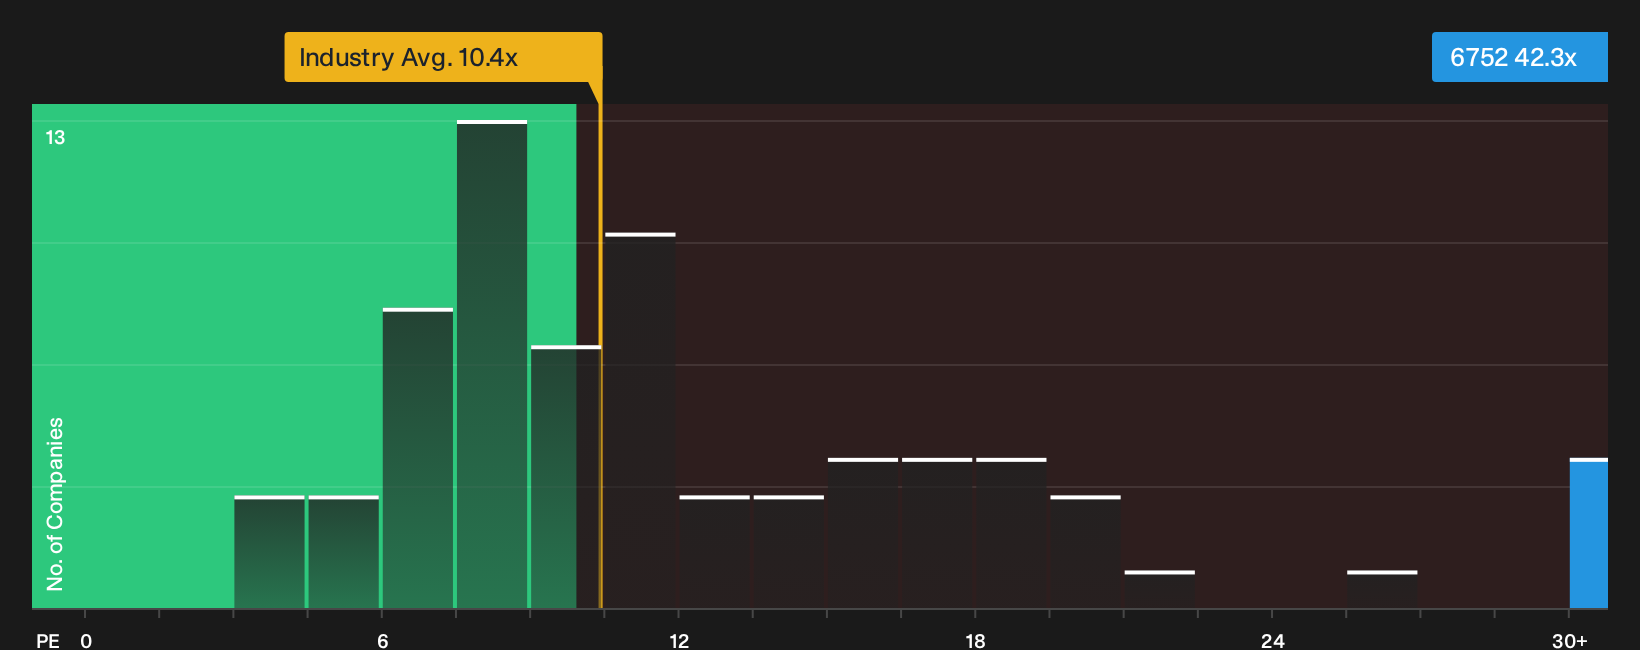
The first take presents Panasonic Holdings as about 4% undervalued versus a ¥4,783 fair value, based on future cash flows and analyst targets. A second lens, plain P/E, tells a sharper story. The shares trade on 42.3x earnings compared with a fair ratio of 35x, peers at 19.6x, and the wider JP Consumer Durables group at 10.4x.
That gap suggests investors are paying a heavy premium for the Panasonic Holdings narrative, even with discounted cash flow analysis indicating potential value. The key question is whether you think the earnings path ahead is strong enough to keep that premium intact.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Unsure about the enthusiasm around Panasonic Holdings at this price? Move quickly, consider both sides of the story, and ground your own view in the underlying facts by weighing the 2 key rewards and 3 important warning signs
Looking for more Panasonic Holdings style ideas?
If Panasonic Holdings has sharpened your focus on where capital goes next, do not stop here. Broaden your watchlist now so you are not chasing the next move late.
- Target quality at a discount by scanning the 19 high quality undervalued stocks that pair solid fundamentals with prices that sit below many investors' radar.
- Build a steadier income stream by reviewing the 14 dividend fortresses that combine higher yields with payout profiles many investors look for.
- Strengthen downside protection by checking the 21 resilient stocks with low risk scores that score well on financial resilience and business stability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com