
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Arkansas Expansion Could Be A Game Changer For UL Solutions (ULS)
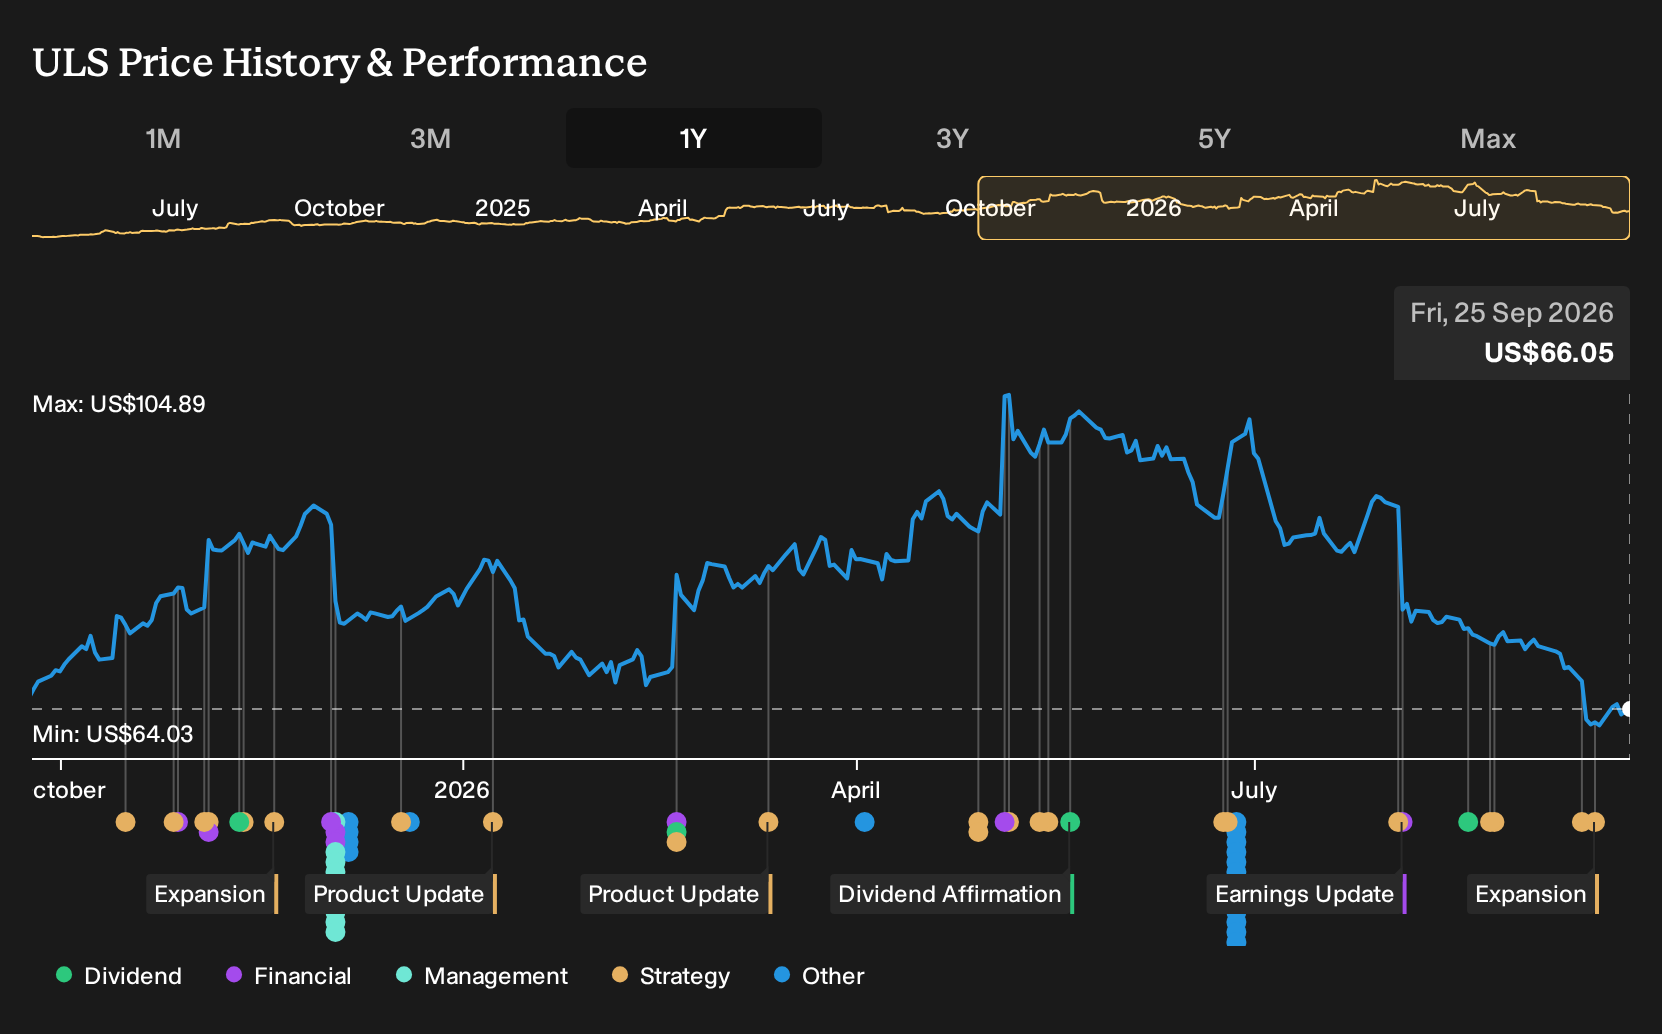
- UL Solutions expanded its Lowell, Arkansas Retail Center of Excellence in 2026, integrating apparel and textile softlines testing with existing hardlines capabilities and adding vehicle to grid certification services supported from other laboratories.
- The move tightens UL Solutions’ link to major retailers clustered in Northwest Arkansas while deepening its role in emerging V2G safety and reliability standards, both of which speak directly to how the business earns testing and certification fees.
- We will look at how UL Solutions’ investment narrative is influenced by the expanded Arkansas testing hub and its new V2G certification work.
UL Solutions Investment Narrative Recap
To stay invested in UL Solutions, you need to be comfortable with a capital intensive testing model that leans on recurring certification fees and disciplined cost control, while analysts expect earnings to drift slightly lower over the next three years. The Lowell expansion and V2G launch support the long run story but do not radically change that near term earnings debate.
The more immediate swing factor is execution on new labs and programs without squeezing free cash flow too hard. The biggest risk right now is spending heavily on capacity from Arkansas to Japan while end demand slows or one off gains fade, which could make the current P/E premium harder to justify.
The new vehicle to grid certification program looks most relevant for UL Solutions because it ties directly into how the group earns high margin testing and compliance fees from complex electrical equipment. It connects cleanly with existing distributed energy and EV charging work, which can deepen relationships with utilities and auto related clients if uptake is solid.
This program also speaks to the current catalyst risk mix. Strong early traction could support the view that recent earnings growth is not just about one time items and that new labs in places like Fremont and Northbrook can stay busy. Slower adoption would leave UL Solutions relying more heavily on mature certification lines while still carrying higher fixed costs from recent expansion.
UL Solutions' current analyst storyline points to revenues of $3.8b and earnings of $492.1 million by 2029, based on forecast top line growth of 6.1% a year and an earnings decline of $13.9 million from $506.0 million today.
Uncover why UL Solutions' fair value indicates a 49% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One wildcard is lab utilization. The most bearish UL Solutions analysts already expected only about 5.4% annual revenue growth to roughly $3.7b by 2029 and earnings of $524.7 million, and that view came before the Lowell and V2G news. Those forecasts reflect a much more cautious narrative on how new capacity might actually be used.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your UL Solutions research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for UL Solutions. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate UL Solutions' overall financial health at a glance.
Looking for more UL Solutions style investment ideas?
If the UL Solutions story has you thinking about where testing, reliability and steady fee income might show up next in your portfolio, the Simply Wall St Screener can help you cast a wider net while staying focused on quality and risk.
- If you value stability and want to keep potential drawdowns in check, start with a set of 30 resilient stocks with low risk scores that already screen well on resilience and balance sheet strength.
- For investors hunting for quality at a reasonable price, build out your watchlist with 16 high quality undiscovered gems that the market may not be paying close attention to yet.
- If consistent income matters to your plan, focus on yield and staying power with a group of 8 dividend fortresses that combine higher payouts with robust fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com