
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Japanese Consumer Stocks Retail Investors Are Watching After The Bank Of Japan Rate Shift
Japan has just moved from ultra-cheap money to a 1.25% policy rate, and that shift puts domestic consumption back in the spotlight. A firmer yen can squeeze exporters while giving local consumers a little more breathing room on imported costs. That mix can reward some Japanese domestic consumption stocks more than others. This article examines three companies exposed to this rate story and explains why their share prices might react very differently from export-heavy peers.
The stocks in the spotlight below are just a small sample of Japan focused consumer plays, and the same screen surfaced 31 more domestically tilted companies with equally compelling stories that are not covered here. To size up that wider group and identify your own high conviction ideas, head straight to the Japanese Domestic Consumption Stocks screener.
Sugi HoldingsLtd (TSE:7649)
Sugi Holdings runs a nationwide drugstore and pharmacy chain in Japan, squarely tied to domestic consumer spending on everyday healthcare and household needs. It generates about ¥1.0t from its Drugstore and Pharmacy Business in Japan and carries a market value of roughly ¥455.7b.
Sugi Holdings gives you direct exposure to Japan’s everyday shopper, from prescription drugs to household essentials, at a time when a stronger yen helps keep imported costs in check and real incomes a little healthier. The stock ties that domestic demand story to one unresolved pressure that could reshape how much of each yen spent actually falls to the bottom line.
That unresolved pressure is exactly what sits at the heart of the 3 key rewards and 1 important warning sign, pointing to where Sugi HoldingsLtd’s earnings profile could really shift.

Tsuruha Holdings (TSE:3391)
Tsuruha Holdings runs a nationwide Japanese drugstore network focused on daily necessities, with all ¥1,814.9b in sales coming from pharmaceuticals and cosmetics in Japan, and carries a market value of about ¥982.3b.
Tsuruha Holdings is closely linked to Japan’s consumer economy, with all revenue tied to domestic shoppers buying medicines, cosmetics and everyday goods. The business combines forecast earnings and revenue growth with a steady dividend. One funding choice could meaningfully sway future profitability for this retailer of daily essentials if a single key assumption breaks.
If that leverage on a single funding choice worries you, jump into the 5 key rewards and 1 important major warning sign to see where Tsuruha Holdings’ earnings path could sharply decouple.

Ajinomoto (TSE:2802)
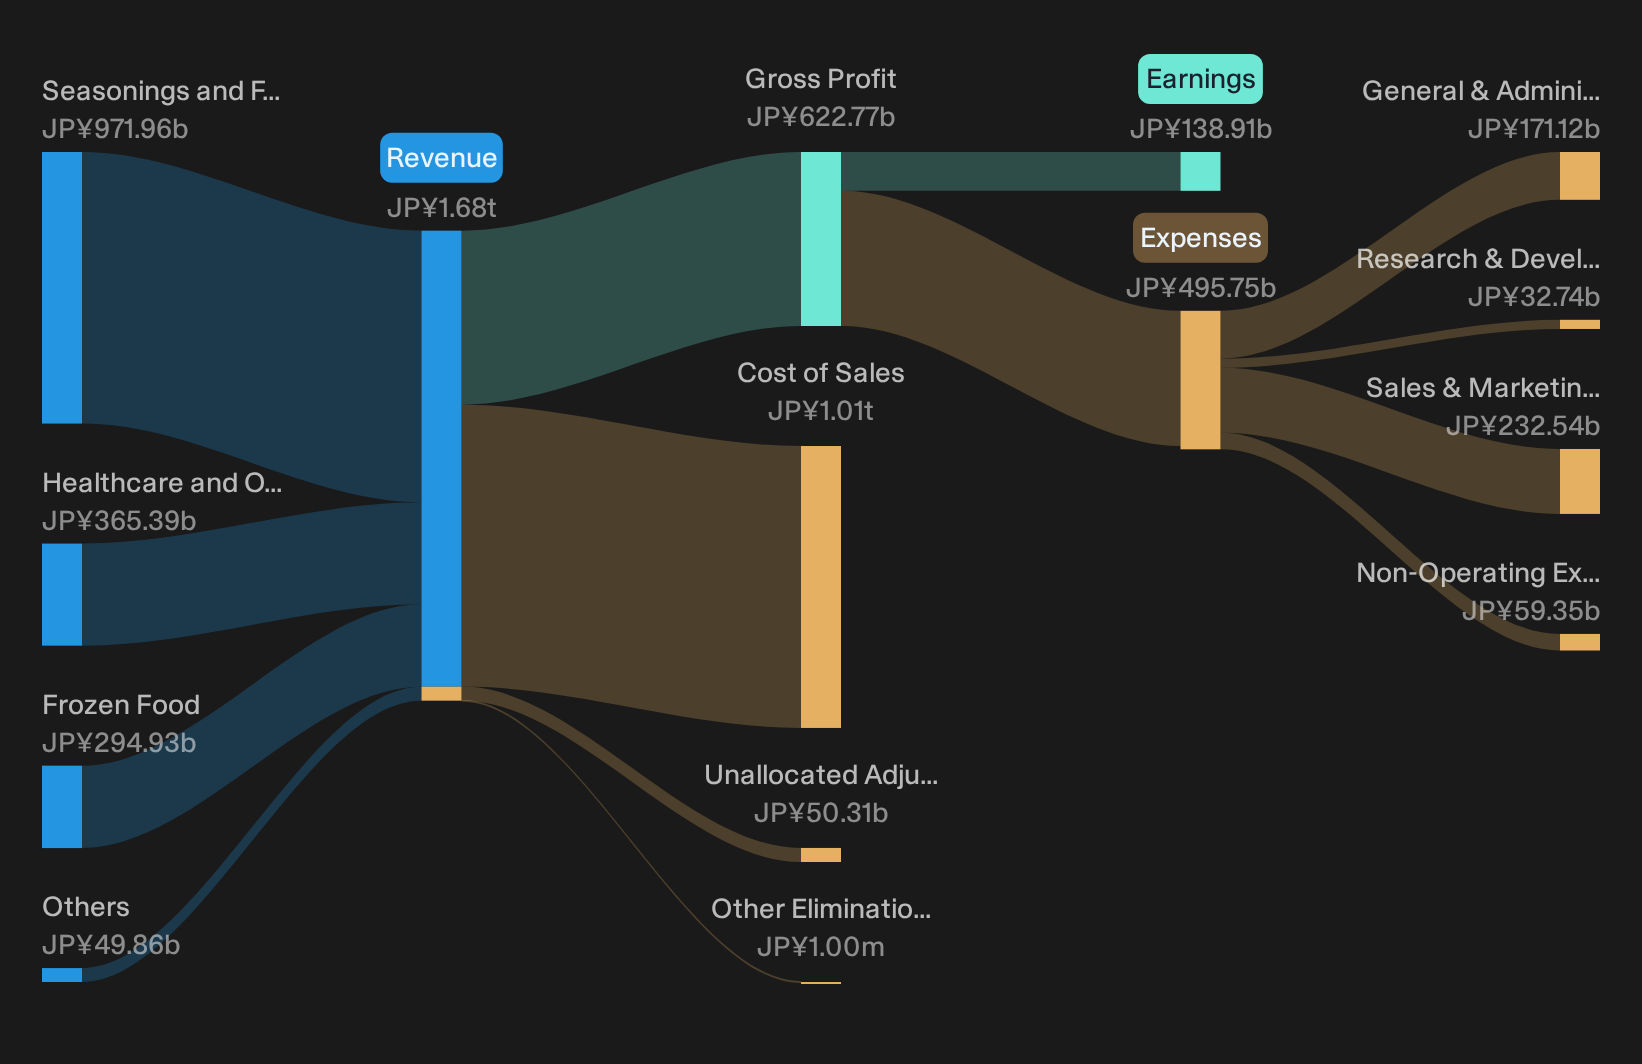
Ajinomoto plugs directly into Japan’s consumer economy through seasonings, sauces, and frozen foods that sit in local kitchens and supermarket freezers, while also running a growing healthcare and specialty materials arm.
The Seasonings and Foods segment generates about ¥972b, Frozen Food adds roughly ¥295b, Healthcare and Others contributes around ¥365b, and the group’s market value sits near ¥4,821.5b.
Ajinomoto gives this domestic consumption screen exposure to everyday meals plus higher value health-focused products at a time when a firmer yen can ease import costs and support grocery budgets, which may allow for a more profitable mix shift.
Structural portfolio transformation, away from commoditized lines and toward high-value specialty ingredients and wellness solutions, is proceeding rapidly. There are early indications that recurring revenue businesses and higher-margin healthcare applications could account for a materially larger share of revenue over time, which may support net margins and earnings resilience.
What may really matter now is how one quiet change in that product mix affects pricing power and long-run profitability.
That quiet mix shift is already in motion, and the full narrative for Ajinomoto maps how Ajinomoto’s earnings engine could accelerate while key risks stay in check.
Seeking Fresh Alternatives Before Others?
Fresh ideas move first. By the time momentum shows on every chart, the best entry window can be gone. Check these under the radar lists now and act early.
- Target steady compounders with resilient cash flows by scanning a curated list of solid balance sheet and fundamentals (22 results) before the crowd starts chasing quality again.
- Explore early breakout potential across high quality, under followed companies by working through a hand picked 74 high quality undiscovered gems while they are still under the radar for now.
- Focus on structural demand for power, data and electrification by reviewing the targeted 40 power grid technology and infrastructure stocks before capital starts concentrating in the same tickers.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com