
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Earnings Guidance At Nucor (NUE) Has Changed Its Investment Story
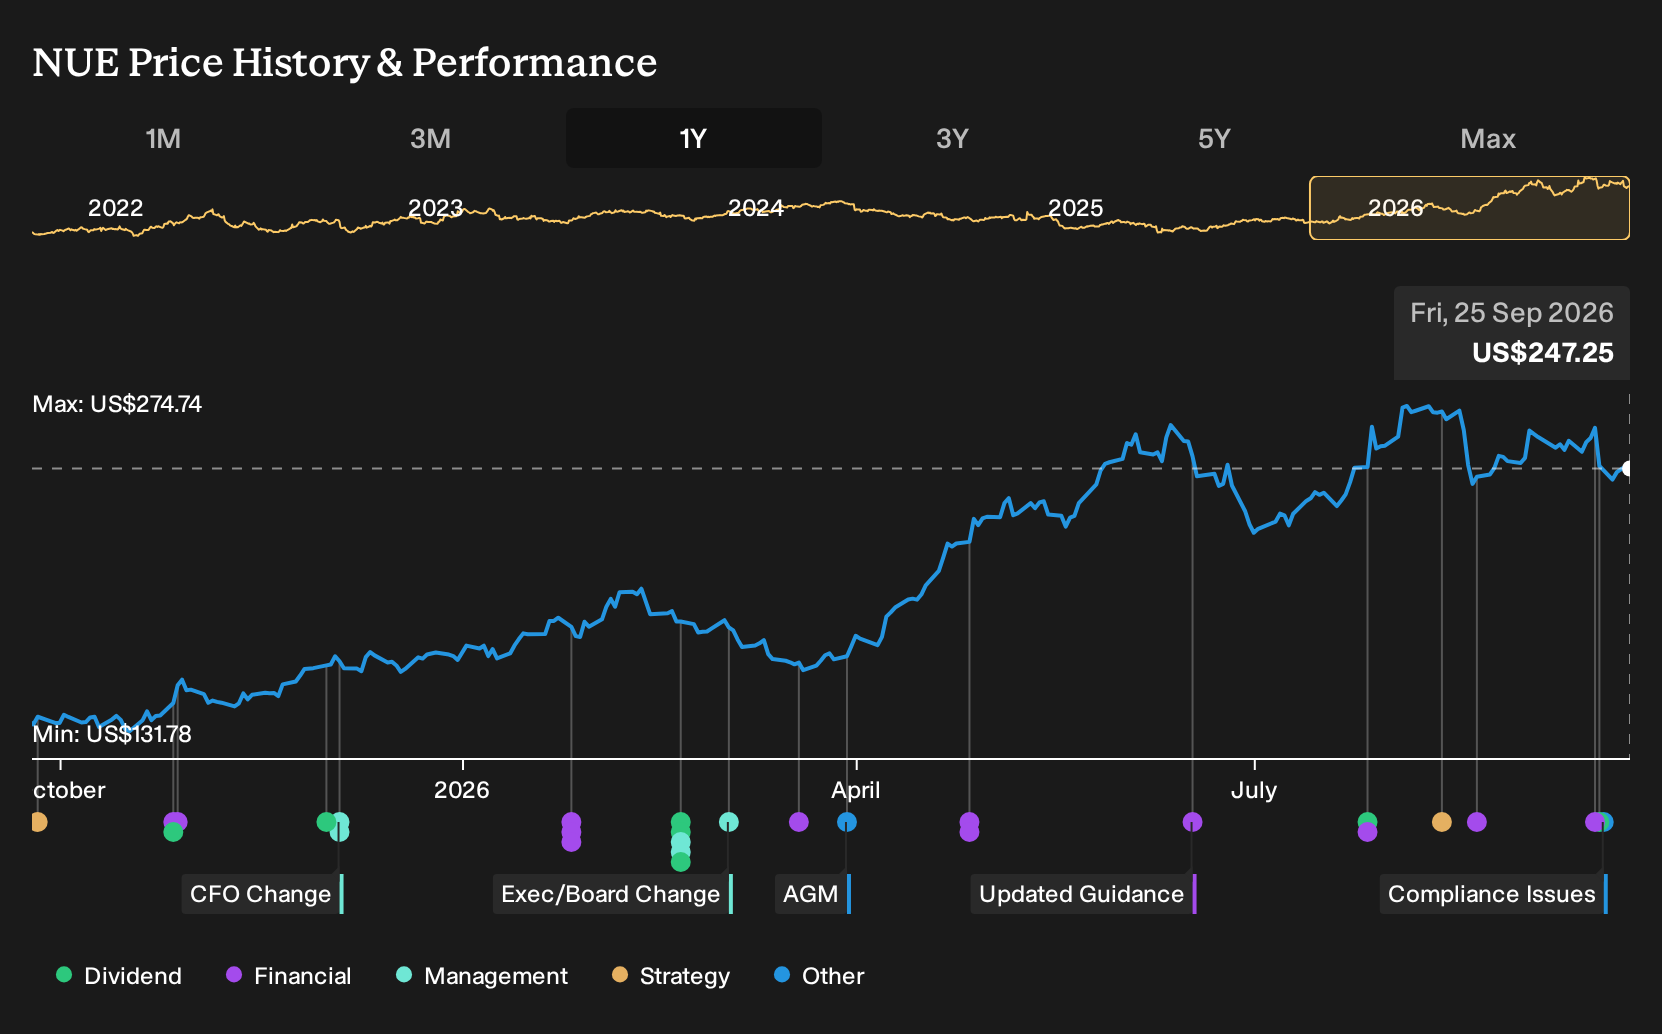
- Nucor recently issued third quarter 2026 earnings guidance, telling investors it expects between $5.55 and $5.65 in diluted EPS for the period.
- The guidance update gives a clearer view of how Nucor’s mills and downstream projects are performing relative to recent capital spending and demand assumptions.
- We will now look at how Nucor's new earnings guidance could influence the broader investment narrative around its long-term buildout.
Scan how Nucor’s latest guidance, dividend decision, and regulatory moves compare with peers by lining them up next to list of solid balance sheet and fundamentals (24 results).
Nucor Investment Narrative Recap
Nucor appeals to shareholders who believe its multi year buildout of mills and downstream assets can keep turning heavy capital spending into steadier earnings and cash flow. The new third quarter EPS guidance of US$5.55 to US$5.65 per diluted share keeps attention on short term execution. The key near term swing factor remains how reliably mill utilization and pricing hold up against macro and raw material volatility.
The biggest risk still sits in project execution and cost control, especially at newer facilities that carry start up drag. The fresh guidance does not materially change that. Investors still need to watch for any commissioning hiccups, softer nonresidential demand, or raw material mix shifts that could pressure margins and slow the cash generation phase of Nucor's capital program.
The regular US$0.56 quarterly dividend, payable on November 10, 2026, is the announcement that most directly ties into this earnings update. It marks Nucor's 214th consecutive quarterly cash dividend and indicates that the board views current cash generation as sufficient to maintain ongoing shareholder returns while large projects are still moving through ramp up periods.
For you as a holder or prospective holder, that dividend track record connects directly to the catalysts around trade protection, new mill capacity, and towers and structures growth. If those projects continue to support earnings and free cash flow over time, the ability to keep funding dividends and capital spending side by side becomes an important proof point that the broader Nucor buildout is functioning as intended.
Nucor's narrative projects US$40.5b revenue and US$4.6b earnings by 2029, which implies 3.9% yearly revenue growth and an earnings increase of about US$1.7b from US$2.9b today.
Uncover why Nucor's fair value indicates a 15% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One bullish twist you might want to stress test is energy exposure. The most optimistic Nucor watchers were penciling in revenue of US$44.8b and earnings of US$5.1b by 2029, assuming power costs stay manageable. The fresh FERC intervention shows electricity pricing could shift, so those upbeat models may need to be revisited.
Explore 3 other Nucor fair value estimates, including one that suggests up to 67% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Nucor research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Nucor. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Nucor's overall financial health at a glance.
Looking for more investment ideas beyond Nucor?
If Nucor helps frame what you want from earnings power and balance sheet strength, it can be useful to line it up against a wider mix of companies that fit different risk and return profiles using the Simply Wall St Screener.
- If you want potential mispricing with quality backstops, start with a focused group of 32 high quality undervalued stocks that pair stronger fundamentals with more conservative balance sheets.
- If resilience matters most to you, tilt your search toward 30 resilient stocks with low risk scores that screen well on financial stability and business risk scores.
- If you are hunting for income ideas, narrow your watchlist to 8 dividend fortresses that combine higher yields with a record of paying investors in cash.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com