
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Air France KLM (ENXTPA:AF) Bets On JFK Premium Push As Valuation Questions Linger
Air France-KLM (ENXTPA:AF) is shifting all New York flights to JFK's New Terminal One and opening its largest lounge worldwide, a move aimed squarely at premium travelers and loyalty-driven traffic.
Recent price action reflects this focus on higher-yield routes. Air France-KLM’s share price has risen 2.05% over the last day and 2.36% over the past week, although the 90-day share price return is down 13.55% and the 5-year total shareholder return has declined 46.11%. This suggests that short-term momentum is picking up while the long-run record remains weaker.
Scan for other carriers leaning into premium routes and loyalty economics with our curated list of 618 high quality undiscovered gems, which may be flying under most investors' radar.
Air France-KLM now trades with a long-term record that looks weak on paper, yet sits close to analyst targets and far below one intrinsic estimate. Where does a fair price really land after this JFK premium push?
Price-to-Earnings of 2.8x: Is it justified?
On current numbers, Air France-KLM trades on a P/E of 2.8x while the share price sits at €11.71, which points to an undervalued profile against both peers and one intrinsic estimate.
The P/E ratio compares what investors pay today for each euro of earnings that the airline generates. For a carrier like Air France-KLM, with €34,155.0m in revenue and €1,084.0m in net income, this measure helps you judge how the market is pricing those earnings relative to other listed airlines.
Here, the gap is wide. Air France-KLM’s 2.8x P/E is far below the peer average of 17.8x and also well under the global airlines average of 11.3x. The valuation is also below an estimated fair P/E of 13.5x, a level the market could move towards if sentiment and earnings expectations align more closely with this fair ratio view.
Explore the SWS fair ratio for Air France-KLM.
Result: Price-to-Earnings of 2.8x (UNDERVALUED)
Still, Air France-KLM runs a capital intensive model that is exposed to swings in fuel costs and relies on premium demand, which can soften if corporate or long haul travel weakens.
Find out about the key risks to this Air France-KLM narrative.
Another view on Air France-KLM’s value
The SWS DCF model paints a very different picture for Air France-KLM. On that framework, the share price of €11.71 sits well below an estimated future cash flow value of €57.69, which points to a very large implied upside. Is that a genuine opportunity or simply optimistic maths?
Our DCF model depends on long term assumptions about cash generation that may or may not play out in practice. It is worth understanding how it works before leaning on it too heavily for decisions. Look into how the SWS DCF model arrives at its fair value.
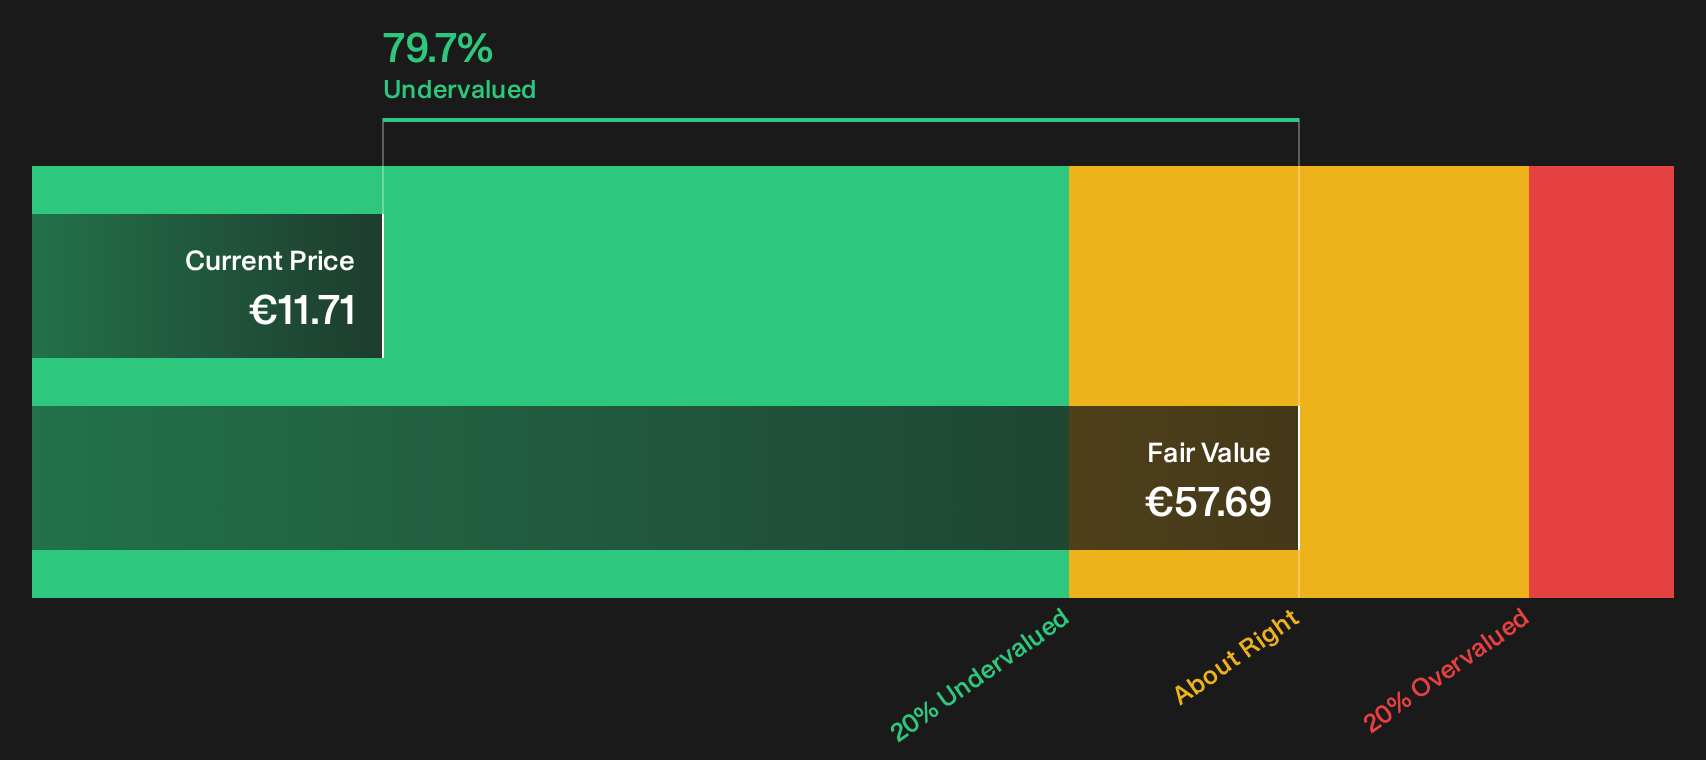
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Air France-KLM for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 184 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Curious whether the tone on Air France-KLM so far feels too cautious or not cautious enough? Act while the data is fresh and shape your own view by weighing the 4 key rewards
Looking for more investment ideas beyond Air France-KLM?
Do not stop with Air France-KLM. Broaden your watchlist with fresh ideas that match different risk levels and income goals using the Simply Wall Street screener.
- Target potential mispricings by scanning a curated set of 184 high quality undervalued stocks that combine appealing valuations with fundamental support.
- Strengthen portfolio resilience by focusing on companies with sturdier finances through a list of solid balance sheet and fundamentals (201 results).
- Seek income-focused opportunities by reviewing a handpicked group of 159 dividend fortresses that aim to provide higher yields with support from underlying metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com