
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Almonty Industries (ALM) Could Be 67% Undervalued As Tungsten Deals Lift Interest
Almonty Industries (ALM) has drawn fresh attention after a multi-year tungsten concentrate supply deal with a Sandvik subsidiary, a rebound in quarterly results, and new offtake commitments that have reshaped how investors view its tungsten footprint.
The share price reaction has been choppy, with Almonty Industries closing at $13.72 after a 1-day share price return of 10.65% and a 30-day share price decline of 23.95%. The year-to-date share price return of 55.91% sits alongside a 1-year total shareholder return of 131.37% and a very large 3-year total shareholder return, which signals longer term momentum building behind the tungsten story.
Scan the tungsten theme beyond Almonty Industries by sifting through our hand picked 36 best rare earth metal stocks that are tied to critical metals demand and supply chain security.
After a sharp one year run and a rough recent month, the real question around Almonty Industries is simple. Is most of the tungsten rerating already in the price, or is the valuation still catching up to the new offtake reality?
Preferred P/E of 52.1x: Is it justified?
On the numbers provided, Almonty Industries trades on a P/E of 52.1x, which is high compared with both its peers and the broader US Metals and Mining industry, even though the SWS DCF model points to a fair value of $41.23 versus the last close at $13.72.
The P/E ratio compares the current share price with earnings per share and effectively shows how much investors are paying for each dollar of profit. For a miner like Almonty Industries, a richer multiple can reflect expectations around future tungsten offtake, revenue expansion, and margin improvement rather than just the current income statement.
Against that backdrop, the current 52.1x P/E looks expensive relative to the US Metals and Mining industry average of 20.9x and a peer average of 25.9x. It is also well above the estimated fair P/E of 36.3x. This suggests a level the market could move toward if expectations cool or if earnings do not track the more optimistic forecasts.
Explore the SWS fair ratio for Almonty Industries.
Result: Price-to-earnings of 52.1x (OVERVALUED)
Still, the tungsten story around Almonty Industries can be knocked off course if new offtake deals slow or if project ramp ups face delays.
Find out about the key risks to this Almonty Industries narrative.
Another View: What Almonty Industries' Cash Flows Are Saying
The earnings multiple presents Almonty Industries as expensive, yet the SWS DCF model points the other way. At a share price of $13.72 versus an estimated future cash flow value of $41.23, that framework suggests the tungsten miner is trading at a heavy discount. Which signal should matter more if earnings are still settling after a recent move into profitability?
Look into how the SWS DCF model arrives at its fair value.
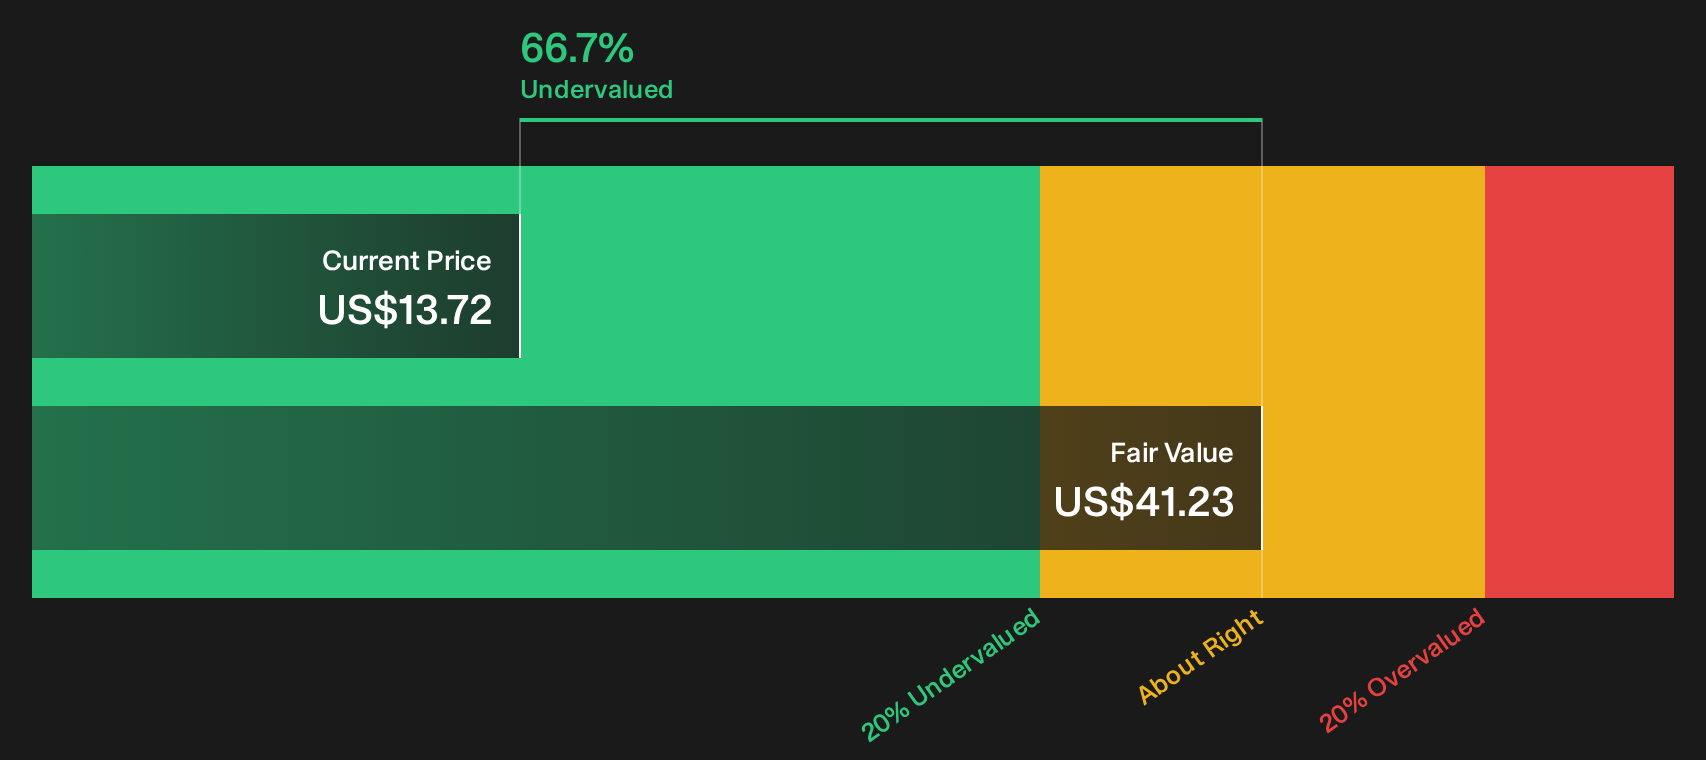
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Almonty Industries for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Almonty Industries so far? If you want to move quickly and build your own stance, start with the 3 key rewards and 4 important warning signs.
Looking for more investment ideas beyond Almonty Industries?
If Almonty Industries has sharpened your focus on opportunities, do not stop here. Use the Simply Wall Street screener to spot fresh ideas that fit your style.
- Target potential value plays by lining up companies that pass strict quality and valuation filters through the 32 high quality undervalued stocks.
- Prioritise resilience by sorting for businesses that show a robust capital structure and strong fundamentals using the list of solid balance sheet and fundamentals (24 results).
- Hunt for under-the-radar opportunities by scanning a curated pool of strong fundamentals with the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com