
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Cleveland-Cliffs (CLF) Just Moved, So What Is Drawing Attention Now?
Freedom Broker’s fresh buy call on Cleveland-Cliffs (CLF) hinges on a sharp rebound in third quarter adjusted EBITDA to about US$575 million, alongside tighter U.S. steel imports that have supported domestic pricing.
Cleveland-Cliffs’ latest share price of US$12.18 comes after a 90-day share price return of 29.85%. However, the year-to-date share price return is down 10.44% and the 5-year total shareholder return has declined 38.05%, suggesting short-term momentum is building while longer-term holders have seen weaker outcomes.
Compare Cleveland-Cliffs’ momentum with other potential rebound stories by scanning our hand-picked list of 32 high quality undervalued stocks that currently screen well on quality and valuation.
The rebound in Cleveland-Cliffs is sharp, yet the share price still trades at a reported 56% discount to one intrinsic value estimate. Has most of the easy upside already played out, or is that gap still meaningful?
Most Popular Narrative: 1% Overvalued
The most followed narrative pegs Cleveland-Cliffs’ fair value at $12.00, just below the recent $12.18 close, which frames this latest rally as only slightly ahead of that long term view.
New investments in higher-margin stainless and specialty steels, supported by infrastructure investment, electrification, and clean-energy buildout, may expand Cleveland-Cliffs' addressable markets and may support lasting product mix improvement, potentially affecting revenue and average selling prices.
See why 60 investors see Cleveland-Cliffs as 1% overvalued.
Result: Fair Value of $12.00 (OVERVALUED)
Still, this Cleveland-Cliffs story leans heavily on ongoing U.S. steel tariffs and carries meaningful balance sheet risk if deleveraging or asset sales disappoint.
Find out about the key risks to this Cleveland-Cliffs narrative.
Another View On Cleveland-Cliffs Valuation
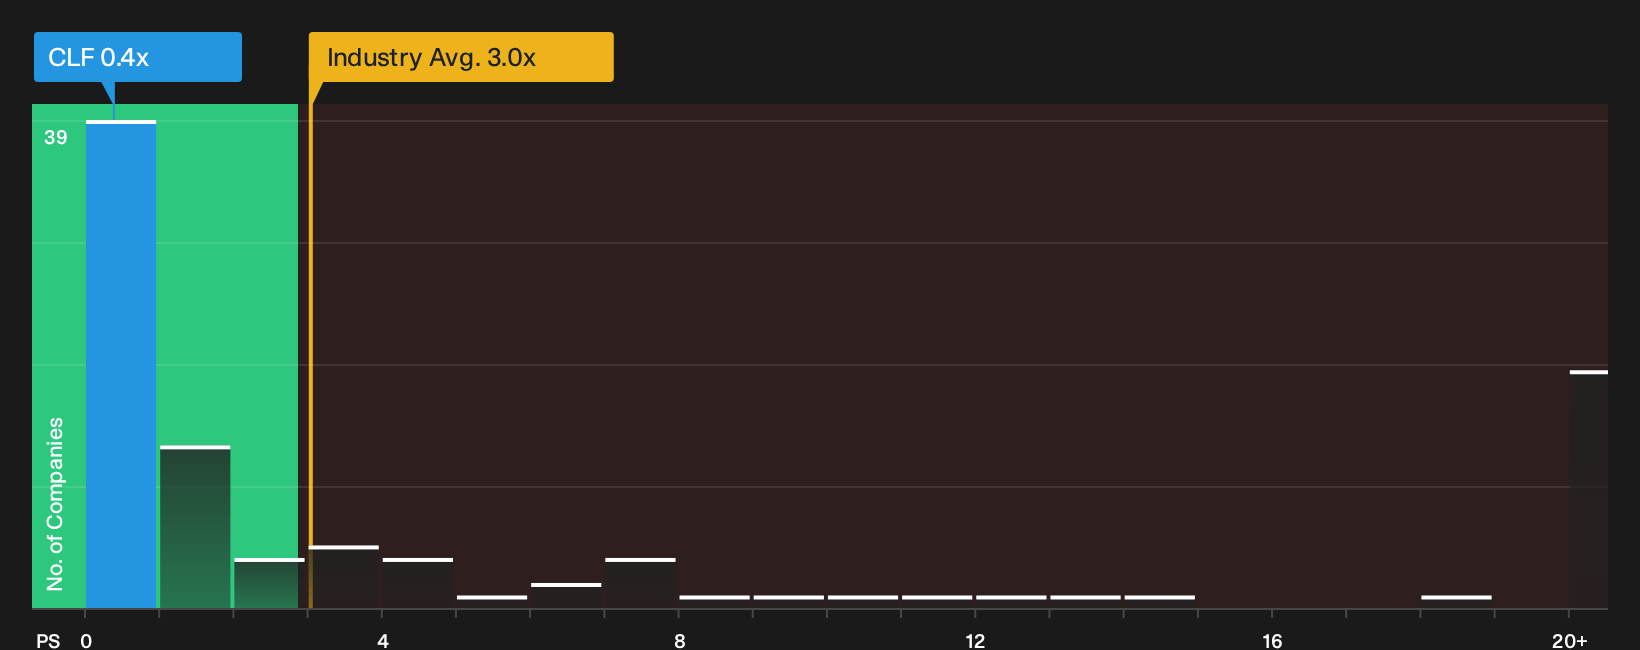
Cleveland-Cliffs looks very different when viewed through simple sales multiples. The stock trades on a P/S of 0.4x, while direct peers average 1.7x and the wider US Metals and Mining group sits near 3.0x. Our fair ratio of 0.8x still implies a large valuation gap. This may indicate a potential margin of safety or it may reflect concerns about earnings quality.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Cleveland-Cliffs so far. If you want your view to be grounded in more than headlines, review both the potential upside and the red flags in the 3 key rewards and 2 important warning signs.
Looking for more Cleveland-Cliffs style investment ideas?
If Cleveland-Cliffs has sharpened your focus on pricing power and valuation, keep that momentum going by scanning fresh opportunities with the Simply Wall Street Screener.
- Spot potential mispricing early by reviewing the 16 high quality undiscovered gems that combine strong fundamentals with relatively low market attention.
- Prioritise resilience by checking the 30 resilient stocks with low risk scores that score well on balance sheet strength and earnings stability.
- Target financial robustness by scanning the list of solid balance sheet and fundamentals (24 results) so you are not caught off guard when conditions turn tougher.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com