
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is AXIS Capital Holdings (AXS) Still A Bargain After A 132% Run?
AXIS Capital Holdings has delivered a powerful multi year share price run, and the recent pullback now raises a sharper question for investors around whether its current valuation is still supported by its earnings power.
- Over the past 5 years the stock has gained 132.1%, which puts real pressure on the earnings story to carry that higher market value.
- The business model relies heavily on underwriting discipline and investment income, so any shift in claim trends or portfolio yields can materially alter how comfortably its profits support the present share price.
- There is a second opinion on AXIS Capital Holdings worth weighing. See what analysts think AXIS Capital Holdings's shares could be worth.
The stock's next move may depend on whether AXIS Capital Holdings' current earnings profile is strong enough to justify where the shares trade today.
If you want to stress test this same earnings driven valuation question beyond AXIS Capital Holdings, compare it with 32 high quality undervalued stocks.
Is AXIS Capital Holdings Still Cheap on Earnings?
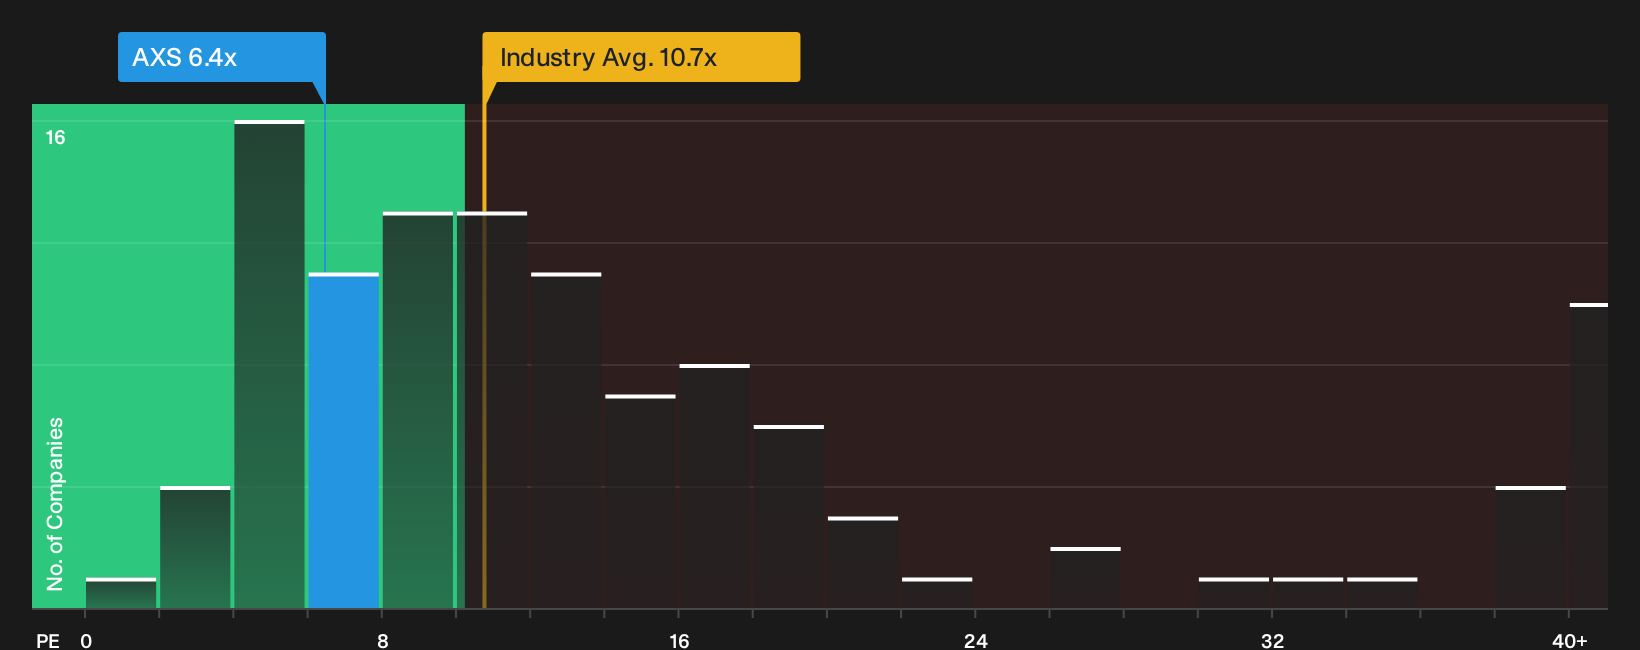
The P/E ratio is usually the cleanest way to think about what you are paying for each dollar of AXIS Capital Holdings earnings. Right now the stock trades on a P/E of about 6.4x, which is below both the wider insurance industry average of roughly 10.7x and the peer group near 9.7x.
The fair value model that blends AXIS Capital Holdings expected growth, profitability profile and risk suggests a higher P/E would be justified. The current 6.4x therefore points to the shares being undervalued on this yardstick. For you as an investor, that gap means the market is pricing AXIS earnings at a lower level than similar insurers, and lower than the tailored fair multiple implied by the company specific fundamentals. Explore the numbers behind AXIS Capital Holdings's P/E valuation.
The AXIS Capital Holdings Narrative: What Would Justify Today's Price?
Narratives on Simply Wall St pick up where the AXIS Capital Holdings' P/E puzzle leaves off, by explaining which potential paths for growth, margins and earnings would need to occur for the stock to be worth meaningfully more or less than it is today. Each narrative treats fair value as a thesis about the business that you can observe over time rather than a single frozen snapshot. These narratives sit on AXIS Capital Holdings' Community page and give you a structured way to think about what the current price is really asking you to believe.
One of the top community narratives on AXIS Capital Holdings: 23% undervalued
"The main thing that has to go right is that AXIS Capital Holdings continues to grow fee income and capital light capacity solutions…"
Discover why this Narrative puts AXIS Capital Holdings at 23% undervalued.
One more crucial piece for AXIS Capital Holdings that the valuation alone will not answer
Price and earnings tell only part of the story for AXIS Capital Holdings, because the people setting priorities and how they are rewarded can tilt outcomes in very different directions. See who runs AXIS Capital Holdings and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com