
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Comstock Resources (CRK) Faces Fresh Jefferies Risk Focus, Is It Still Below Fair Value?
Jefferies coverage sparks fresh focus on risk at Comstock Resources
Comstock Resources (CRK) came under pressure after Jefferies began coverage, spotlighting the producer’s sensitivity to front month natural gas prices and elevated debt, which shaped the latest shift in investor sentiment.
The Jefferies call landed on a stock that was already under pressure, with the share price down 44.36% year to date and 8.19% over the past month, even as the 5 year total shareholder return of 32.57% shows a very different long haul story.
This week’s 5.07% one day share price drop came on the heels of that new coverage, reinforcing concerns about natural gas exposure and leverage. At the same time, the 20.44% total shareholder return over three years hints at investors still weighing past gains against a reset in risk perception.
Scan beyond Comstock Resources and stress test your own risk tolerance against a hand picked 30 resilient stocks with low risk scores intended to help keep volatility in check.
With Comstock Resources changing hands at US$13.12 and sitting roughly 23% below the average analyst target but far above some intrinsic value estimates, which reference point looks closer to fair value after this latest drop?
Most Popular Narrative: 19% Undervalued
Comstock Resources last traded at $13.12, while the most followed narrative points to a fair value of about $16.27 using a 7.24% discount rate. That gap puts the focus squarely on whether the Western Haynesville story and balance sheet moves are strong enough to justify the implied upside.
The company's proactive development of Western Haynesville specific midstream infrastructure (such as a major new gas treating plant) will allow for higher production levels, improved price realizations, and increased ability to capitalize on expanding U.S. LNG export capacity, thereby supporting revenue growth.
See why 7 investors see Comstock Resources as 19% undervalued.
Result: Fair Value of $16.27 (UNDERVALUED)
Still, the Comstock Resources story can change quickly if Haynesville focused production remains concentrated and higher leverage meets weaker cash generation or rising development costs.
Find out about the key risks to this Comstock Resources narrative.
Another View on Comstock Resources valuation
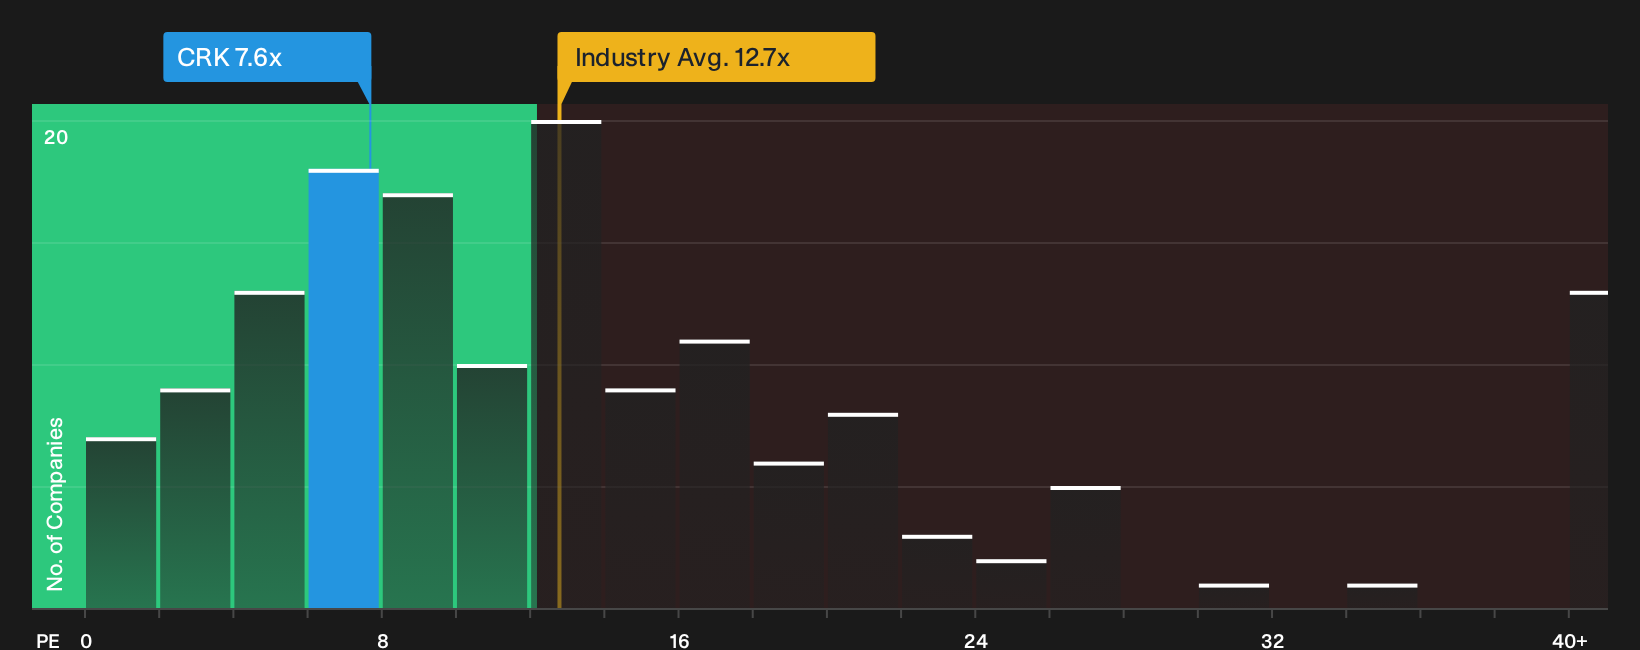
The first lens points to Comstock Resources trading below a roughly $16.27 fair value. A different yardstick tells a less generous story. On a P/E of 7.6x, the stock looks cheaper than the US Oil and Gas average on 12.7x and slightly below peers on 8x, yet still a bit above its own fair ratio of 7.1x.
That mix of apparent discount versus the sector, but a small premium to the fair ratio, hints at limited margin for error rather than a clear giveaway. If earnings fall in line with forecasts, this gap may represent value or it may simply be compensation for the risk investors are being asked to take.
See what the numbers say about this price — find out in our valuation breakdown.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Comstock Resources for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Comstock Resources valuation and risk are clear enough. What counts now is your read on that trade off. To weigh both sides on your terms, start with a quick look at the 3 key rewards and 3 important warning signs.
Looking for more Comstock Resources sized investment ideas?
If Comstock Resources has you reassessing risk and reward, do not stop here. Broaden your watchlist now or you risk missing fresher opportunities elsewhere.
- Target resilient balance sheets and stronger fundamentals by scanning a curated list of solid balance sheet and fundamentals (24 results) that can help steady a portfolio when conditions get bumpy.
- Hunt for mispriced opportunities using a focused 32 high quality undervalued stocks that surfaces companies where current prices sit well below underlying fundamentals.
- Stack potential income streams by reviewing a hand picked 8 dividend fortresses that highlights higher yielding payers with an emphasis on staying power.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com