
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Royal Bank Of Canada (TSX:RY) Could Be 4% Undervalued As Earnings Views Improve
Royal Bank of Canada (TSX:RY) is back in focus after analysts lifted full year earnings expectations in recent months. The shift in sentiment comes as the bank continues to be viewed favorably versus financial sector peers.
Recent activity around Royal Bank of Canada’s funding stack has been busy, with multiple new fixed income offerings and NVCC instruments coming to market. Yet the share price has been relatively steady, with a year to date share price return of 21.77% and a 1 year total shareholder return of 44.16%, pointing to momentum that has been building over a longer horizon.
Scan how Royal Bank of Canada’s momentum compares with other high quality financials by checking our hand picked list of solid balance sheet and fundamentals (7 results).
Royal Bank of Canada’s share price has run hard, yet it still trades below both analyst targets and some intrinsic value estimates. Is that gap a genuine margin of safety or a signal that expectations are stretched?
Most Popular Narrative: 4% Undervalued
Royal Bank of Canada last closed at CA$285.63, while the most followed narrative framework points to a fair value of CA$298.79 using a 7.2% discount rate. That gap sets the stage for a debate about whether today’s price fully reflects the bank’s long term earnings and capital return plans.
Strategic investments in AI and digitalization, such as the ATOM Foundation and Lumina platform, expanded use of data analytics, and digital banking product launches, are associated with cost efficiencies, deeper customer engagement, and higher transaction volumes.
Growing demand for wealth management and retirement solutions, evidenced by double-digit growth in assets under administration across Canadian and U.S. Wealth Management, is associated with global wealth accumulation and the aging population, and with long-term, higher-margin, recurring fee income streams and AUM growth.
See why 163 investors see Royal Bank of Canada as 4% undervalued.
Result: Fair Value of CA$298.79 (UNDERVALUED)
Still, Royal Bank of Canada’s exposure to Canadian real estate, along with the prospect of higher provisions for credit losses, could quickly challenge the current undervaluation story.
Find out about the key risks to this Royal Bank of Canada narrative.
Another View on Royal Bank of Canada’s Valuation
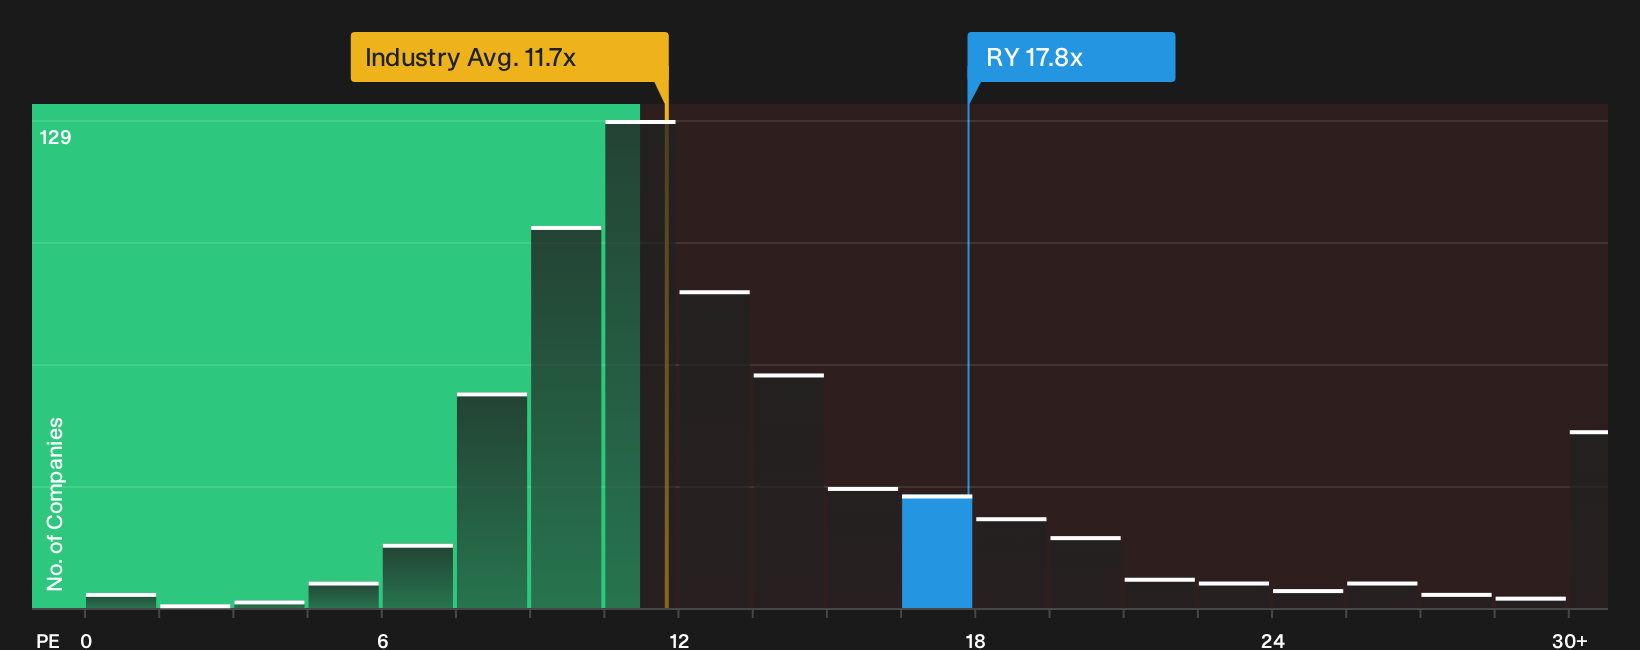
While the SWS DCF model points to undervaluation, the market’s pricing on earnings sends a different message. Royal Bank of Canada trades on a P/E of 17.8x versus a peer average of 17.4x and a fair ratio of 17.7x, which signals only a slim margin for error. If sentiment changes, does that tiny gap turn into valuation risk faster than investors expect?
See what the numbers say about this price by reviewing our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Royal Bank of Canada story so far. Act quickly, review the data on both the downside and the upside, then weigh the 4 key rewards and 1 important warning sign.
Looking for more Royal Bank of Canada style investment ideas?
If you want a wider view than Royal Bank of Canada alone, use focused stock lists to spot opportunities before they move and avoid getting stuck with laggards.
- Target potential future compounders by scanning a curated pool of financially strong stocks through the 9 high quality undiscovered gems.
- Prioritize resilience and sleep easier at night by focusing on companies that pass strict stability checks using the 8 resilient stocks with low risk scores.
- Build a cash flow focused portfolio by concentrating on income names that meet a tough yield and quality bar with the 1 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com