
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
CarMax Stock And 2 Auto Dealer Picks With Stronger Balance Sheets
America’s Car-Mart put used-car retailers in the spotlight after its covenant troubles and bankruptcy warning shook confidence in the sector. Stress at CRMT can create mispricing elsewhere, as investors often react first and ask questions later. This piece looks at three financially stronger U.S. auto dealer stocks exposed to the same news, helping you spot where fear may be overdone and where caution could still be wise.
The stocks highlighted below are just a first pass, and the full screen surfaced 11 more U.S. used-car retailers and auto dealers with equally compelling financial stories that are not covered in this article. To identify and analyze the highest conviction ideas with solid balance sheets and healthier risk profiles, head straight into the Financially Strong U.S. Used-Car Retailers and Auto Dealers screener.
Lithia Motors (LAD)
Overview: Lithia Motors is a large auto retailer selling new and used vehicles and related services through dealerships and digital platforms across North America and the UK.
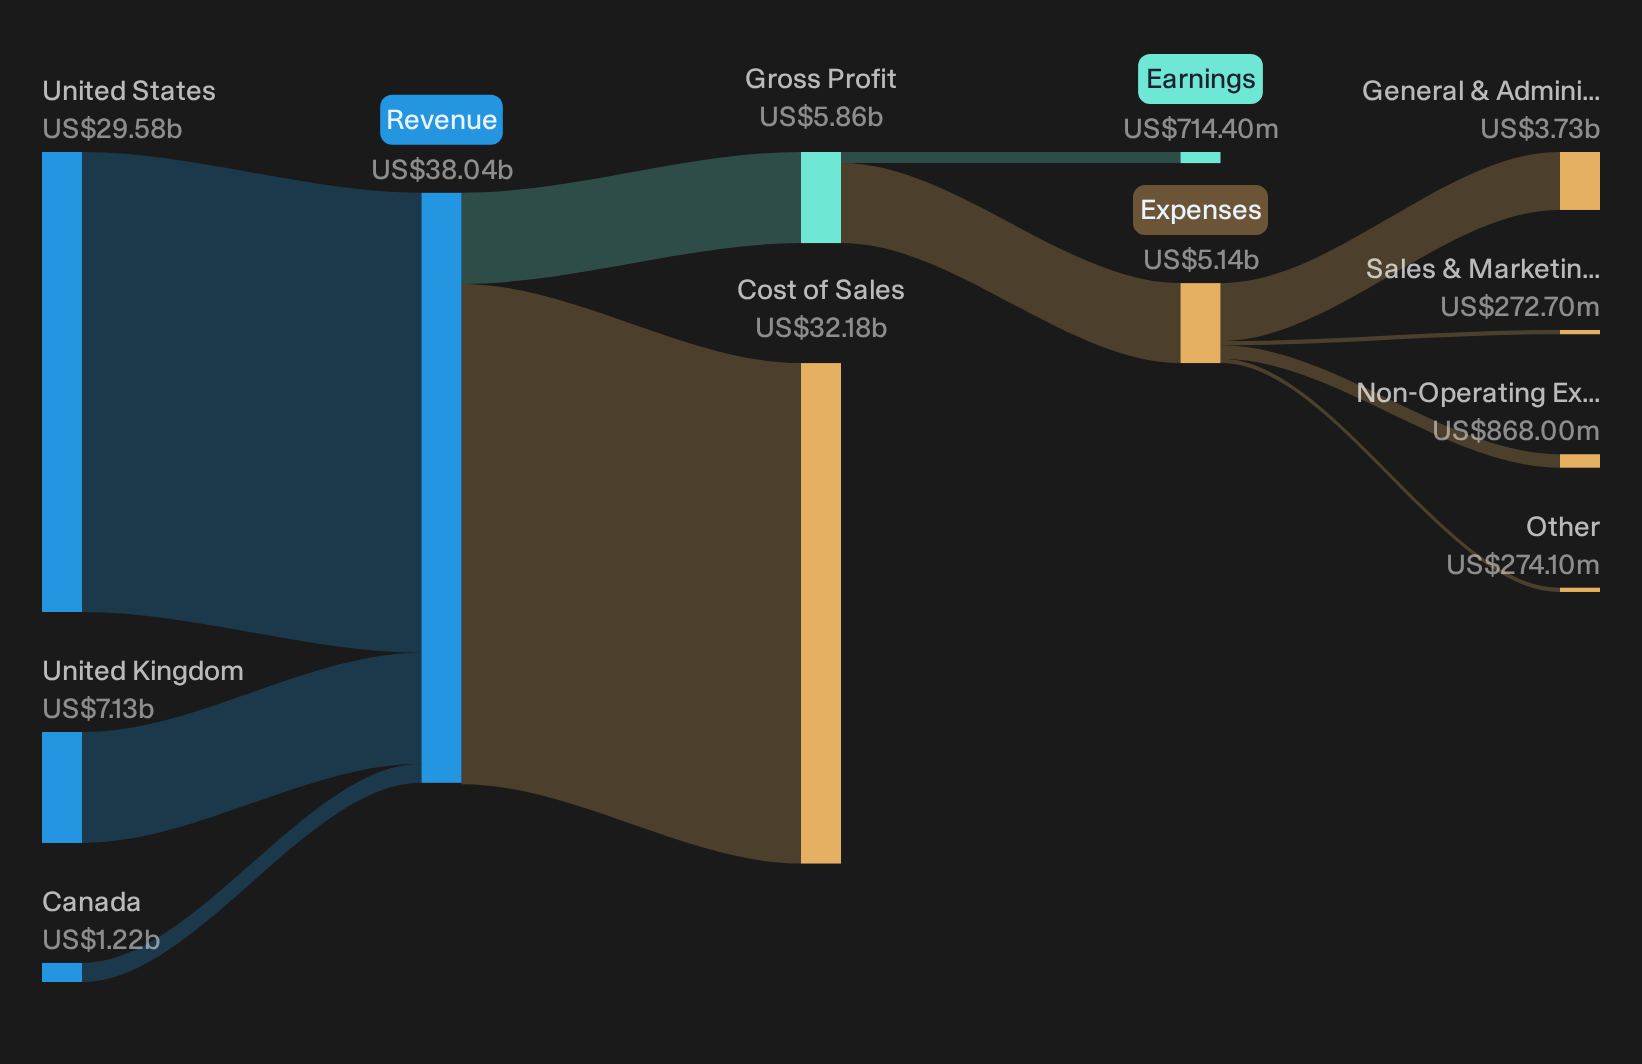
Operations: Lithia Motors generates about US$37.9b from vehicle operations, with US$29.6b in the United States, US$7.1b in the United Kingdom, and US$1.2b in Canada.
Market Cap: US$7.0b
For investors screening for financially stronger used-car retailers, Lithia Motors offers scale, a broad footprint, and a business model built around multiple profit streams beyond just selling cars.
"Sustained strength and growth in aftersales (service, parts, warranty) driven by the aging U.S. vehicle fleet and longer replacement cycles is boosting high-margin, recurring revenue streams. Over 60% of Lithia's net profit now comes from aftersales, providing stability and earnings growth not reflected in current valuations."
The real tension for Lithia Motors now is what happens to those carefully managed costs if a single key efficiency assumption breaks.
If that key assumption starts to wobble, the full narrative for Lithia Motors explains how Lithia Motors’ multi-revenue engine could absorb shocks, undergo a re-rating, or stall altogether.
CarMax (KMX)
Overview: CarMax is a large, pure-play U.S. used-vehicle retailer with nationwide stores and in-house financing, focused on used-car sales and related services.
Operations: CarMax generates about US$28.2b in revenue, with roughly US$26.3b from CarMax Sales Operations and US$1.8b from CarMax Auto Finance, all in the United States.
Market Cap: US$8.1b
CarMax matters for this screener because it is one of the few pure used-car specialists with national reach and its own finance arm. This structure gives it tools that many smaller rivals under credit stress simply do not have.
"Continued investment in digital capabilities and omnichannel retailing, including AI-powered virtual assistants, streamlined online appraisal and financing tools, and a growing mix of digitally supported sales, is expected to drive higher conversion rates and lower customer acquisition costs, resulting in sustained retail sales growth and expanding net margins over the long term."
What happens to CarMax’s earnings power now largely depends on how one quiet pressure on its funding and credit costs plays out.
That quiet funding pressure is exactly what the full narrative for CarMax unpacks, showing where credit costs could be masking an accelerating opportunity for CarMax.

Asbury Automotive Group (ABG)
Overview: Asbury Automotive Group runs a large U.S. dealership network focused on selling new and used vehicles and providing repair, parts, collision, and finance and insurance services, positioning it to benefit when weaker used-car retailers struggle for funding.
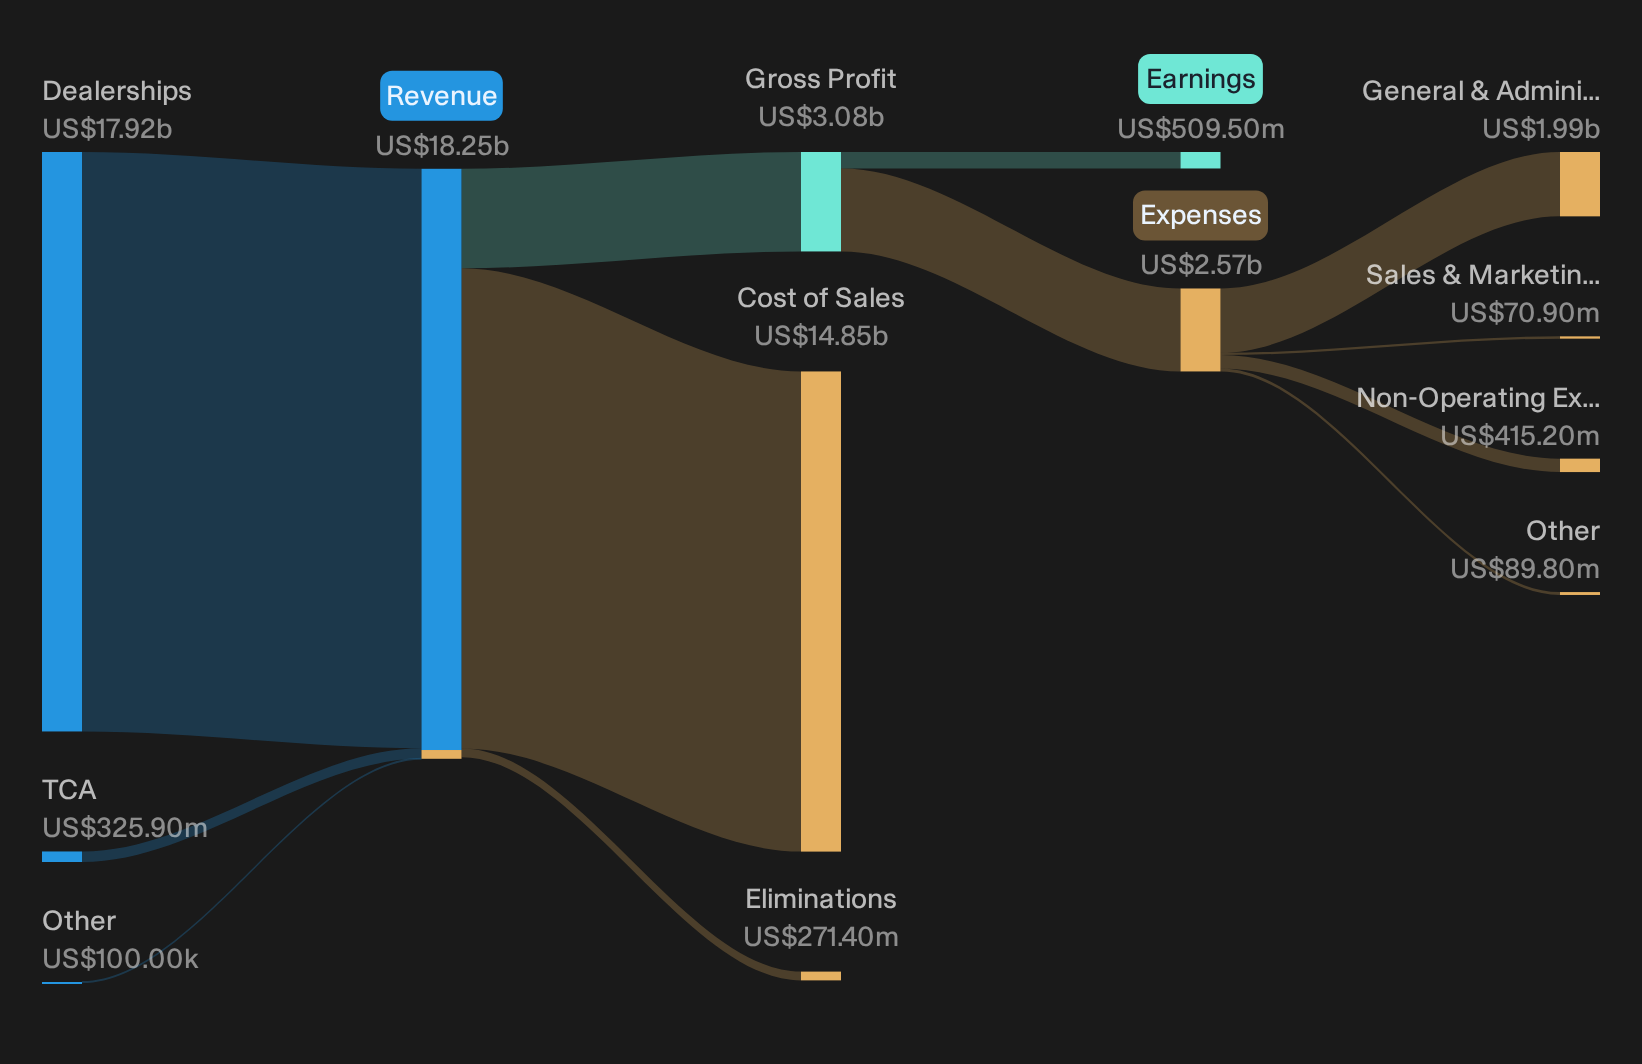
Operations: Asbury Automotive Group generates about US$18.2b from Dealerships and US$325.9 million from TCA in the United States, with eliminations of US$271.4 million.
Market Cap: US$3.3b
Asbury Automotive Group fits this financially stronger dealer screen because it couples a broad used-vehicle footprint with a deeper services and financing ecosystem that smaller, stressed rivals often lack.
"Higher dollars per repair order on battery electric vehicles, currently about US$350 or more above internal combustion work with similar margins, create room for Asbury Automotive Group to grow fixed operations revenue and support gross margin mix as EV penetration increases in the service bay."
What happens if one key assumption about how quickly those higher value service bays fill up proves either too cautious or too optimistic?
That timing risk is exactly what the full narrative for Asbury Automotive Group pulls apart, revealing how Asbury Automotive Group could see earnings power accelerate or stall as service demand decouples from sales volumes.
Seeking Alternatives Before The Crowd Does
Fresh ideas move first. By the time a breakout gains momentum, the best entry points can be gone. Scan under the radar for now and act now.
- Spot potential rebound plays and faster movers by running the curated 32 high quality undervalued stocks while prices and expectations still feel caught napping.
- Surf where capital is already flying by lining up 85 AI infrastructure stocks that may benefit from accelerating demand for the picks and shovels of AI.
- Target cash-generating miners before the crowd re-prices risk by screening through 36 elite gold producer stocks while sentiment around precious metals keeps shifting.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com