
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Ciena (CIEN) Undervalued On Its AI Driven Analyst Upgrade?
Ciena (CIEN) is back in focus after a Special Call on 16 September 2026 and a fresh analyst upgrade linked to rising demand for optical systems serving artificial intelligence data traffic.
Ciena’s latest analyst upgrade comes after a sharp pullback, with the share price down about 25% over 90 days and 6% over 30 days. The shares are still up 45% year to date and supported by a very large 1 year total shareholder return of 151%, which extends to more than 7x over 3 years.
Scan for more AI infrastructure opportunities by sizing up the curated 85 AI infrastructure stocks that could be riding the same data traffic tailwinds as Ciena.
Bulls point to Ciena’s AI tailwind, earnings momentum, and pullback as a rare reset. Bears see a hot 1 year run and rich expectations. Which story do the current valuation markers actually support?
Most Popular Narrative: 35% Undervalued
Ciena closed at $356.91, while the most followed narrative pegs fair value at $551.86. This frames the recent pullback against a still-optimistic long term story built around AI networking demand and margin expansion.
Major cloud providers and a new wave of neo-scalers are aggressively investing in high-capacity, low-latency optical networking infrastructure to support AI workloads, driving multiyear, global network buildouts that should significantly expand Ciena's addressable market and underpin sustained, above-trend revenue growth.
Ciena's industry-leading solutions (WaveLogic 6, RLS platform, pluggables, DCOM) are rapidly becoming de facto standards for AI network infrastructure, resulting in sizable multi-hundred-million-dollar orders, a record order book, and strong visibility into 2026 growth-suggesting consensus revenue estimates may be too conservative.
See why 48 investors see Ciena as 35% undervalued.
Result: Fair Value of $551.86 (UNDERVALUED)
Still, if hyperscaler clients pull back orders or new open networking approaches gain traction faster than expected, Ciena’s premium AI narrative could face real pressure.
Find out about the key risks to this Ciena narrative.
Another View: Ciena Looks Expensive On P/E
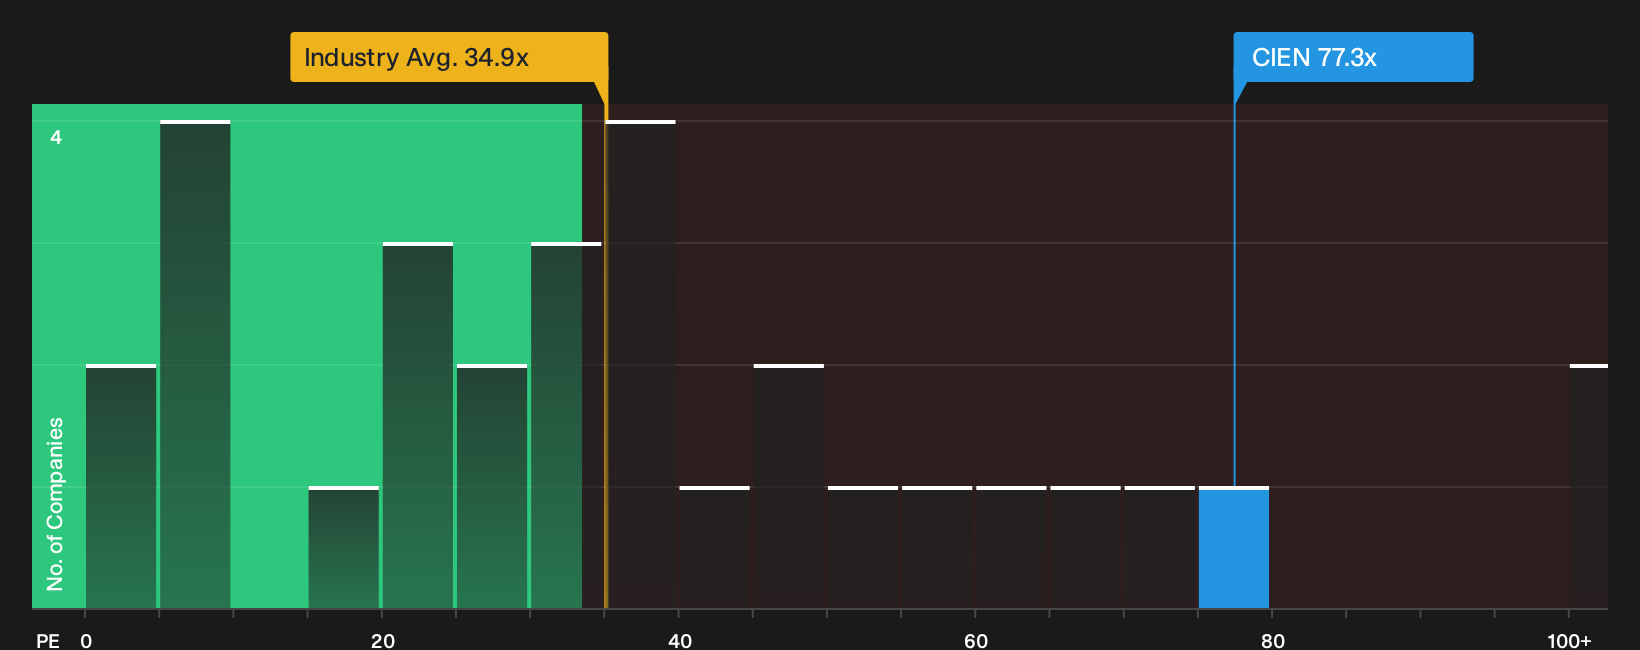
The fair value model paints Ciena as 34.3% undervalued, yet the P/E story adds friction. The stock trades on 77.3x earnings compared with a fair ratio of 52.4x, the US Communications sector on 34.9x, and peers around 42.4x. That is a rich premium. Are investors paying too far ahead of the AI narrative?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Ciena is split, with optimism around AI demand and concern around valuation and execution risk sitting side by side. Act quickly, review the underlying numbers for yourself, and weigh both the potential upside and the downside flagged in our breakdown of 3 key rewards and 2 important warning signs
Looking for more Ciena-like investment ideas?
If you only stop at Ciena, you risk missing other opportunities that match your style, your risk limits, and the kind of returns you want to target.
- Target higher potential payoff by reviewing a carefully filtered group of 8 elite penny stocks with strong financials that pair tiny market values with stronger financial underpinnings.
- Sharpen your value hunt and scan a curated 32 high quality undervalued stocks that already screens for quality balance sheets and solid cash generation.
- Prioritise resilience first and sift through a focused 30 resilient stocks with low risk scores designed for investors who want steadier profiles and fewer negative surprises.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com