
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Bastogi (BIT:B) Stock Confronts Core Losses Behind Disposal Fueled Profit
Bastogi stock came into the H1 print with a quiet tailwind, up about 23% over three months and closing at €1.21 on Friday. The headline number that really jars short term optimism is the swing from profit to a net loss of €4.955 million from ongoing operations, even as earnings from discontinued businesses injected a hefty €76.844 million. For anyone thinking beyond this week’s chart, the bigger story is the tension between that one off boost and the longer term earnings power that will need to carry Bastogi once those disposals are in the rear-view mirror.
Is Bastogi trading at a genuine 44.7% discount, or does the recent swing to a €4.955 million loss tell a different story about what the shares are really worth? Compare that one off disposal boost with ongoing earnings power inside the full valuation analysis for Bastogi
H1 2026 Earnings Summary
- Revenue (H1 2026 vs. H1 2025): €16.466 million vs. €34.006 million (top line roughly halved year on year).
- Net Income/Loss, Excluding Extra Items (H1 2026 vs. H1 2025): loss of €4.955 million vs. profit of €4.605 million (shift from profit to loss).
- Basic EPS (H1 2026 vs. H1 2025): not disclosed for H1 2026 vs. €0.041375 per share (prior period reference only, current half not stated).
- Earnings from Discontinued Operations (H1 2026 vs. H1 2025): €76.844 million vs. not reported (current period significantly influenced by disposal-related gains).
Tired of scrolling through long lists of figures trying to piece together what Bastogi looks like today?
See a clear visual snapshot of Bastogi, including how the current valuation compares with its recent earnings profile, inside the full company report for Bastogi.
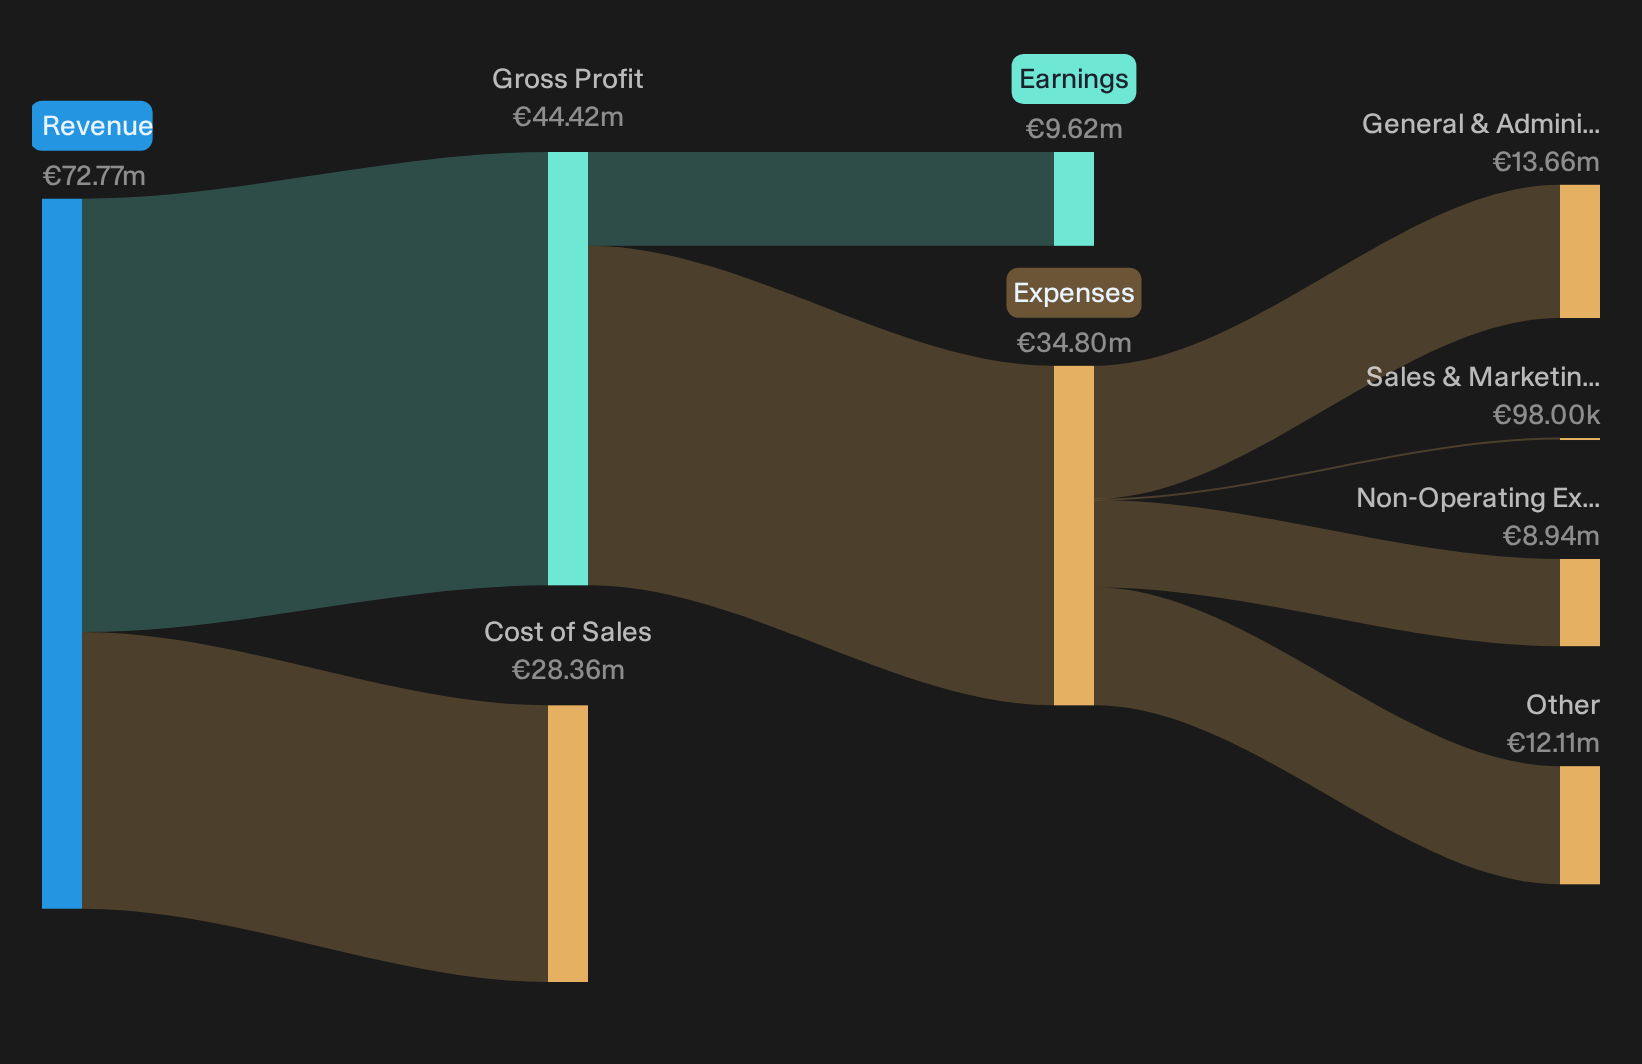
Bastogi’s Asset Story Meets Earnings Reality
Bastogi is often pitched as an asset backed cultural and real estate platform. The current figures make that story more complicated. Revenue moved from €34.006 million to €16.466 million and the ongoing business shifted from a €4.605 million profit to a €4.955 million loss. The €76.844 million gain from discontinued operations supports the balance sheet optics today, yet it also underlines how dependent the first half result is on disposals rather than recurring activity in venues, hospitality and services.
Complex Conglomerate Risks Brought Into Sharper Focus
The cautious view on Bastogi as a complex group finds support in these numbers. Core operations moved into a €4.955 million loss while headline earnings rely on discontinued activities worth €76.844 million. That split between ongoing and exited businesses points to execution risk across the remaining portfolio. With revenue at €16.466 million versus €34.006 million in the prior period comparison, the breadth of segments does not currently translate into resilient earnings power, which keeps conglomerate and transparency concerns in play.
With earnings relying on disposals and core operations posting a €4.955 million loss, the key question is whether Bastogi’s balance sheet can comfortably absorb future shocks. Check the full financial health analysis of Bastogi stockBuild Your Edge With Simply Wall St
If Bastogi’s mix of disposal gains and a €4.955 million operating loss has you watching for a clearer entry point, register for free with Simply Wall St and add it to your Watchlist to track share price moves against fair value estimates. When you do decide to take a position, use the Portfolio Command Center to cut through noise and stay on top of the most important updates for your holdings. For longer term decisions, tap into the Community to see how other investors are thinking about the same risks and potential catalysts. That way you spot emerging issues and opportunities early and keep a step ahead of the wider market.
Seeking Alternatives Beyond Bastogi?
Fresh ideas often move first. By the time momentum is obvious on the chart, early entry points can be gone. Scan these focused lists while it still matters and consider opportunities earlier in their move.
- Spot potential breakout compounding stories before the crowd by sweeping through 618 high quality undiscovered gems that have been filtered for strong underlying fundamentals and cleaner balance sheets.
- Track where cash flow strength meets balance sheet resilience by reviewing the curated list of solid balance sheet and fundamentals stocks (201 results) and see which businesses still look prepared for shocks.
- Zero in on income ideas with staying power by scanning the hand picked 160 dividend fortresses that focus on higher yields supported by underlying fundamentals rather than hype.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com