
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How New TREMFYA Data At Johnson & Johnson Stock Has Changed Its Investment Story
- Johnson & Johnson reported past clinical milestones for TREMFYA in axial psoriatic arthritis and long-term CARTITUDE-2 data for CARVYKTI in early line multiple myeloma, reinforcing product strength in immunology and oncology.
- These readouts support Johnson & Johnson's effort to offset pressure from loss of exclusivity and litigation by leaning on higher value specialty medicines.
- We will now look at how Johnson & Johnson's investment narrative could shift, given TREMFYA's axial PsA data as a fresh catalyst.
Johnson & Johnson Investment Narrative Recap
To stay invested in Johnson & Johnson, you need to believe the core thesis still rests on its ability to replace pressure from STELARA’s loss of exclusivity and ongoing litigation with growth from immunology, oncology and MedTech. The fresh TREMFYA axial PsA data and CARVYKTI results feed that story but do not change the basic equation.
In the very near term, the key swing factor is how quickly newer therapies can contribute enough to keep earnings resilient while tariffs, talc cases and orthopedic headwinds sit in the background. The recent readouts help sentiment on the pipeline and durability of the oncology portfolio, but they do not remove those risks.
The TREMFYA Phase 4 STAR result looks most connected to the current immunology narrative. Meeting primary and major secondary endpoints in biologic naive axial PsA, with MRI confirmed inflammation and no new safety signals, supports Johnson & Johnson’s effort to lean on higher value specialty medicines as older drugs face competition.
That said, the main operational questions remain execution and breadth. Management still needs multiple products like TREMFYA, CARVYKTI, TECVAYLI plus DARZALEX FASPRO and future CAPLYTA indications to collectively offset revenue pressure from STELARA biosimilars and any tariff or litigation impact. For investors, the focus stays on how consistently these newer assets translate into stable cash flow.
Johnson & Johnson's current analyst narrative points to revenues of $120.5b and earnings of $28.6b by 2029. That profile assumes revenue expands at about 7.2% a year and earnings rise by $7.6b from $21.0b today to the 2029 consensus level.
Uncover why Johnson & Johnson's fair value is consistent with its current price.
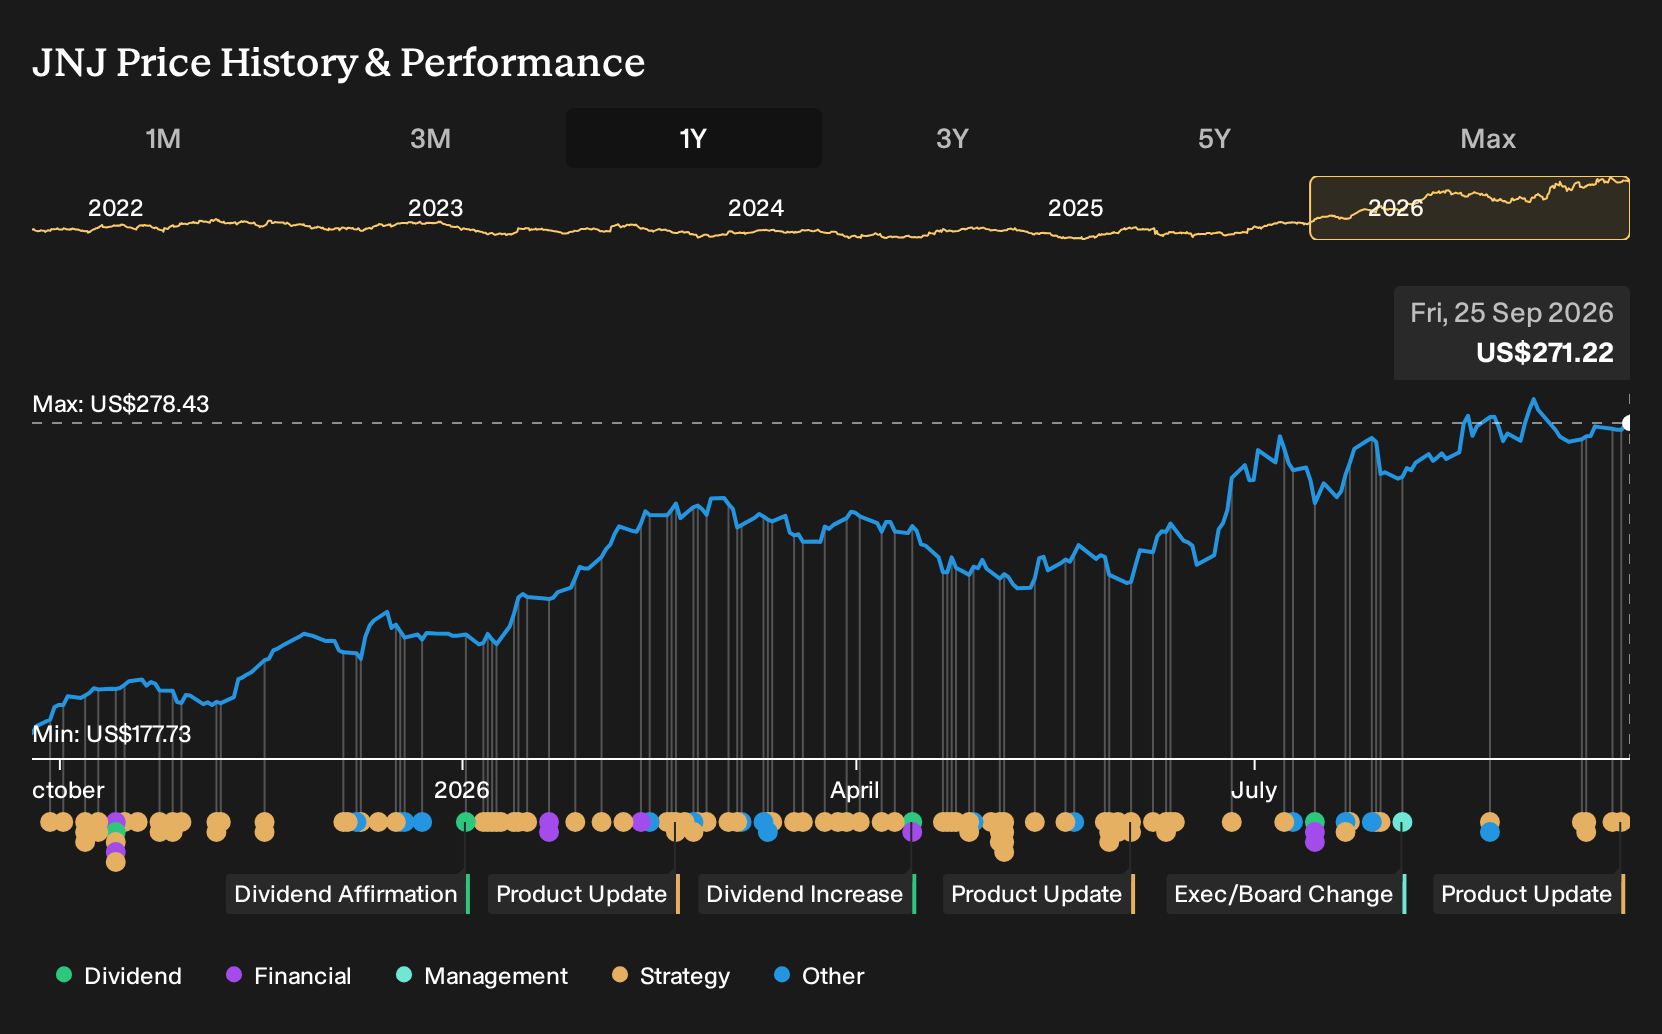
Exploring Other Perspectives
One alternate storyline around Johnson & Johnson leans hard into CAPLYTA as a swing factor. The most optimistic analysts were already modeling earnings of about $39.2b on revenue of roughly $125.9b by 2029, compared with the baseline view of $28.6b on $120.5b. Those targets came before the TREMFYA STAR data, so opinions may evolve as you weigh both narratives.
Explore 8 other Johnson & Johnson fair value estimates, including one that suggests potential upside of as much as 34% from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Johnson & Johnson research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Johnson & Johnson. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Johnson & Johnson's overall financial health at a glance.
Looking for more Johnson & Johnson style investment ideas?
If the Johnson & Johnson story has you thinking about portfolio balance, cash generation and resilience, it can help to line it up against other businesses with similar strengths. The Simply Wall St screener lets you filter the market by quality, income or balance sheet strength so you can find stocks that fit the role you want them to play.
- For investors who want dependable income with less emphasis on short term price moves, review 8 dividend fortresses that may suit a long term, yield focused approach.
- If capital preservation and shock absorption matter most to you, start with the list of solid balance sheet and fundamentals (24 results) to see which businesses combine financial strength with durable fundamentals.
- When you want to go beyond the crowded large caps and hunt for lesser known opportunities with solid metrics, the 16 high quality undiscovered gems can surface ideas that are easier to overlook in headline-driven markets.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com