
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Founder Led Stocks With Up To 46% Revenue Growth
Foreign investors have poured a record US$942b into US equities over the past year, even as bond yields sit at two decade highs. Money is voting for businesses where leadership looks committed and predictable. That is where founder led firms can matter. When the person who created the company still calls the shots, incentives tend to be clearer. This article highlights three such stocks for investors to take a closer look at.
The three founder led stocks below are only a starting sample, drawn from a much larger universe where the same ownership mindset and long term commitment show up in very different business models, and the full screen surfaced 1,435 more companies with equally compelling narratives that are not covered here. To size up that broader field for yourself, head straight into the Founder-Led Companies screener to identify, filter and analyze the founder led plays that best match your own conviction and risk profile.
Cerebras Systems (CBRS)
Overview: Cerebras Systems builds wafer scale AI chips and rack systems that power large scale inference and generative AI workloads for global customers.
Operations: Cerebras Systems generates about US$680.7 million from semiconductors, with roughly US$236.6 million in the United States and US$443.5 million across Europe, the Middle East and Africa.
Market Cap: US$49.1b
Cerebras Systems matters for a founder led screen because Andrew Feldman and his co founders are tying their own reputations directly to an all in bet on wafer scale AI infrastructure, rather than a diversified holding structure.
"In late 2025, Cerebras signed a transformative Master Relationship Agreement with OpenAI; OpenAI is contractually bound to procure 750 megawatts of inference capacity through 2028, backed by a $1.0 billion working capital loan to fund Cerebras's manufacturing scale-up."
For shareholders, much now hinges on how one concentrated customer relationship ultimately shapes pricing power, future margins and the growth runway.
That kind of concentration risk can cut both ways, so it is worth reading the full narrative for Cerebras Systems to see how Cerebras Systems’ bet could accelerate or stall from here.

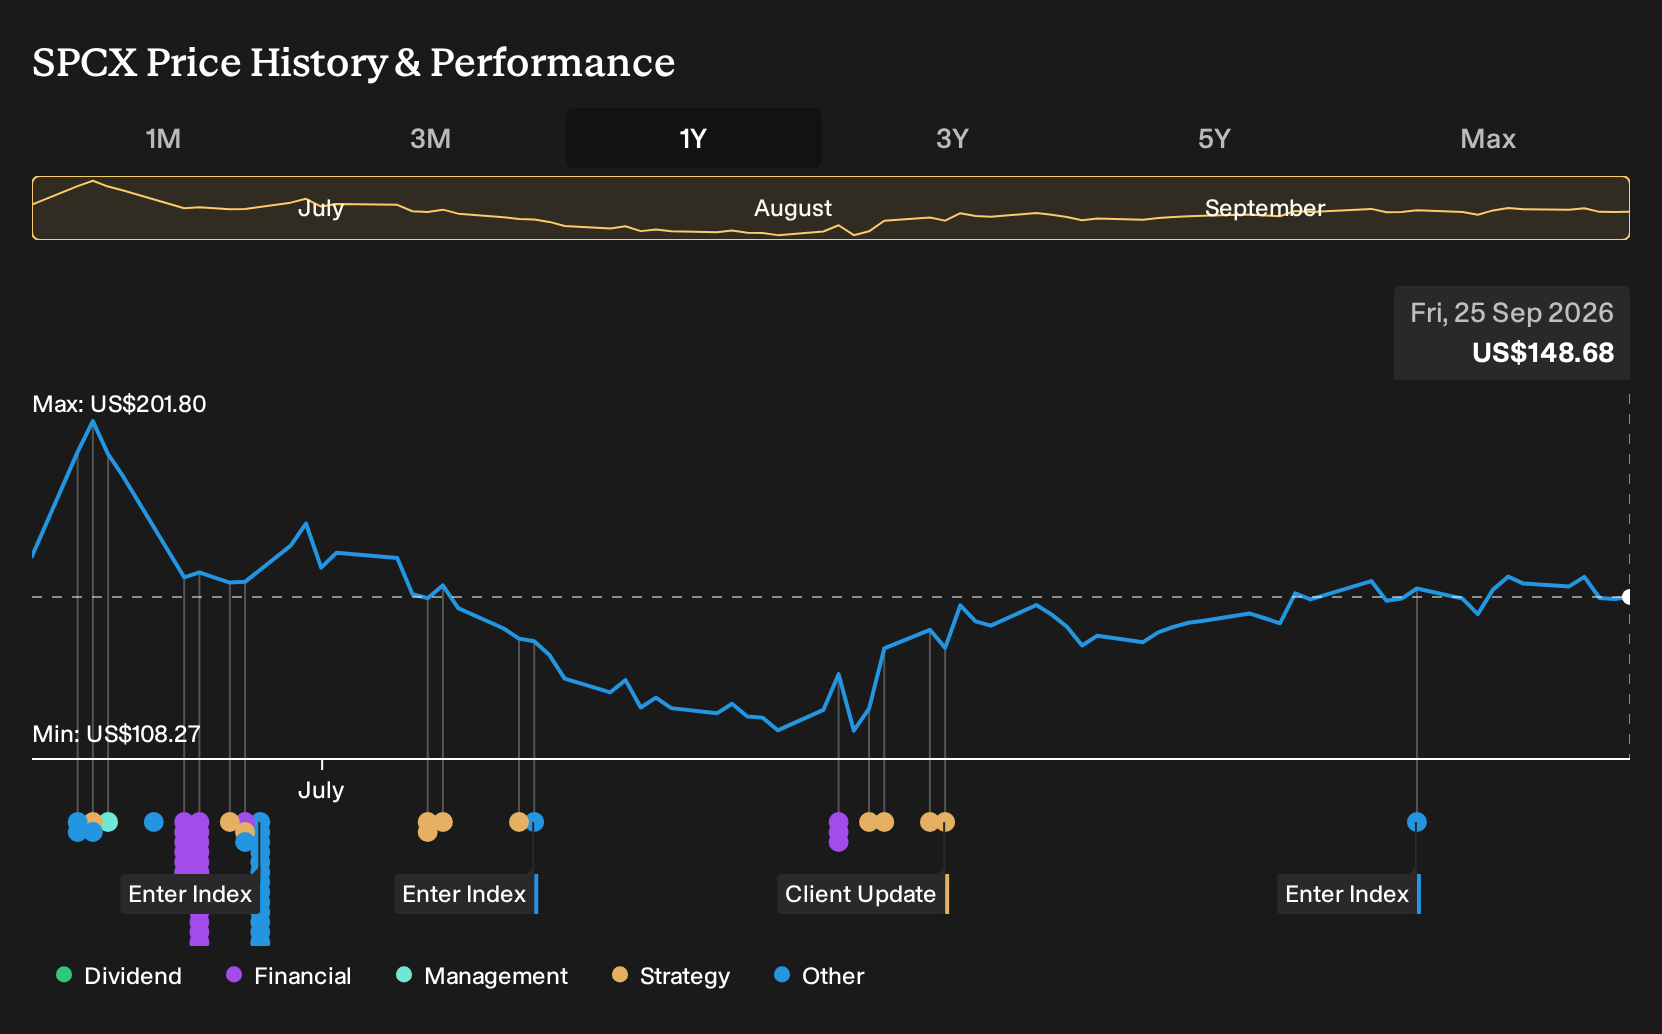
Space Exploration Technologies (SPCX)
Overview: Space Exploration Technologies runs Starlink, a founder-driven satellite broadband network, alongside launch services and AI infrastructure spanning rockets, platforms, and data centers.
Operations: Space Exploration Technologies generates about US$13.9b from Connectivity, US$5.1b from AI, and US$4.1b from the Space segment.
Market Cap: US$2,017.8b
Space Exploration Technologies matters for a founder-led screen because Starlink is Elon Musk’s personally championed connectivity project, where his capital decisions and long-term vision are most visible to outside shareholders.
"Starlink satellite internet is currently the main driver of revenue and is the only division reporting an operating profit."
What happens to future returns if a single, critical capital decision around this project sharply shifts how cash flows are shared and priced?
If that capital swing is what you care about, read the full narrative for Space Exploration Technologies to see how Space Exploration Technologies could have Starlink reshape risk and upside.
Super Micro Computer (SMCI)
Overview: Super Micro Computer builds high performance, modular servers and storage systems tailored for AI and data center workloads worldwide.
Operations: Super Micro Computer generates about US$39.1b from high performance server solutions, with roughly US$27.7b in the United States and US$11.4b internationally.
Market Cap: US$28.4b
Super Micro Computer fits this founder-led theme because Charles Liang still shapes the AI server roadmap himself, tying leadership decisions directly to liquid cooled racks, GPU dense blades, and full data center build outs that carry his name as much as the ticker.
"The accelerating global adoption of AI and analytics continues to drive demand for high-performance, scalable server and data center solutions, positioning Super Micro for strong multi-year revenue growth as enterprises and nations build out AI infrastructure."
What really moves the needle from here is how one pressure on profitability plays out as those huge AI server commitments turn into shipments.
That profitability squeeze is the real question, and the full narrative for Super Micro Computer maps how Super Micro Computer’s AI build out, capital intensity and pricing power could be decoupling beneath the headlines.

Seeking Alternatives Before The Crowd?
Fresh breakouts and quiet compounders rarely stay under the radar for long. Momentum shifts fast, information decays, and ideal entry points get caught and repriced quickly, so consider acting promptly.
- Spot early strength by scanning 30 resilient stocks with low risk scores to help keep portfolio swings contained while markets move in every direction.
- Ride structural demand by reviewing 40 power grid technology and infrastructure stocks that focuses on the backbone of future electricity networks before valuations adjust.
- Target real-world AI demand by checking 85 AI infrastructure stocks that provides the chips, racks, and power behind data centers while they may still be under the radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com