
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Atlas Copco (OM:ATCO A) Undervalued After Its North American Service Center Buildout?
Atlas Copco (OM:ATCO A) stock is in focus after the group started construction on a 355,000-square-foot North American Service Center in Lancaster County, South Carolina. The project is aimed at expanding logistics and service capacity.
The new North American Service Center news lands while Atlas Copco shares trade at SEK205.4, with a 1-day share price return of 1.08% and a 7-day share price return of 4.16%. This points to building near-term momentum after a modest 30-day dip of 0.58% in the share price and longer-term total shareholder returns of 34.29% over 1 year and 72.06% over 5 years.
Scan how Atlas Copco’s expansion story compares with other industrials showing similar momentum by reviewing our handpicked 40 power grid technology and infrastructure stocks in related logistics and infrastructure plays.
Bulls see Atlas Copco’s North American buildout and steady shareholder returns as evidence the current price still leaves room. Bears point to the premium tag and execution risk. Which case does the valuation math lean toward next?
Most Popular Narrative: 6% Undervalued
Atlas Copco is trading at SEK205.4 against a widely followed fair value estimate of about SEK218.5, so the construction push in North America is being judged against expectations for higher earnings power and margins over time.
The expanding, high-margin service and aftermarket business continues to grow robustly across business areas, increasing recurring revenue streams and helping to stabilize and lift group operating margins even amid volatility in equipment orders.
See why 30 investors see Atlas Copco as 6% undervalued.
Result: Fair Value of SEK218.48 (UNDERVALUED)
Still, currency pressure and any prolonged weakness in large compressor orders could quickly challenge the case that Atlas Copco is modestly undervalued.
Find out about the key risks to this Atlas Copco narrative.
Another View on Atlas Copco’s Valuation
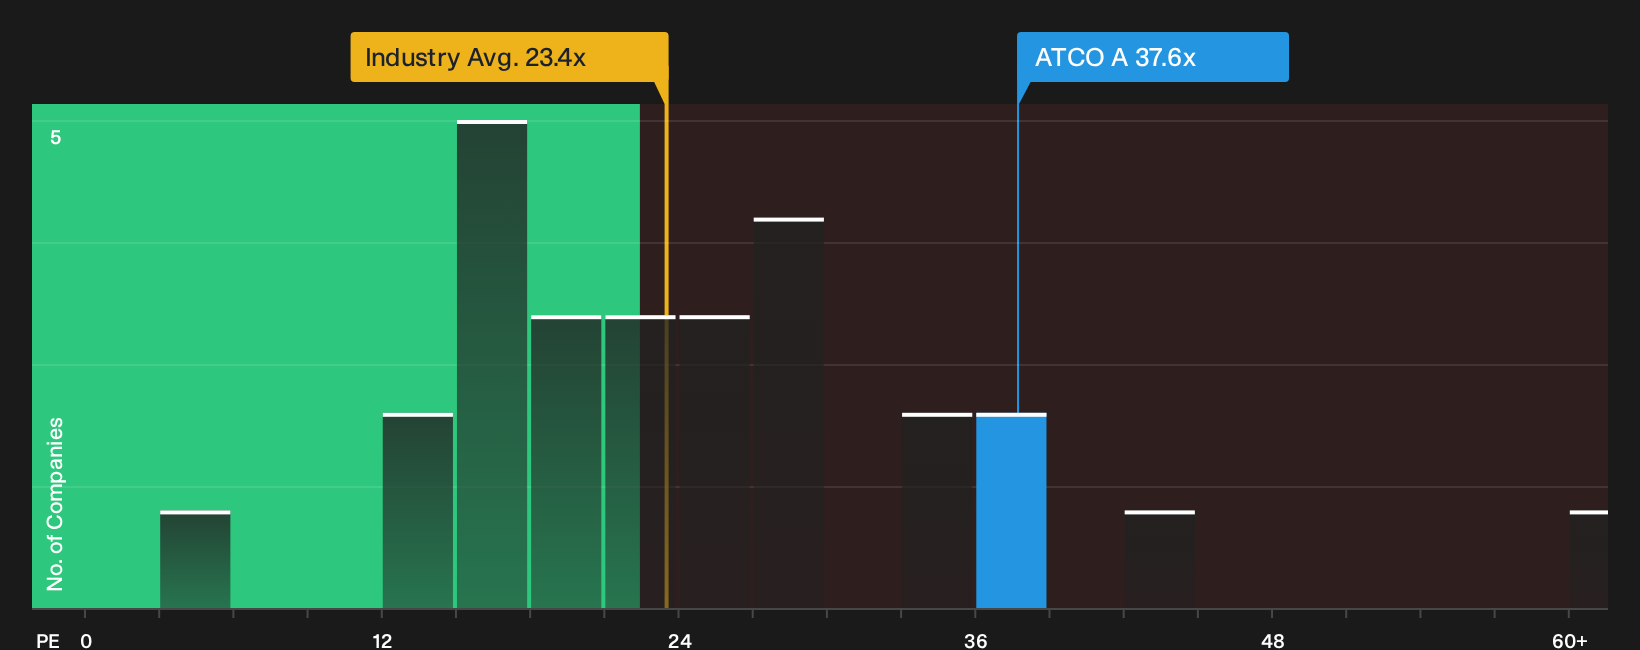
The first narrative frames Atlas Copco as modestly undervalued around SEK205 on a fair value of about SEK218, yet the current P/E of 37.6x paints a different picture. That multiple is higher than the Swedish Machinery industry on 23.4x, peers on 27.8x, and even the fair ratio of 36x. This points to a richer price tag and less margin for error if growth stumbles. Which lens do you trust more when risk and return start to pull in opposite directions?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed tone around Atlas Copco leaves you on the fence, move fast and test the numbers yourself. Then weigh the upside case in detail through 1 key reward
Looking for more Atlas Copco style investment ideas?
Do not stop at Atlas Copco. Use the Simply Wall Street Screener to pressure test other opportunities, compare quality, and build a watchlist that actually reflects your goals.
- Target potential mispricings by reviewing companies highlighted in our 182 high quality undervalued stocks and see which ones line up with your return expectations.
- Strengthen portfolio resilience by focusing on businesses from the list of solid balance sheet and fundamentals (201 results) so you are not relying on fragile finances when conditions turn.
- Hunt for under-the-radar potential through the 619 high quality undiscovered gems before the broader market starts paying attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com