
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Hims And Hers Health (HIMS) Stock Looks Discounted After Its 368% Three Year Run
Hims & Hers Health has been a volatile ride, with long term shareholders seeing very large gains while more recent buyers have faced sharp pullbacks. That puts fresh attention on whether the current price lines up with what the business is actually generating in sales. With that backdrop, the question for anyone looking at Hims & Hers Health today is how much of those expectations are already built into the share price.
- Over the past 3 years, Hims & Hers Health has delivered a share price return of about 3.7x, which makes it important to ask whether the market is paying a stretched or restrained multiple of its revenue.
- The launch of an AI native weight loss care platform that automates parts of the clinical process may support expectations for stronger sales efficiency and potentially faster scaling of revenue relative to operating costs.
- The analysts covering Hims & Hers Health have run their own numbers. See what analysts think Hims & Hers Health's shares could be worth.
The issue now is whether Hims & Hers Health's current US$29.42 share price is justified by its sales when set against the Fair Ratio benchmark.
For context on where Hims & Hers Health sits on this theme, it can help to compare it with other healthcare operators using AI driven models by scanning 38 healthcare AI stocks.
Does Hims & Hers Health Look Undervalued on Sales?
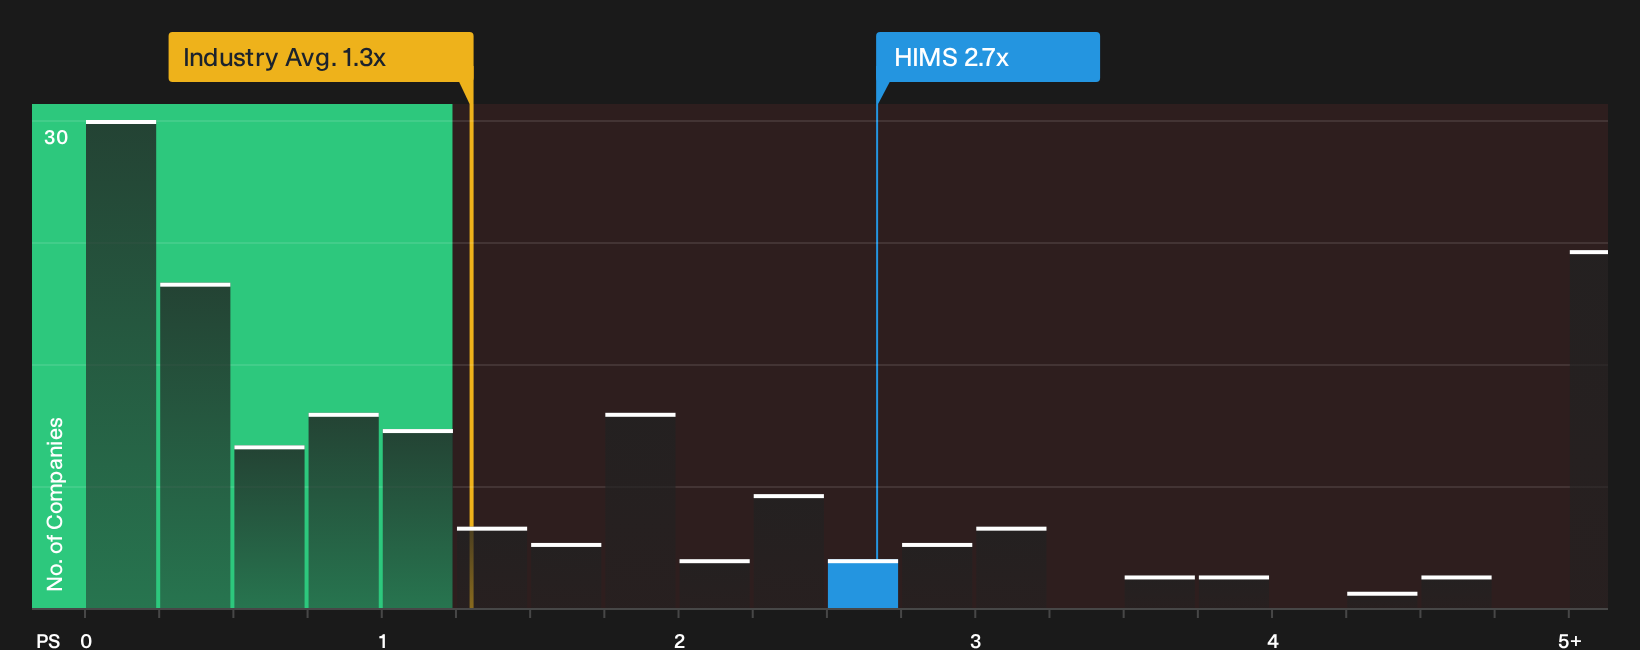
The P/S ratio is a useful guide for Hims & Hers Health because the business is still building its earnings profile while revenue sits at the center of how investors frame it. On this measure, the stock trades on a P/S of about 2.7x, compared with roughly 1.3x for the broader healthcare industry and about 2.2x across closer peers using similar models. That puts the revenue multiple above sector norms but not at an extreme level relative to other companies in comparable niches.
The Fair Ratio framework, which adjusts the sales multiple you might expect for Hims & Hers Health based on factors like growth potential, margins, size and risk, indicates that the current 2.7x P/S sits below that tailored benchmark. Because the recent launch of the AI native weight loss care platform focuses attention on future monetisation of that technology, this gap suggests the market is not assigning a full premium to those expectations on this metric alone. On this basis, the stock screens as undervalued on P/S against this Fair Ratio yardstick, even after the recent regulatory scrutiny from the FTC lawsuit. Explore the numbers behind Hims & Hers Health's P/S valuation.
The Hims & Hers Health Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Hims & Hers Health pick up where the valuation puzzle leaves off by explaining which paths for growth, profit margins and earnings would need to occur for the stock to be worth significantly more or less than today’s price. They appear on the company’s Community page as a way to turn a single P/S or model output into a concrete future you can watch over time.
Community views on Hims & Hers Health are split between investors who see a lot more upside in the story and others who are more restrained.
Bull case: 83% undervalued
"Management continues to invest heavily because it sees strong demand and a much larger opportunity ahead..."
Discover why this Narrative puts Hims & Hers Health at 83% undervalued.
Bear case: roughly fairly valued
"This has some advantages like the projected stellar growth of both revenue and EPS but it will also normally represent the dillution of shares to support it and the negative ROIC..."
Explore why this Narrative puts Hims & Hers Health at roughly fairly valued.
One more Hims & Hers Health check that sits outside the price tag
Valuation only tells part of the Hims & Hers Health story, since our broader review has also flagged specific risk checks that could change how you weigh everything you have just read. Take a closer look at 1 warning sign before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com