
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Renasant (RNST) Could Be 16% Undervalued After Its CFO Transition
Renasant (RNST) has reshuffled its top finance role, with long time CFO Jim Mabry set to retire and incoming executive Catherine Mealor stepping in as chief financial officer from January 2027.
Renasant’s leadership change comes after a mixed stretch for the stock, with the share price at US$40.35 and a year-to-date share price return of 14.08%, but a 90-day share price return that is down 6.94%, while the 3-year total shareholder return of 66.39% points to stronger longer-run momentum.
Scan beyond Renasant and size up other regional banks facing similar margin pressure and credit trends with a hand picked set of 30 resilient stocks with low risk scores.
Renasant looks like a solid regional bank on the surface, with growing loans and credit quality support. The real question is whether that strength is already fully reflected in a US$40.35 share price.
Most Popular Narrative: 16% Undervalued
Renasant is pegged with a fair value of $48 per share in the most followed narrative, compared with the current $40.35 price. This frames the stock as modestly undervalued on that lens.
The company's presence in high-growth Southeastern U.S. markets is expected to benefit from continued migration and positive demographic trends, supporting above-average, mid-single-digit loan and deposit growth for the foreseeable future, which should drive revenue expansion.
The merger with The First Bancshares increases scale and provides a larger footprint in regions experiencing strong small business formation, enabling Renasant to capitalize on rising entrepreneurial activity. This should enhance lending opportunities and fee income over time.
See why 44 investors see Renasant as 16% undervalued.
Result: Fair Value of $48 (UNDERVALUED)
Still, the Renasant story can strain if Southeastern credit conditions weaken or merger integration drags, which could lead to higher costs and more volatile earnings.
Find out about the key risks to this Renasant narrative.
Another Take on Renasant’s Valuation
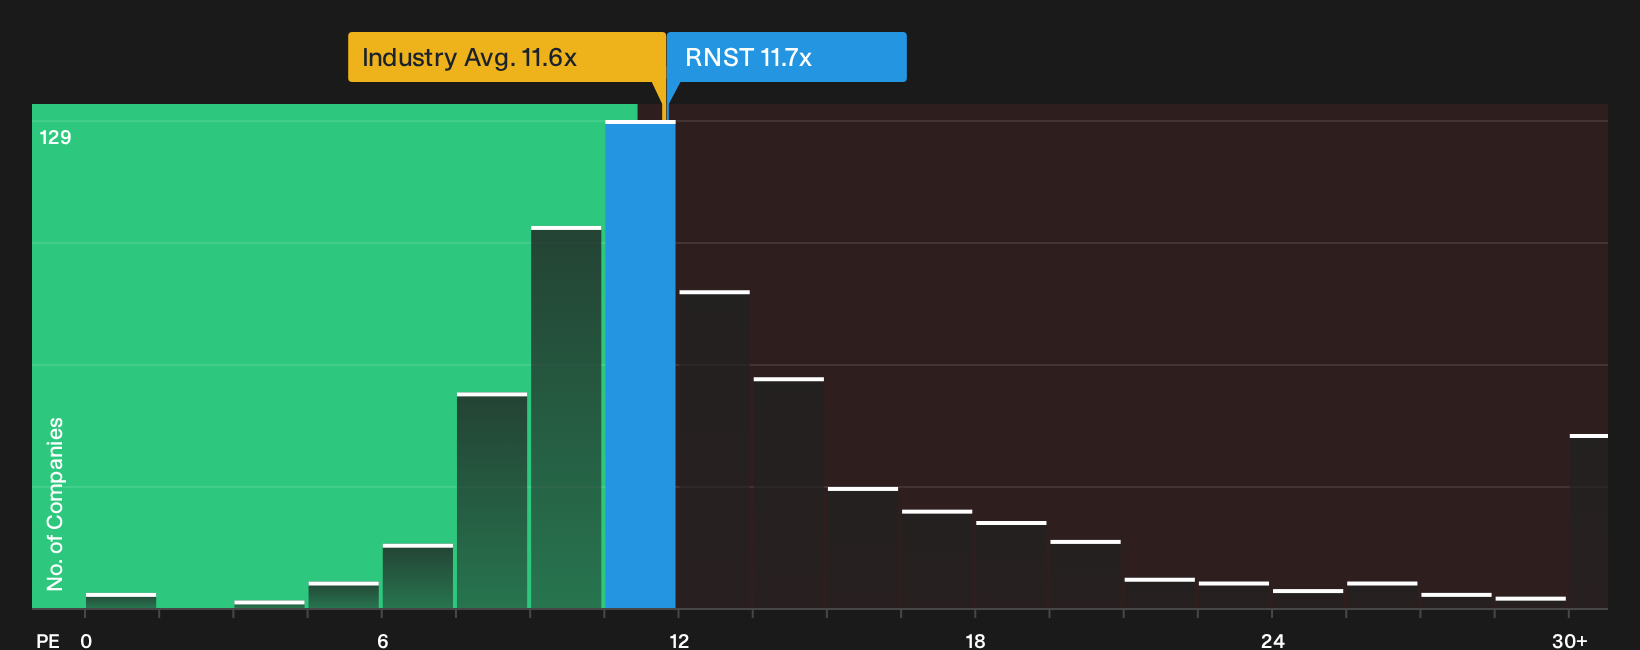
The first lens on Renasant leans on fair value estimates and price targets. A simpler yardstick tells a cooler story. At a P/E of 11.7x, the bank trades almost exactly in line with its own fair ratio of 11.7x, and only slightly above the US Banks industry at 11.6x. That leaves less obvious mispricing and more of a question about whether earnings quality and growth justify even a small premium.
See what the numbers say about this price, and how much room there might be for sentiment to shift, in our valuation breakdown with See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed views on Renasant so far. If you want to cut through the noise and move fast, weigh both sides of the story with 4 key rewards and 1 important warning sign
Looking for more investment ideas beyond Renasant?
If Renasant has your attention but you want a wider bench of ideas, use the Simply Wall Street Screener to pressure test your next move.
- Target resilient balance sheets that can better handle stress by scanning a list of solid balance sheet and fundamentals (24 results).
- Hunt for potential mispricing by zeroing in on a 32 high quality undervalued stocks that might line up with your return and risk preferences.
- Build a portfolio that aims to get paid while you wait by sorting through a curated set of 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com