
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Teekay Tankers (TNK) Stock Looks Reasonable Against Current Earnings
Teekay Tankers has been on a powerful multi year run, and the current share price leaves investors asking a simple question: Is the business now priced in line with what its earnings can reasonably support?
- Over the past 5 years, Teekay Tankers has delivered a very large share price gain. That puts extra weight on whether its current earnings can shoulder that kind of move.
- The company’s model relies heavily on turning freight rates into sustained profits. This can shape how durable its earnings base looks and how much investors may be willing to pay for each dollar of profit.
- There is a second opinion on Teekay Tankers worth weighing. See what analysts think Teekay Tankers's shares could be worth.
For investors, the debate is whether Teekay Tankers’ current earnings justify a share price around US$94 or if expectations have moved ahead of the business.
If you want to test the same earnings based question you are asking of Teekay Tankers across a wider opportunity set, start with 32 high quality undervalued stocks.
Does Teekay Tankers Look Undervalued on Earnings?
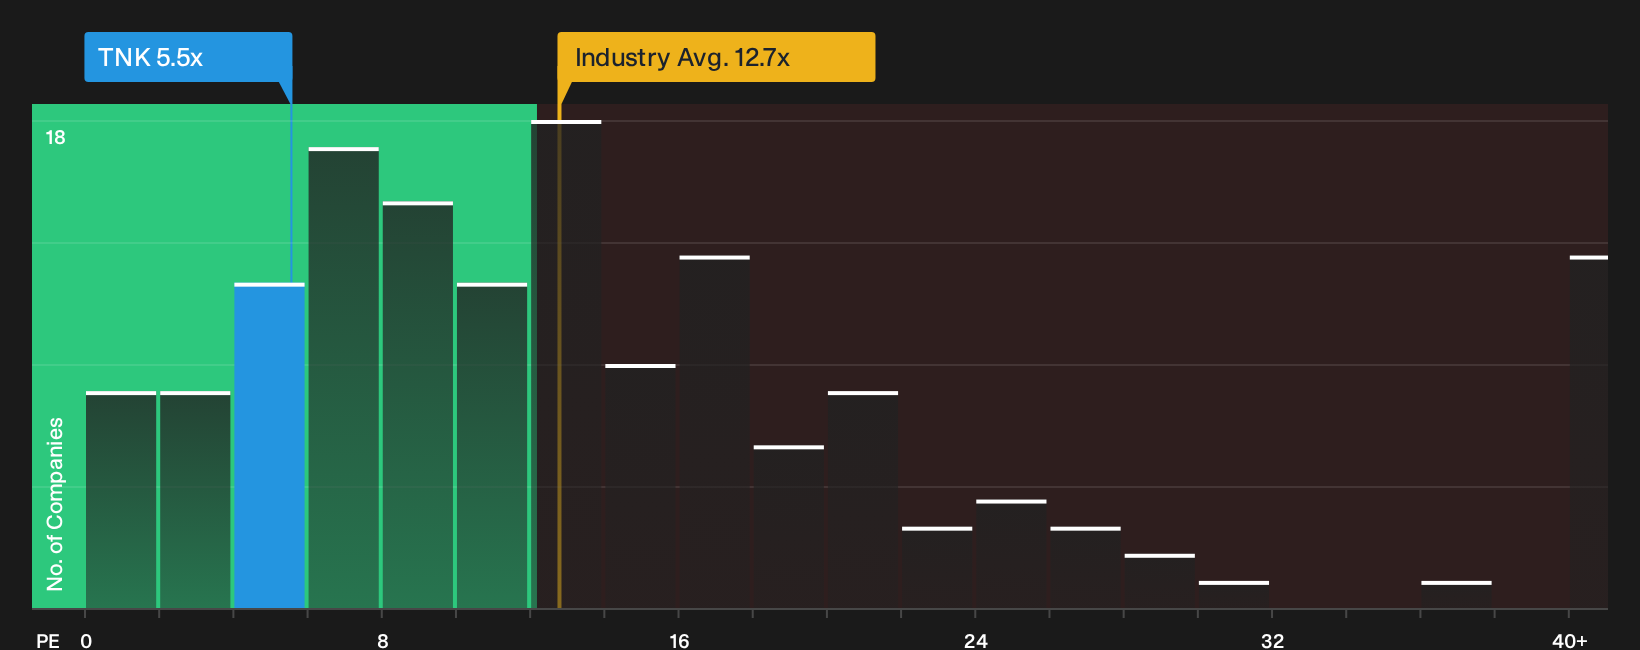
The P/E ratio is a clean way to see what you are paying for each dollar of Teekay Tankers’ recent earnings, which matters for a business built around converting freight rates into profit. At around 5.5x earnings, Teekay Tankers trades well below the broader Oil and Gas industry average of about 12.7x and a peer group closer to 13.5x. That is a wide gap for a stock already trading near US$94.
The Fair Ratio model, which adjusts for the company’s growth profile, margins, size and risk, points to a higher P/E than where the shares change hands today. On this yardstick, the current multiple screens as undervalued relative to what that framework suggests investors might usually pay for these earnings. The key question for you is how durable you think this earnings base is and whether shipping cycles allow Teekay Tankers to keep justifying even a discounted P/E. Explore the numbers behind Teekay Tankers's P/E valuation.
The Teekay Tankers Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Teekay Tankers pick up where the P/E debate leaves off by spelling out which combinations of future freight rates, margins and earnings would need to hold for Teekay Tankers' valuation to look meaningfully higher or lower than today. Each narrative ties a fair value anchor to a particular storyline about the company's potential catalysts and key risks so you can later compare which version of events seems closest to reality.
Community views on Teekay Tankers split between those who see more upside in the current cycle and others who think the share price already reflects most of the story.
Bull case: 18% undervalued
"Teekay Tankers' strong cash flow, unlevered balance sheet, and discipline in asset allocation provide a unique competitive edge..."
Discover why this Narrative puts Teekay Tankers at 18% undervalued.
Bear case: roughly fairly valued
"Slowing oil demand, regulatory changes, and fleet renewal challenges expose Teekay Tankers to volatile earnings, operational risks, and increased sensitivity to market downturns..."
Explore why this Narrative puts Teekay Tankers at roughly fairly valued.
Before leaving Teekay Tankers, one more check belongs beside the price tag
Valuation only tells part of the Teekay Tankers story, since Simply Wall St’s broader review has already picked up specific risk checks that investors may want to weigh for themselves. Take a closer look at 4 warning signs (2 major) before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com