
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Options Volatility At ATS Stock Has Changed Its Investment Story
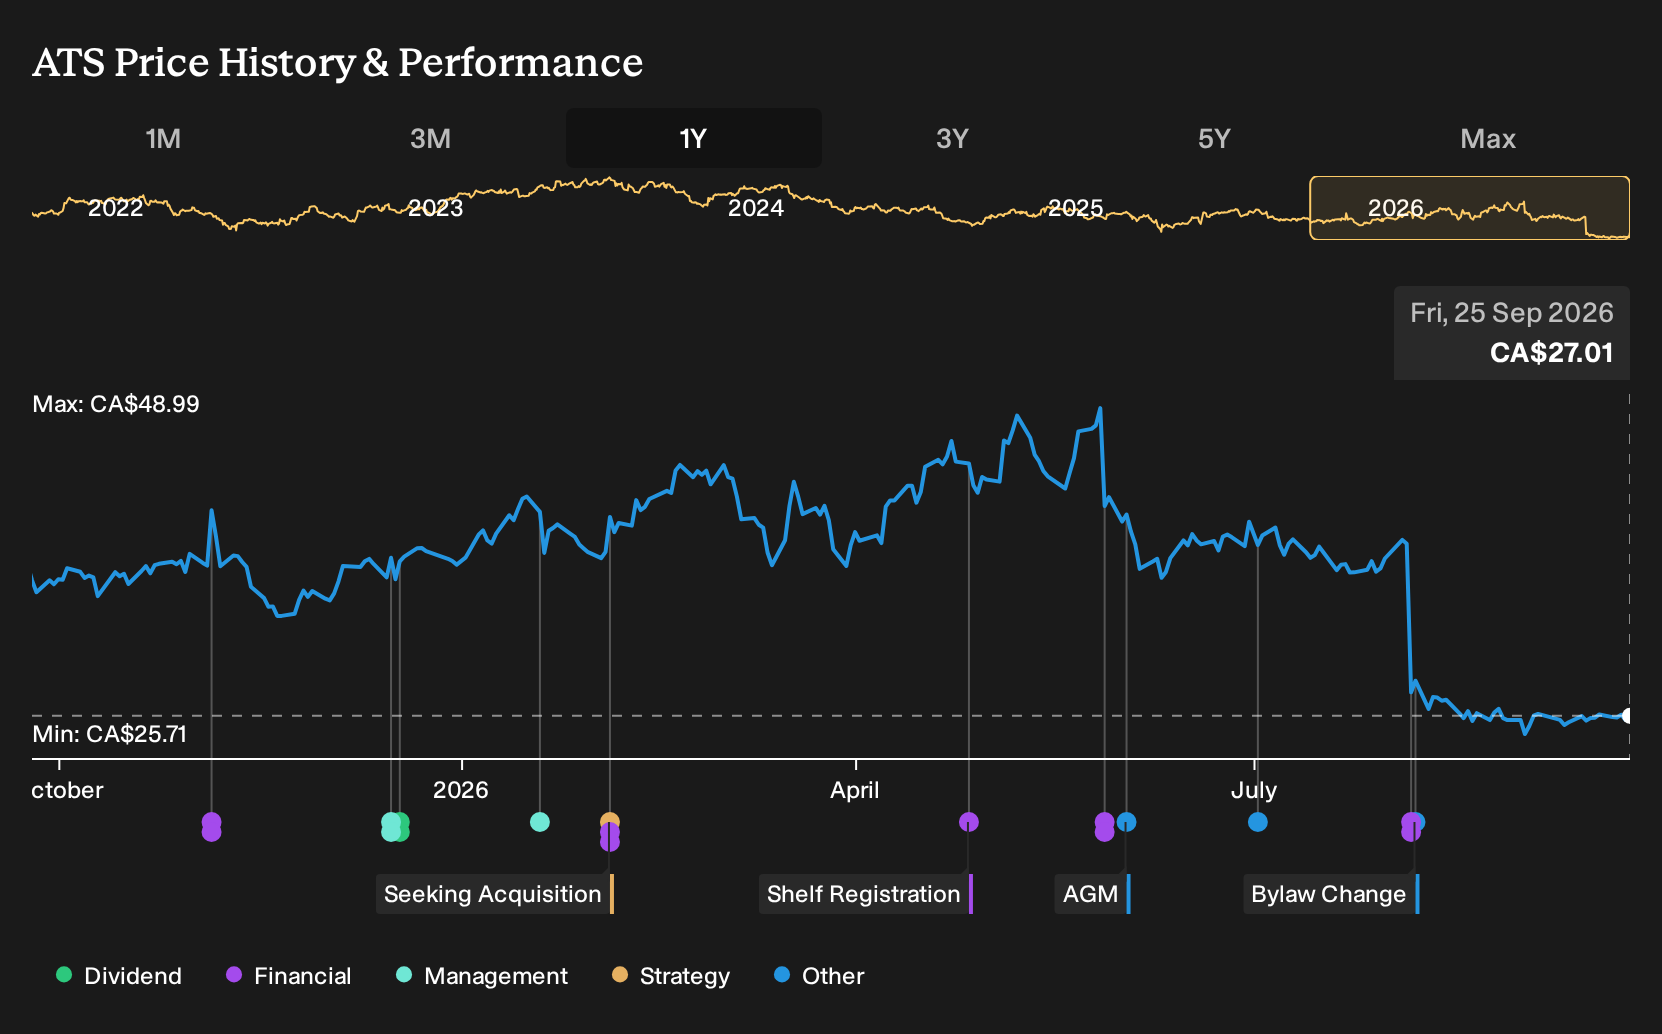
- ATS Corporation has recently seen unusual activity in its options market, with a November call option showing elevated implied volatility. This suggests traders are positioning for a sizable move in the shares tied to potential upcoming company or market events.
- The options activity intersects with ongoing business pressures for ATS, where earnings expectations are being revised lower. This hints that investors are questioning how well the automation specialist can convert its order backdrop and acquisition program into more consistent profitability.
- We will examine how ATS's broader investment narrative around automation, acquisitions and recurring revenue is being challenged by this spike in options implied volatility.
Stress test your thesis on ATS by lining it up against 92 robotics and automation stocks, which options traders may be watching just as closely for the next sharp move.
ATS Investment Narrative Recap
To own ATS, you need to believe the long-term demand for complex automation, especially in life sciences and regulated industries, can support steadier margins and more recurring revenue. The near term story is tougher. Organic growth has been soft, order bookings fell 15%, and leverage is still meaningful, so execution needs to be clean.
The options volatility spike does not change that core thesis by itself. It highlights how sensitive the short term is to any earnings surprise, good or bad. The key near term catalyst remains evidence that ATS can turn its backlog into higher quality, less lumpy profitability. The biggest risk is that integration costs, SG&A creep, and GLP 1 project concentration keep net margins under pressure.
There is no fresh corporate announcement directly tied to this specific options action. That puts the focus back on the last set of reported fundamentals. Those figures show ATS with CA$2.93b in revenue and CA$47.2m in net income, alongside high leverage and interest costs that are not comfortably covered by earnings.
For you as a shareholder, the read-through is straightforward. Any upcoming update that clarifies organic growth, order trends in transportation, and exposure to GLP 1 auto injectors will matter more now that volatility is elevated. Stronger cash generation and evidence of cleaner, less one off earnings quality would do the most to ease concerns about balance sheet risk and the sustainability of the automation story.
ATS' current analyst narrative points to revenues of CA$3.1b and earnings of CA$227.0m by 2029. That profile assumes 1.8% yearly revenue growth and an earnings increase of about CA$179.8m from CA$47.2m today.
Uncover why ATS' fair value indicates a 40% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Options traders are zeroing in on one thing you might overlook in ATS: the fixed cost transformation and European footprint consolidation. The most cautious analysts already pencilled in only CA$3.1b of revenue and CA$219.0m of earnings by 2029, and the new volatility spike could push those expectations, and the story around them, even lower.
Explore 2 other ATS fair value estimates, including one that suggests it could be worth just CA$37.76.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your ATS research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for ATS. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ATS' overall financial health at a glance.
Looking for more ideas beyond ATS?
If the ATS story has you rethinking your watchlist, this is a good moment to broaden your research and compare it with other opportunities using the Simply Wall St Screener. You can review balance sheets, income profiles and risk checks in a few minutes to see where ATS really fits in your wider plan.
- If capital protection is front of mind, scan through a set of companies with steadier risk profiles by reviewing 8 resilient stocks with low risk scores.
- For investors hunting for mispriced quality, weigh ATS against a curated pool of companies that screen as attractively valued through 5 high quality undervalued stocks.
- If you want a watchlist of financially resilient operators, build out a shortlist using the list of solid balance sheet and fundamentals (7 results) to focus on firms with stronger foundations.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com