
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
ACEA (BIT:ACE) Stock May Be Reasonable Despite Its Earnings Discount
ACEA has delivered a powerful run for long term holders, yet the recent pullback invites a fresh look at whether the current share price is still backed by its earnings power. For anyone tracking the utility group, the question now is how that earnings profile stacks up against what the market is paying today.
- Over the past 3 years the ACEA share price has climbed 127.2%, which puts a lot of weight on the company’s ability to keep justifying that move through its profits.
- The business model is tied to regulated utilities and recurring services, so future earnings capacity can hinge on how efficiently ACEA turns that steady revenue into cash flow and what it invests back into its asset base.
- The analysts covering ACEA have run their own numbers. See what analysts think ACEA's shares could be worth.
The stock’s next move may depend on whether ACEA’s current earnings justify the valuation implied by today’s share price.
If you are weighing ACEA on its earnings alone and want a broader yardstick, it can help to compare it with a wider set of 182 high quality undervalued stocks.
Does ACEA Look Undervalued on Earnings?
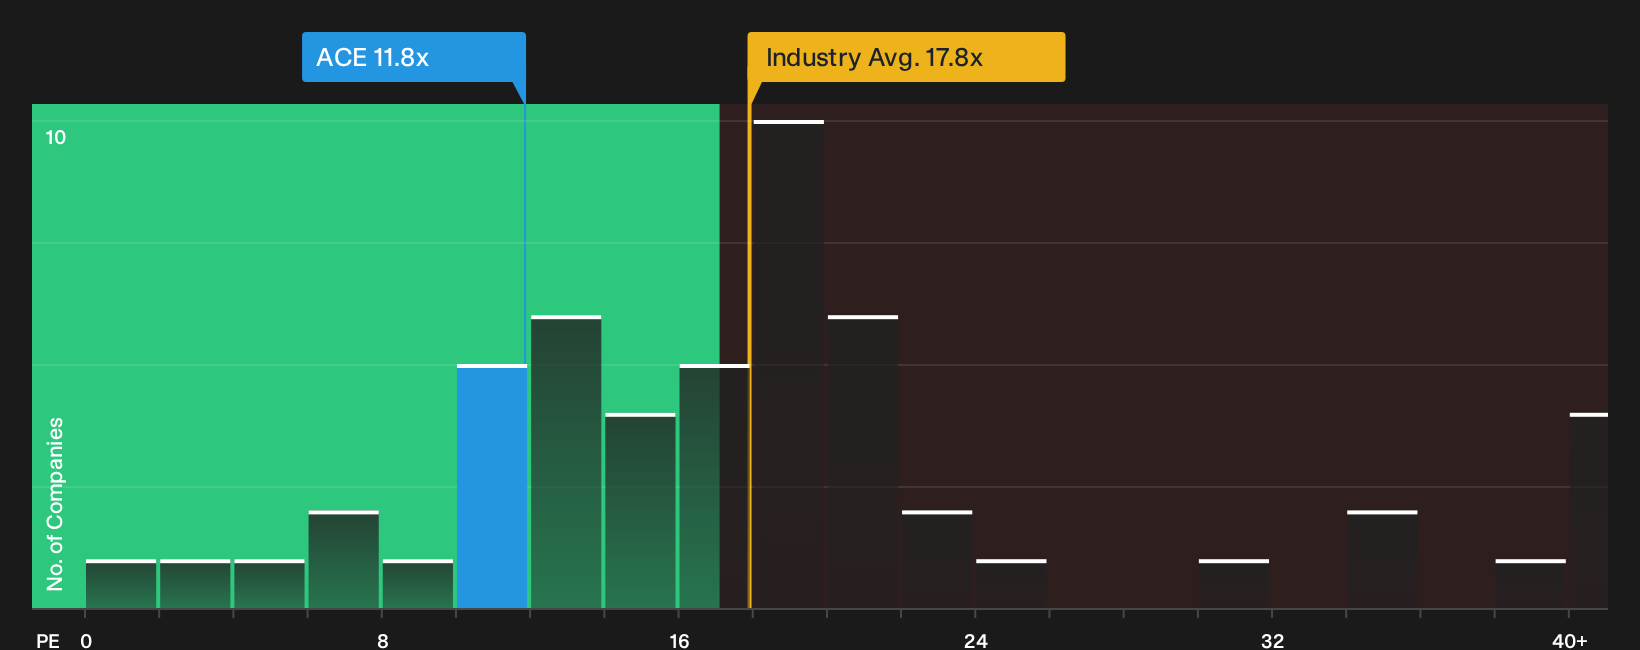
The P/E ratio tends to suit a regulated group like ACEA because earnings are a central part of how investors usually weigh utility valuations. On this measure, ACEA trades on roughly 11.8x earnings, which comes in well below the integrated utilities industry average of about 17.8x and the broader peer group at around 18.6x.
The Fair Ratio model, which adjusts for ACEA’s own growth profile, profitability, size and risk, points to a higher earnings multiple than the one the shares currently command. That keeps the current P/E on the undervalued side of this tailored yardstick, suggesting the market is applying a relatively cautious price tag to each euro of profit. For anyone assessing ACEA, the key question is whether that lower multiple fairly reflects the company’s regulatory exposure and reinvestment needs or whether it leaves room for a re-rating if its earnings path holds up. Explore the numbers behind ACEA's P/E valuation.
The ACEA Narrative: What Would Justify Today's Price?
Narratives for ACEA pick up where the valuation puzzle leaves off. They spell out which paths for growth, margins and earnings would need to play out for the current share price to look materially high or low. Each narrative links its number to a specific view on how ACEA's profitability, investment needs and risks might shift, giving you something concrete to revisit as fresh information comes through.
One of the top community narratives on ACEA: 23% undervalued
"The planned pivot to >95% of EBITDA from regulated infrastructural businesses, including the disposal of ACEA Energia, is expected to enhance earnings stability…"
Discover why this Narrative puts ACEA at 23% undervalued.
Before acting on ACEA's valuation, one more factor needs a closer look
Price, earnings and narratives only go so far when the real choices come from the people in charge and the way their pay is structured. See who runs ACEA and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com