
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Greatland Resources And 2 Other Australian Undervalued Stocks
When US 10 year Treasury yields sit above 5% and global borrowing costs stay elevated, investors are suddenly paying a lot more attention to cash coming through the door today rather than distant profit hopes. That shift creates an opening in Australian markets where some cash rich businesses trade below fair value on discounted cash flow measures. This article highlights three such stocks that screen as attractively priced on their cash generation.
The three stocks covered below are just a sample pulled from this idea, with the wider screen surfacing 4 more companies with similarly cash rich stories that do not fit into a short article format.
If you want to identify and analyze the full set of undervalued cash flow opportunities, head straight to the Undervalued Stocks Based On Cash Flows screener.
Greatland Resources (ASX:GGP)
Overview: Greatland Resources is a gold and copper miner focused on developing the Havieron project in Western Australia, targeting future cash flow from production.
Operations: Greatland Resources currently records all A$2.26b of its revenue from the Telfer Havieron segment, reflecting a concentrated operating base.
Market Cap: A$7.26b
For the Undervalued Stocks Based On Cash Flows theme, Greatland Resources matters because its Havieron project ties real, producing assets directly to future cash generation rather than distant blue sky hopes.
"The primary driver of Greatland’s future is the gold price. As a single-asset developer moving toward production, it offers significant operational leverage to gold."
What happens to those cash flow expectations if a single pressure on project delivery quietly shifts in the background?
That single pressure point is exactly what the full narrative for Greatland Resources unpacks in depth. It shows where execution risk could accelerate or stall Greatland Resources’ cash story.
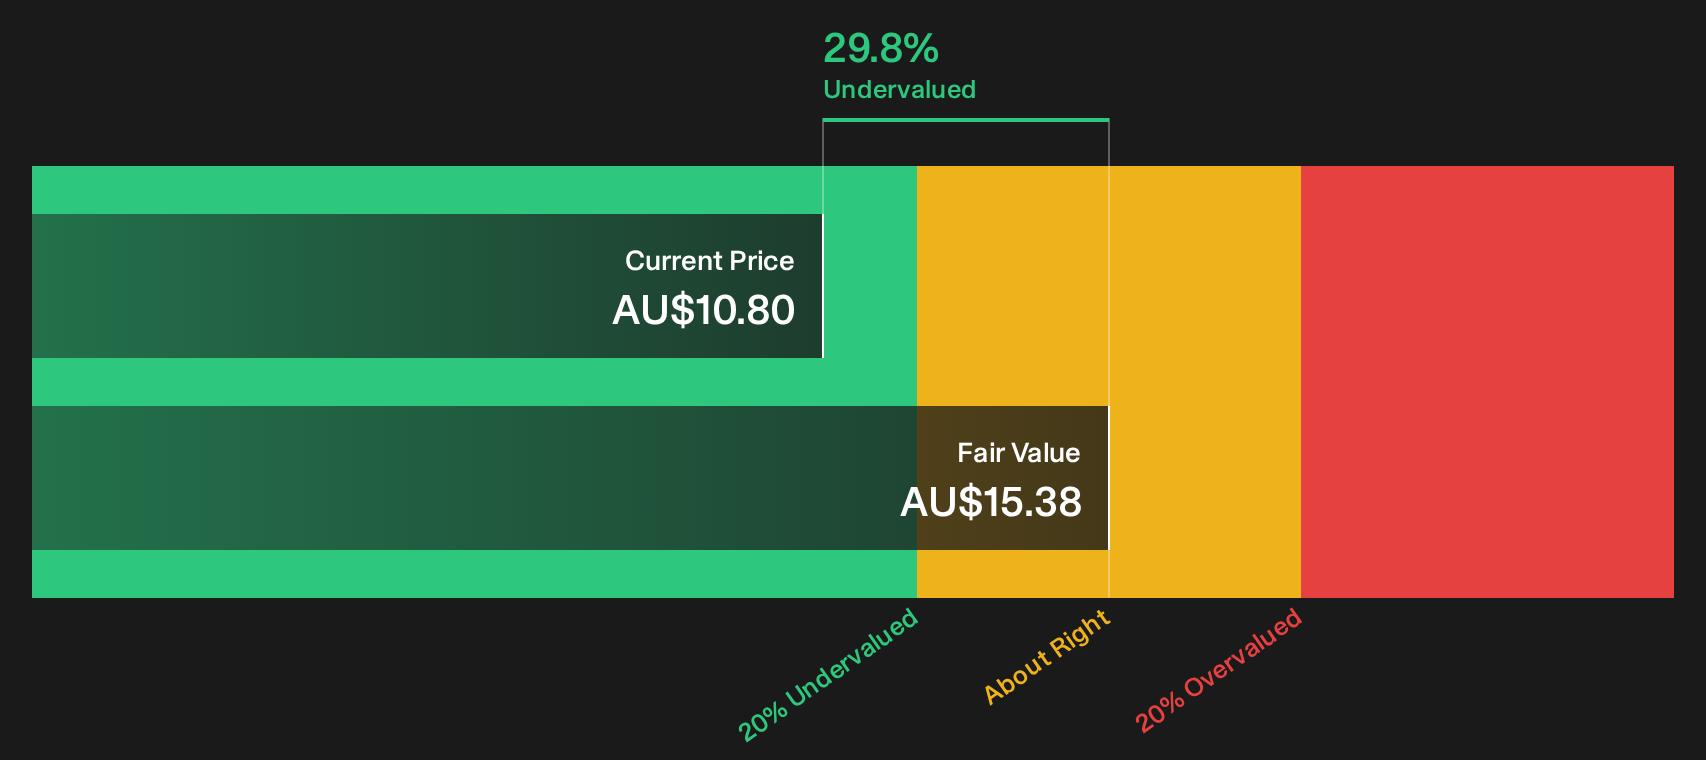
Woodside Energy Group (ASX:WDS)
Overview: Woodside Energy Group is a global hydrocarbon producer, with LNG projects like Pluto, North West Shelf and Wheatstone driving its cash engine.
Operations: Woodside generates about $7.3b from Australian operations, $4.6b from international activities and $1.9b from its marketing segment.
Market Cap: A$60.3b
Woodside Energy Group matters for this cash flow focused screen because its LNG portfolio converts large, long term offtake contracts into recurring operating cash that underpins discounted cash flow valuations.
"Investor optimism appears driven by robust expectations for long-term demand growth in Asian and emerging markets. Woodside's global LNG expansion (Louisiana, Scarborough) is positioned to capture this growth; however, these assumptions may underestimate the potential for rapid decarbonization policies or renewable adoption, which could affect future revenue and volume growth if LNG demand softens in key markets."
The real tension for Woodside investors sits in how one shift in policy and project timing could reshape both cash yields and future pricing power.
That policy and timing risk is only half the story, and the full narrative for Woodside Energy Group shows where Woodside Energy Group could see cash flows accelerate or quietly decouple from consensus expectations.
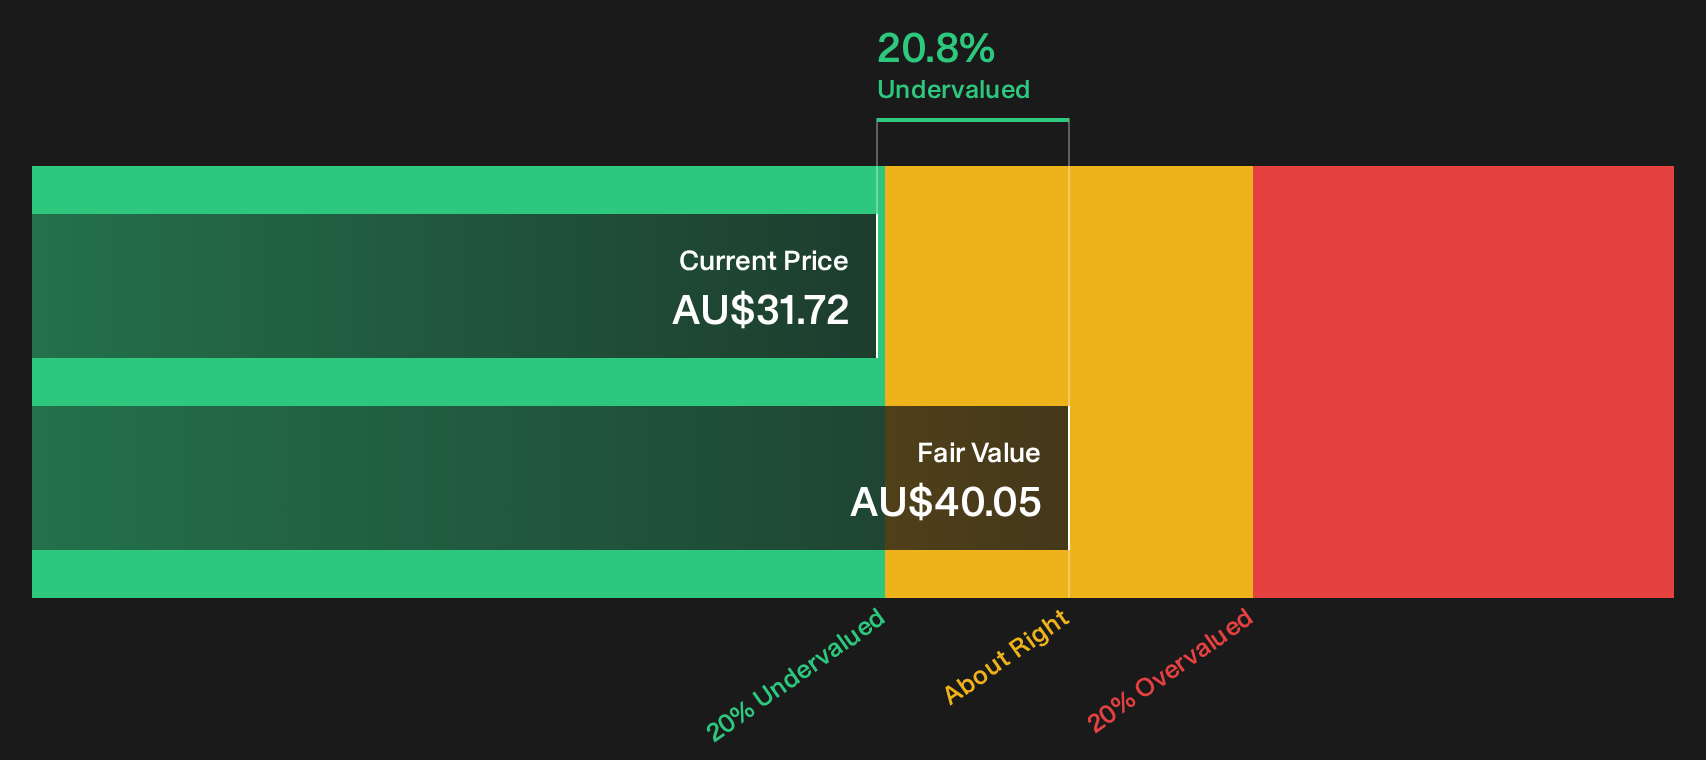
Westgold Resources (ASX:WGX)
Overview: Westgold Resources is a Perth based gold producer that runs large mining and processing operations in Western Australia’s Murchison and Southern Goldfields, turning extracted ore into saleable bullion that drives its cash flow profile.
Operations: Westgold Resources generates about A$1.71b from Murchison and A$732 million from Southern Goldfields, with all A$2.44b earned in Australia.
Market Cap: A$5.1b
Westgold Resources matters for this cash flow focused screen because its gold hubs convert mined ounces into steady operating cash that anchors discounted cash flow estimates.
"The integration of the Karora transaction has significantly increased Westgold's production scale and operational flexibility, positioning the company to benefit fully from sustained global monetary instability and rising geopolitical tensions, with upside leverage to higher gold prices directly feeding into revenue and earnings."
What happens to that cash engine if one key assumption about future production mix quietly shifts away from today’s plan.
When that production mix shifts, the full narrative for Westgold Resources shows whether Westgold Resources’ enlarged footprint is quietly masking risk or setting up accelerating cash generation.

Seeking Fresh Alternatives Beyond These Picks
Fresh ideas tend to move first. Once breakout momentum is obvious, entry points can slip away while prices keep flying. Scan these under the radar ideas now and look for opportunities early.
- Spot income workhorses before yields get compressed by late arrivals when you scan the 3 dividend fortresses.
- Follow early momentum in metal producers that could benefit from tightening supply and steady demand by checking the 17 top copper producer stocks.
- Track the next wave of infrastructure plays supporting AI build outs before capital moves in by reviewing the 85 AI infrastructure stocks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com