
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Berkshire Hathaway (BRK.B) Names A New Chairman, Is The Stock Cheap?
Leadership change at Berkshire Hathaway and what it could mean for investors
Warren Buffett has stepped down as chairman of Berkshire Hathaway (BRK.B), with his son Howard Buffett becoming chairman while Warren Buffett shifts to chairman emeritus and remains on the board.
The leadership handoff, paired with Warren Buffett’s public warning about U.S. fiscal deficits and potential pressure on the dollar, gives investors a fresh lens for thinking about Berkshire Hathaway’s role in a long term portfolio.
Against this backdrop, Berkshire Hathaway’s share price has been relatively steady, with a 1-year total shareholder return of 1.09% contrasting with a much stronger 3-year total shareholder return of 44.30% and 5-year total shareholder return of 83.34%. This suggests longer term momentum has been stronger than the recent trend.
Scan beyond Berkshire Hathaway to see how other financially solid blue chips are positioned with our hand picked 30 resilient stocks with low risk scores.
Bulls see Berkshire Hathaway as a rare mix of scale, cash and diversification, while bears focus on leadership transition risk and softer recent returns. Which side do the current valuation signals lean toward?
Preferred P/E of 12.6x for Berkshire Hathaway: Is it justified?
Berkshire Hathaway trades on a P/E of 12.6x, which, at a last close of $505.48, points to a valuation that looks cheaper than many peers in the diversified financials space.
The P/E ratio links the current share price to earnings per share, so it effectively shows how many dollars investors are paying for each dollar of profit. For a conglomerate like Berkshire Hathaway, which spans insurance, rail, utilities, manufacturing and retail, this measure gives a simple way to compare the stock with more focused financial groups.
That 12.6x multiple sits well below the US Diversified Financial industry average of 17.3x and the peer average of 22.7x. This implies the market is pricing Berkshire Hathaway’s earnings at a clear discount. Relative to an estimated fair P/E of 16.2x, the current level also looks conservative. The market could move closer to that fair ratio if investors reassess the company’s earnings power.
Explore the SWS fair ratio for Berkshire Hathaway.
Result: Price-to-earnings of 12.6x (UNDERVALUED)
Still, Berkshire Hathaway faces real pressure points, including uncertainty around its leadership transition and annual net income that recently moved in the opposite direction of revenue.
Find out about the key risks to this Berkshire Hathaway narrative.
Another view on Berkshire Hathaway’s value
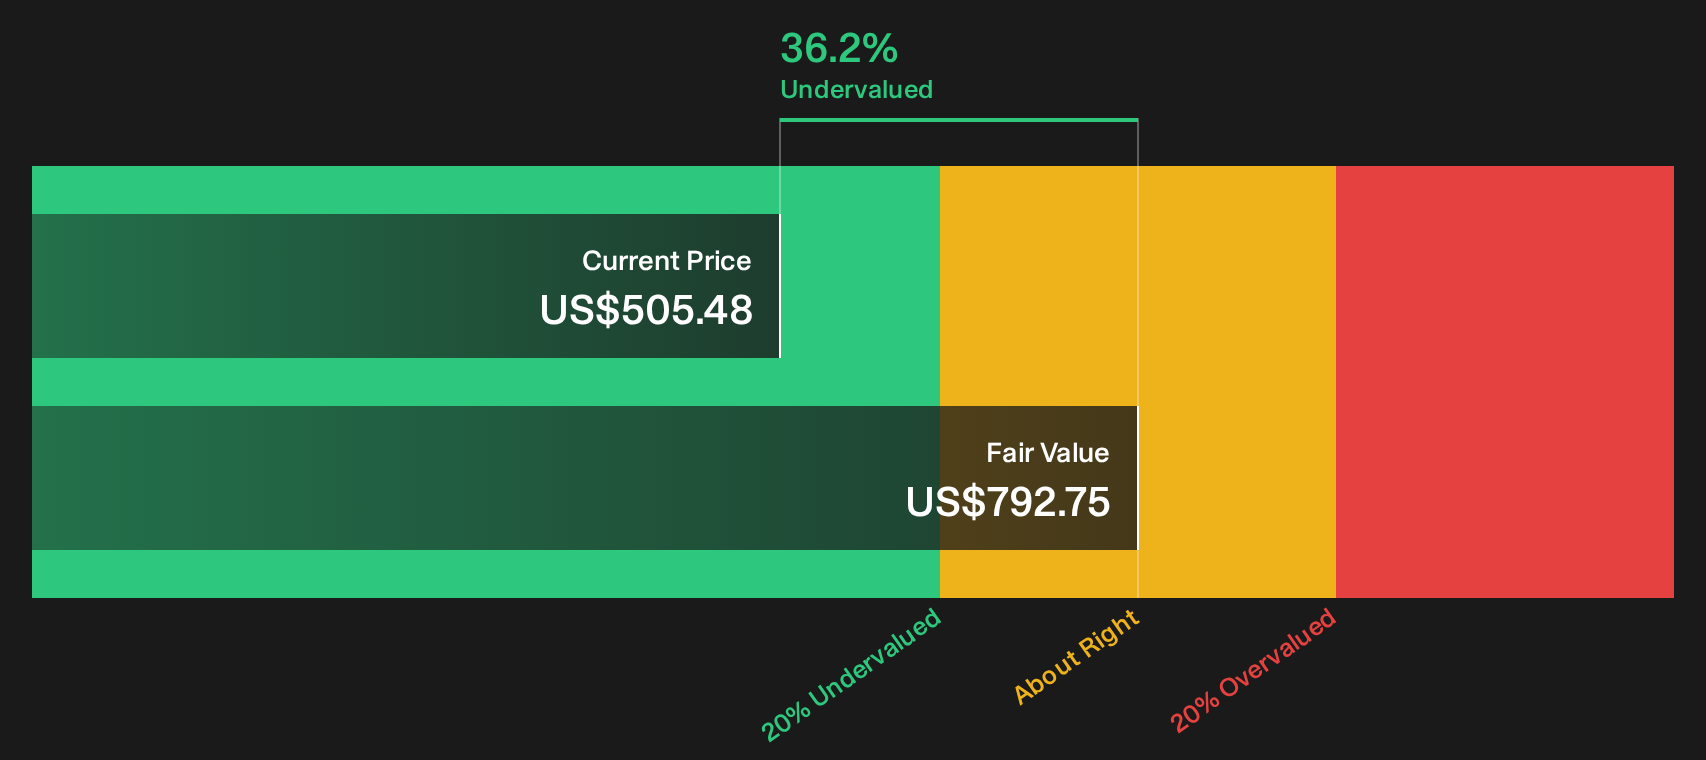
The P/E argument for Berkshire Hathaway points to a discount, but our DCF model paints an even starker picture. At a share price of $505.48 and an estimated future cash flow value of $792.75, the stock screens as undervalued based on that framework.
DCF models hinge on long term cash generation and discount rates, so they can swing more than simple earnings multiples. When two methods both flag a gap, as P/E and DCF do here, the real question for investors is which picture feels more fragile if business conditions or sentiment shift.
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Berkshire Hathaway for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Berkshire Hathaway can feel confusing, so act promptly and review the full picture of risks and rewards before opinions harden by checking the 3 key rewards and 1 important warning sign.
Looking for more Berkshire Hathaway style investment ideas?
If you only focus on Berkshire Hathaway, you could miss other compelling setups. Use the Simply Wall St Screener to widen your opportunity set intelligently.
- Hunt for quality at a discount by reviewing our hand picked 32 high quality undervalued stocks that combine solid fundamentals with appealing prices.
- Target resilience by scanning a focused list of solid balance sheet and fundamentals (24 results) that can help you stress test your portfolio against shocks.
- Spot potential early movers by working through a curated 16 high quality undiscovered gems before the broader market pays attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com