
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Tyson Foods (TSN) Faces A Valuation Test Following Beef Antitrust Settlement Update
Tyson Foods (TSN) is back in focus after a court authorized an amended notice in a long running beef antitrust case, extending key settlement deadlines and confirming Tyson’s planned US$82.5m payment.
For shareholders, the legal update lands after a weak stretch for Tyson Foods’ stock, with a 30 day share price return down 10% and a 90 day move down 13%, while the 1 year total shareholder return is down a milder 3% and the 3 year total shareholder return is up 12%. This points to fading short term momentum against a still positive medium term record.
Scan how Tyson Foods compares with other protein and packaged food players by reviewing our hand picked list of solid balance sheet and fundamentals (24 results).Tyson Foods now trades at a discount to both analyst targets and some intrinsic value estimates after this latest slide. The key question for the next stage of valuation work is how far that gap should reasonably close.
Most Popular Narrative: 21% Undervalued
On the most followed view of Tyson Foods, a fair value of $64.25 against a last close of $50.92 points to a meaningful valuation gap that hinges on how the profit mix and beef restructuring play out over time.
The company is capitalizing on strong, resilient consumer demand for protein across beef, pork, and chicken, with volume and dollar share gains in top brands such as Tyson, Hillshire Farm, and Jimmy Dean; this leverages growing global consumption of animal protein and is expected to support sustained revenue growth and earnings expansion.
See why 44 investors see Tyson Foods as 21% undervalued.
Result: Fair Value of $64.25 (UNDERVALUED)
Still, the Tyson Foods story can break if beef losses persist longer than analysts model and if raw material cost pressure in Prepared Foods squeezes margins again.
Find out about the key risks to this Tyson Foods narrative.
Another View: Tyson Foods On Earnings Multiples
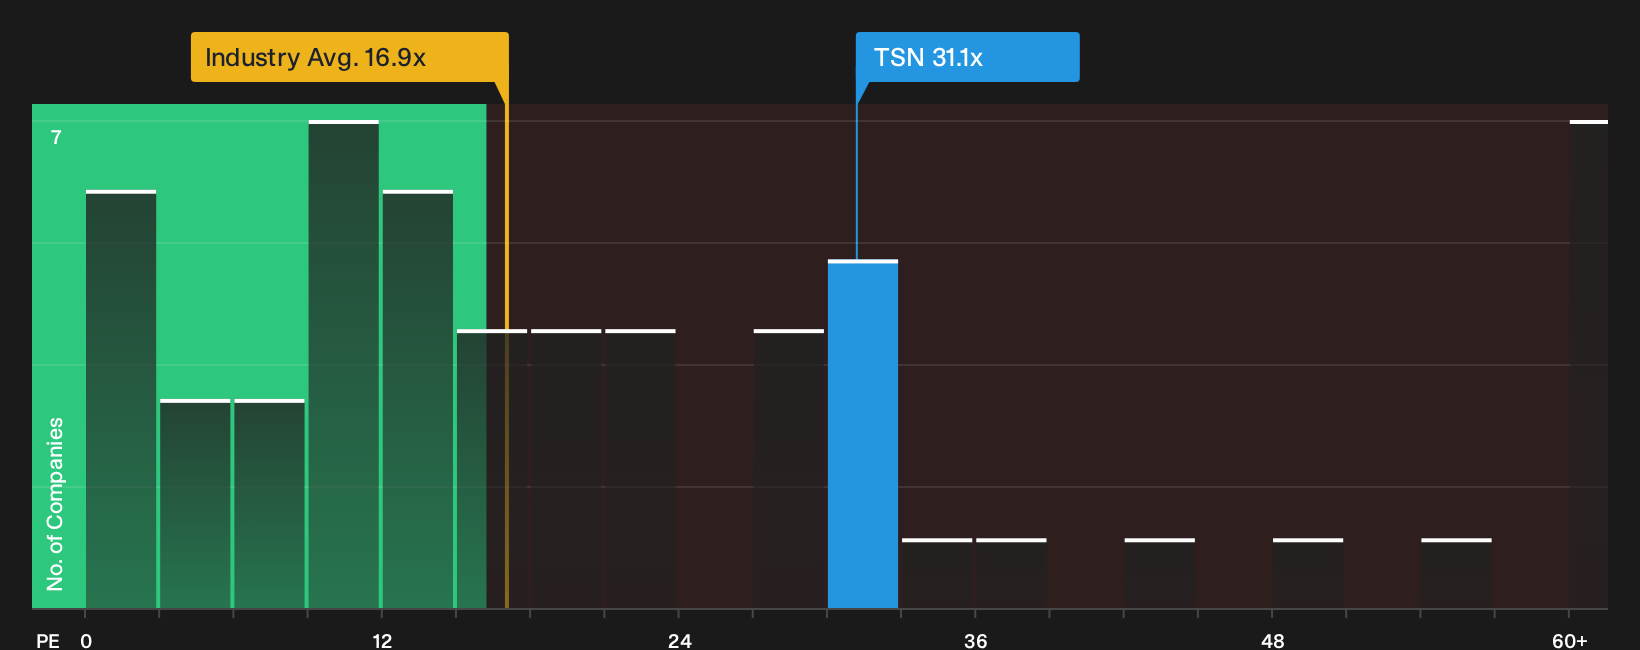
There is a very different read on Tyson Foods when looking at simple earnings multiples. The stock trades on a P/E of 31.1x versus a US Food industry average of 16.9x and a fair ratio estimate of 46.9x. That mix suggests both valuation risk against peers and potential upside if the market ever leans closer to the fair ratio, so which reference point do you trust most?
To see how the current pricing stacks up against that fair ratio and peers in more detail, take a look at the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment on Tyson Foods is clearly split, with investors weighing fresh legal headlines against mixed valuation signals and a patchwork of fundamentals. Consider acting promptly, review the underlying numbers yourself, and weigh both the potential upside and downside by examining the full picture of 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Tyson Foods?
If Tyson Foods has you rethinking your watchlist, do not stop there. Broader opportunity often sits in the stocks you have not checked yet.
- Target resilient balance sheets by scanning companies that pass strict debt and cash flow checks through the list of solid balance sheet and fundamentals (24 results).
- Hunt for potential mispricing by reviewing a curated pool of companies flagged as 32 high quality undervalued stocks before the crowd catches on.
- Prioritize steadier rides by focusing on companies assessed as 30 resilient stocks with low risk scores so you are not relying on just one story to work out.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com