
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Booz Allen (BAH) Stock Still Looks Undervalued On Earnings Strength
Booz Allen Hamilton Holding has seen its share price decline in recent years, which puts fresh focus on whether what investors are paying today lines up with the earnings the business is generating. With the stock now around US$72.95, the question is how that price stacks up against the profit power of the consulting group.
- Over the past 3 years, the share price has fallen about 29%, which puts extra weight on the question of how durable and dependable Booz Allen Hamilton's earnings really are.
- The company relies heavily on government-focused consulting contracts, so the stability of those engagements can influence how predictably its earnings support the current share price.
- Your read on Booz Allen Hamilton Holding is one view; the desks covering it have another. See what analysts think Booz Allen Hamilton Holding's shares could be worth.
The stock's next move may depend on whether Booz Allen Hamilton's current earnings are strong and reliable enough to justify where the shares trade today.
If you want a broader reference point as you assess whether Booz Allen Hamilton Holding's earnings support its current price, a focused screen of 32 high quality undervalued stocks can be a useful next step.
Is Booz Allen Hamilton Holding Still Cheap on Earnings?
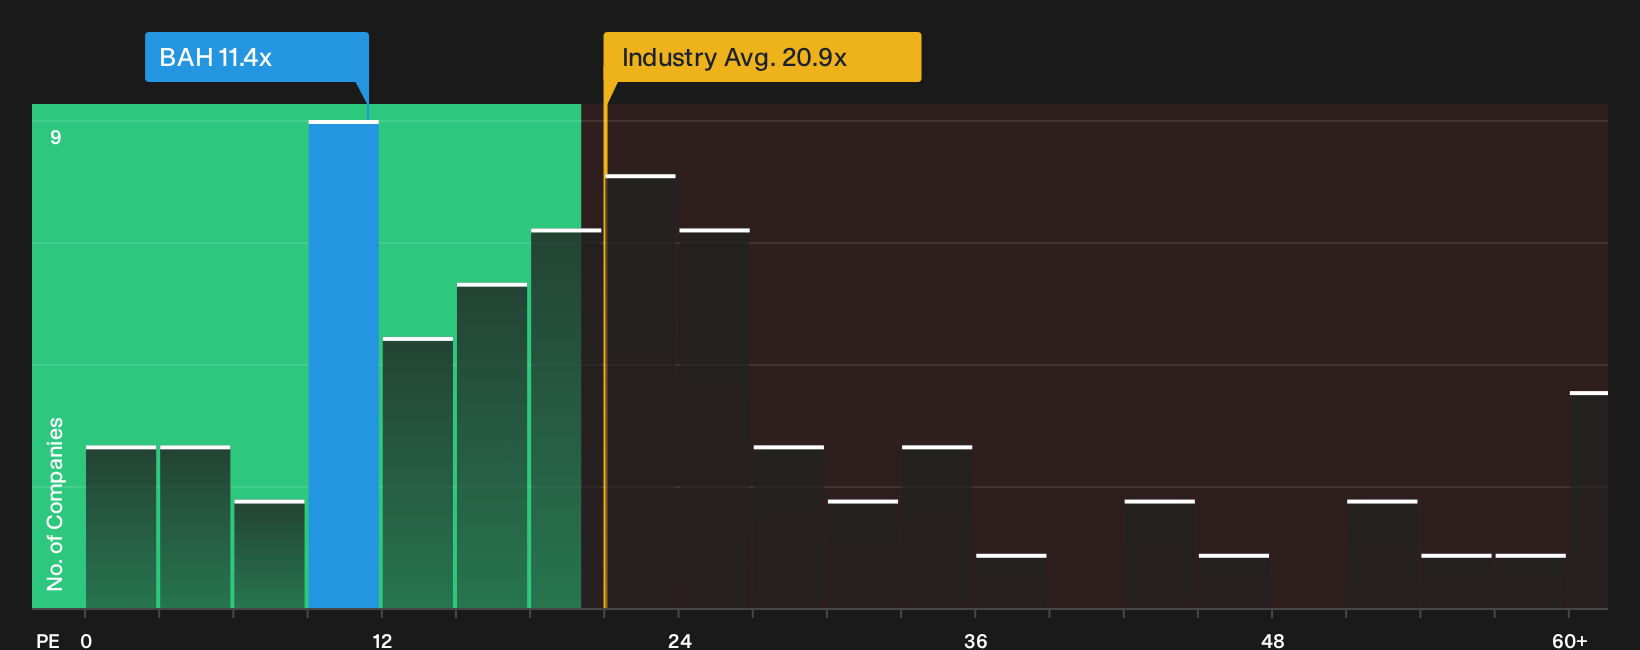
The P/E ratio fits Booz Allen Hamilton Holding well because it links what you pay for the stock to the earnings that come from its consulting contracts. On this lens, the shares trade on about 11.4x earnings, which is markedly below the broader Professional Services industry average of roughly 20.9x and also below peers around 23.2x.
The valuation model suggests a tailored P/E that would usually apply to Booz Allen Hamilton, based on its profitability profile, industry, size and risk mix, is higher than where the shares change hands now. That points to the stock screening as undervalued on this earnings multiple, even before you factor in any company specific views you might have on contract quality, budget exposure or margin resilience. If you want to see how much room there could be between the current P/E and that implied level, it is worth checking the detailed valuation work behind it. Explore the numbers behind Booz Allen Hamilton Holding's P/E valuation.
The Booz Allen Hamilton Holding Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/E puzzle for Booz Allen Hamilton Holding leaves off by explaining what would need to happen to its future growth, margins and earnings for the stock to be worth meaningfully more or less than today’s price. Each one presents Booz Allen Hamilton Holding's estimated worth as a clear thesis about how the business might perform over time, which you can watch play out on the Community page.
Community views on Booz Allen Hamilton Holding are split between those who see underappreciated defense and AI earnings power and those who focus on contract risk and automation pressure.
Bull case: 15% undervalued
"Booz Allen is positioned to benefit from increased federal investment in digital transformation, AI, and cybersecurity, as evidenced by record backlog…"
Discover why this Narrative puts Booz Allen Hamilton Holding at 15% undervalued.
Bear case: 7% overvalued
"Although Booz Allen Hamilton is rolling out AI enabled products such as the Vellox suite, federal clients are also rapidly adopting AI internally…"
Explore why this Narrative puts Booz Allen Hamilton Holding at 7% overvalued.
The price tag on Booz Allen Hamilton is only part of the story
Share valuation is one filter, but the people steering Booz Allen Hamilton and how their incentives line up with your outcomes can matter just as much. See who runs Booz Allen Hamilton Holding and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com