
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Did Cash Dividend News Just Shift Northern Oil and Gas (NOG) Investment Narrative?
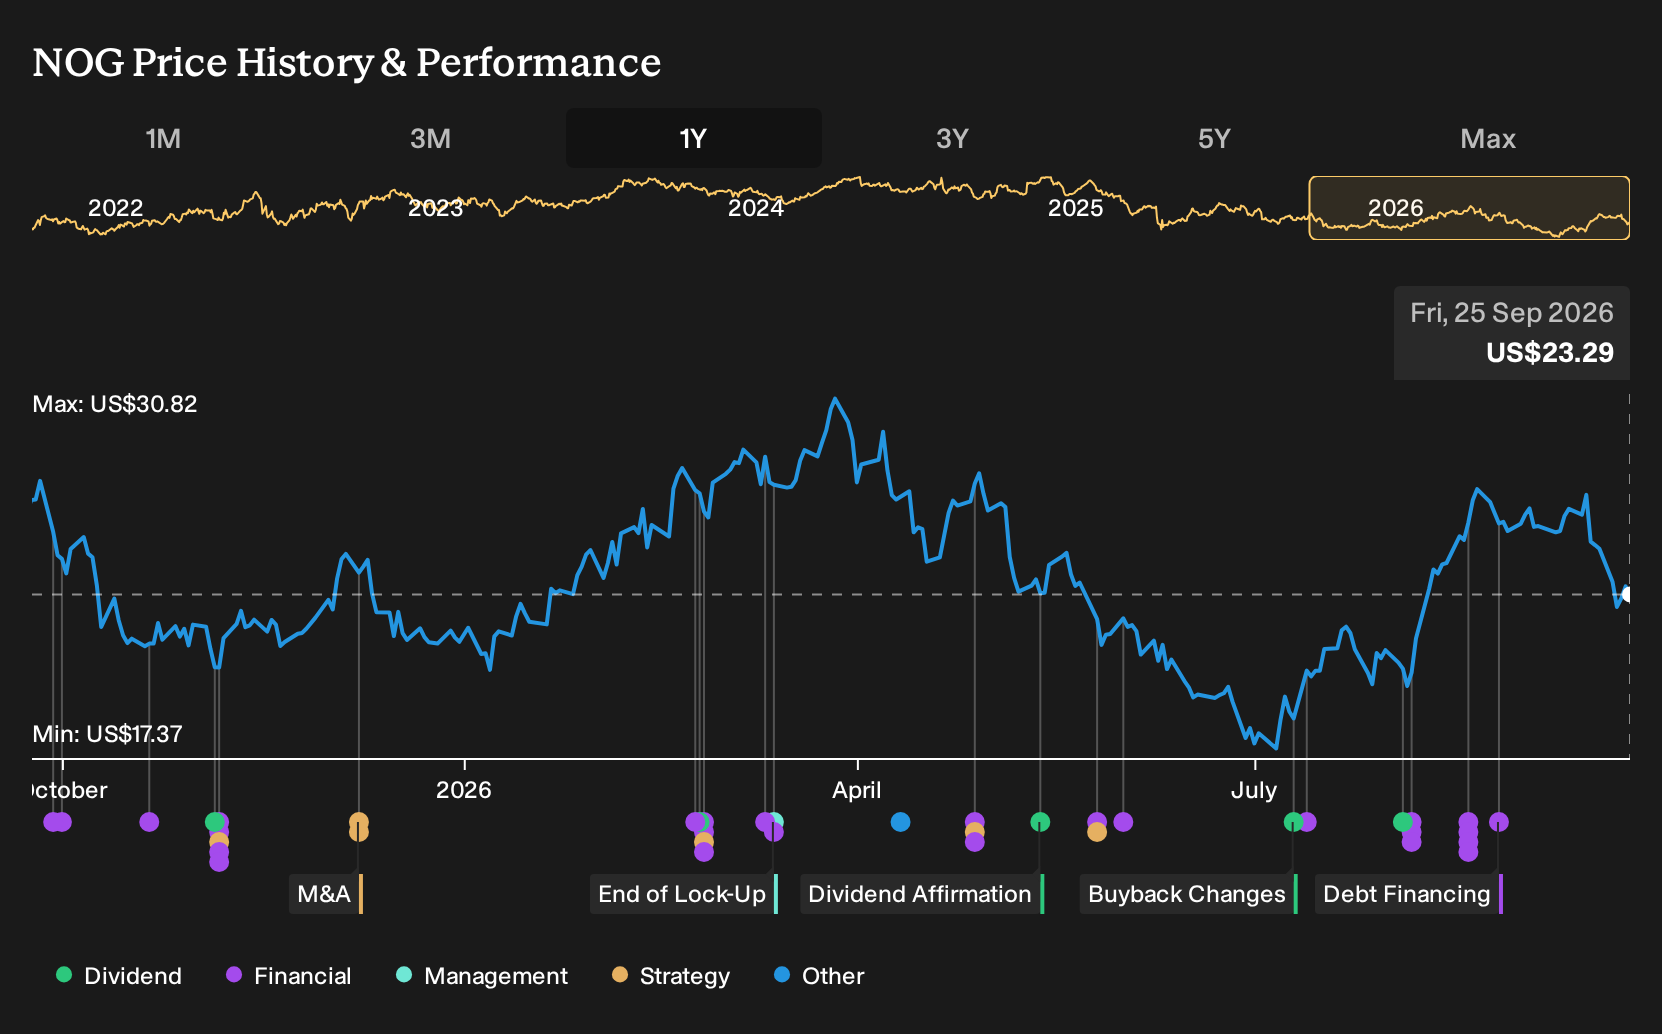
- Northern Oil and Gas, Inc. recently declared a cash dividend of $0.45 per share, with an ex dividend date of September 29, 2026.
- The new payout highlights Northern Oil and Gas's focus on converting its non operating oil and gas interests into direct cash returns for investors.
- This article examines how Northern Oil and Gas's investment narrative is influenced by this cash dividend decision and its payout capacity.
Scan beyond Northern Oil and Gas and line up other income focused opportunities with 8 dividend fortresses that are turning cash flows into regular shareholder payouts.
Northern Oil and Gas Investment Narrative Recap
Northern Oil and Gas is still a cash flow story. To be comfortable as a shareholder, you need to believe its non operating model and acquisitions of long lived U.S. shale interests keep throwing off enough cash to fund both growth and returns. The new US$0.45 dividend fits that story, but does not change the core near term driver, which remains disciplined deal making and production performance.
The biggest swing factor right now is how well Northern Oil and Gas manages commodity price volatility and rising costs while staying selective on M&A. The key risk is that acquisition heavy growth and higher leverage collide with weaker prices, which could pressure coverage of both interest and dividends.
The fresh US$0.45 per share dividend declaration ties directly into that risk reward balance. You are effectively being asked to trust that future production and cash flows from acquired assets support a payout that analysts already flag as not well covered by current earnings or free cash flow.
Dividend sustainability and interest coverage now sit at the center of the execution test. Northern Oil and Gas already has interest payments that are not well covered by earnings, so every incremental distribution tightens the margin for error if oil and gas prices soften or operating costs keep rising.
Northern Oil and Gas Dividend Against Long Range Expectations
Dividend income from Northern Oil and Gas only really makes sense when lined up against what analysts think the business can earn over time. Cash coming out to you today depends on cash coming into the company tomorrow, so the forecast revenue growth, profitability and share count all feed directly into how secure that US$0.45 per share payout feels.
Analysts currently expect Northern Oil and Gas to lift revenue by 8.0% a year over the next three years while turning a loss into a profit over the longer term. The projections assume net margins move from a loss position of 32.4% today to a positive 19.4% in three years. This would give the company more room to handle interest and dividends out of operating performance rather than balance sheet flexibility.
On earnings, the consensus view points to a move from a current loss of US$623.1 million to positive earnings of US$470.7 million by 2029, equal to earnings per share of US$4.37. That is an earnings swing of about US$1.1b from loss to profit, and it underlines how much of the dividend story hinges on a multi year improvement in profitability rather than on where the business is today.
Those same estimates also assume total shares outstanding increase by 7.0% a year over the next three years. As the share count rises, each individual share needs more underlying cash generation to keep its dividend intact, so any shortfall in future earnings growth or free cash flow would matter more for distribution capacity.
On the valuation side, analysts frame their price targets around Northern Oil and Gas generating US$2.4b of revenue and US$470.7 million of earnings by 2029. In that scenario, the stock would need to trade on a P/E of 10.6x, which they note is below the current P/E multiple for the broader US oil and gas industry at 13.9x.
Those same analyst models are being discounted back using rates in the 7.77% to 7.8% range. That discounting math does not change the dividend you receive in cash terms, but it does shape whether the current valuation is seen as leaving room for future return on top of that US$0.45 payout.
Northern Oil and Gas' narrative projects US$2.4b revenue and US$470.7 million earnings by 2029. This requires 8.0% yearly revenue growth and an earnings increase of about US$1.1b from a current loss of US$623.1 million.
Discover why Northern Oil and Gas' fair value points to a 33% potential upside from its current price, and why this gap could close quickly.
Exploring Other Perspectives
One alternative lens for Northern Oil and Gas focuses less on the new US$0.45 dividend and more on long term regulatory and decarbonization pressure. The most cautious analysts already framed lower quality revenue risk even before this payout, assuming around US$2.3b of 2029 revenue and US$622.8 million of earnings. Their forecasts may shift once this dividend is fully reflected, so investors may wish to treat today as a prompt to compare several viewpoints rather than accept a single story.
Explore 5 other Northern Oil and Gas fair value estimates, including one that suggests it could be worth just $25.00.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Northern Oil and Gas research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Northern Oil and Gas. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Northern Oil and Gas' overall financial health at a glance.
Looking For More Ideas Beyond Northern Oil and Gas?
If this dividend update has you reassessing where your capital works hardest, it can help to widen the lens beyond Northern Oil and Gas and compare other potential income and total return candidates side by side using the Simply Wall St Screener.
- If you want potential value plus quality, line up companies that screen as mispriced on fundamentals by checking out 32 high quality undervalued stocks.
- For investors who care most about resilience, stress test your watchlist against balance sheet strength with the list of solid balance sheet and fundamentals (24 results).
- If you are hunting for opportunities the market may be overlooking, scan through 16 high quality undiscovered gems and see which stories deserve a closer look.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com