
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What Just Happened With Bloom Energy (BE)?
Bloom Energy (BE) was just added to the FTSE All-World Index in US dollar terms after being removed from the Russell Small Cap Comp Growth Index, a reshuffle that can alter how large institutions trade the stock.
That reshuffle comes after a sharp run in Bloom Energy’s market value, with a 30-day share price return of 32.3% feeding into a 192.5% year-to-date gain and a very large 3-year total shareholder return of about 21x. This signals strong momentum but also heightened sensitivity to news around large AI power projects and index inclusion.
Scan how institutions are repositioning around AI infrastructure by reviewing the hand-picked 87 AI infrastructure stocks that share some of Bloom Energy’s index and data center power themes.
Bloom Energy now carries the profile of a fast-growing AI power supplier and a freshly minted global index constituent. The harder question is whether the recent share price surge already captures that story in full.
Most Popular Bloom Energy Narrative: 25% Undervalued
Bloom Energy’s most followed narrative pegs fair value at about $386 per share, compared with the recent $288.70 close, which introduces a sizeable valuation gap for investors to weigh.
The Bloom Energy story is still early days. Wall Street cannot seem to comprehend that so many areas for their growth, including international markets, other market segments, and even personal or community power (where they started), are largely untapped. The main constraint on their opportunity is plain and simple ignorance. Their proven, no supply chain risk, nearly flawless all hands execution (engineering, sales, services, customer sat) are good enough to see a long, growth future. Their ability to source and execute on short order is exactly what (sorry but true…) clueless civic (and in some cases corporate) officials need in order to survive their own ignorance. Bloom can (a) eliminate their own fear based narrative about grid overload, (b) side step their historically lame environmental agendas, and (c) deliver a time-to-market execution any bureaucrat can marvel at.
See why 37 investors see Bloom Energy as 25% undervalued.
According to JRY, the narrative values Bloom Energy’s future cash flows with a discount rate of about 9.5%, which is relatively demanding for a business tied so closely to large power and data center projects. The implied fair value of roughly $386 sits about 25% above the current trading level, so followers of this story view the recent share price spike as only part of a larger thesis rather than the end of it.
That narrative leans heavily on rapid revenue and earnings forecasts, with revenue expected to grow around 30.7% per year and earnings projected to rise about 42% per year. It also draws support from a sharp recent shift in profitability, with net profit margins currently around 7.9% compared with 1.5% a year earlier and a move into sustained profitability over the past five years.
Supporters also point to quality-of-management angles that are harder to capture in a simple multiple. Bloom Energy’s board is 90% independent with an average tenure of 7.3 years, the executive team averages 3.3 years in role, and the chief executive’s total pay of about $3.50m sits well below peers of similar size in the US market, which the data puts at roughly $14.78m. For believers in this narrative, that combination of experience and relatively restrained pay supports the case for disciplined execution on a fast growth plan.
There are clear counterweights inside the same dataset. The business has relied entirely on higher risk funding sources such as external borrowing, has recently diluted shareholders, and carries financial results affected by one off items including an $81.9m loss in the last twelve months to 30 June 2026. On top of that, analysts’ average price target of about $280 sits slightly below the current share price, and recent months have included significant insider selling alongside very volatile trading.
Investors weighing this narrative can also factor in how the market has already responded. Bloom Energy delivered a roughly 3.1x total shareholder return over the past year and about 21x over three years, which far exceeds both the broader US market and the US Electrical industry over the last twelve months. Those returns sit alongside a current valuation that one model views as about 19.4% below future cash flow value, but that same dataset also flags the stock as expensive on ratios like P/S when compared with peers.
In practical terms, the widely followed story in the community is that Bloom Energy is a high growth AI power supplier with improving profitability and a long pipeline of potential demand, but with funding structure, volatility and earnings quality all worth close attention. Readers who treat narratives as one input among many can use these numbers as a starting point rather than an end state.
Result: Fair Value of $386 (UNDERVALUED)
Still, Bloom Energy’s reliance on higher risk funding and recent shareholder dilution mean that any setback in large power or data center projects could quickly challenge this bullish narrative.
Find out about the key risks to this Bloom Energy narrative.
Another View On Bloom Energy’s Valuation
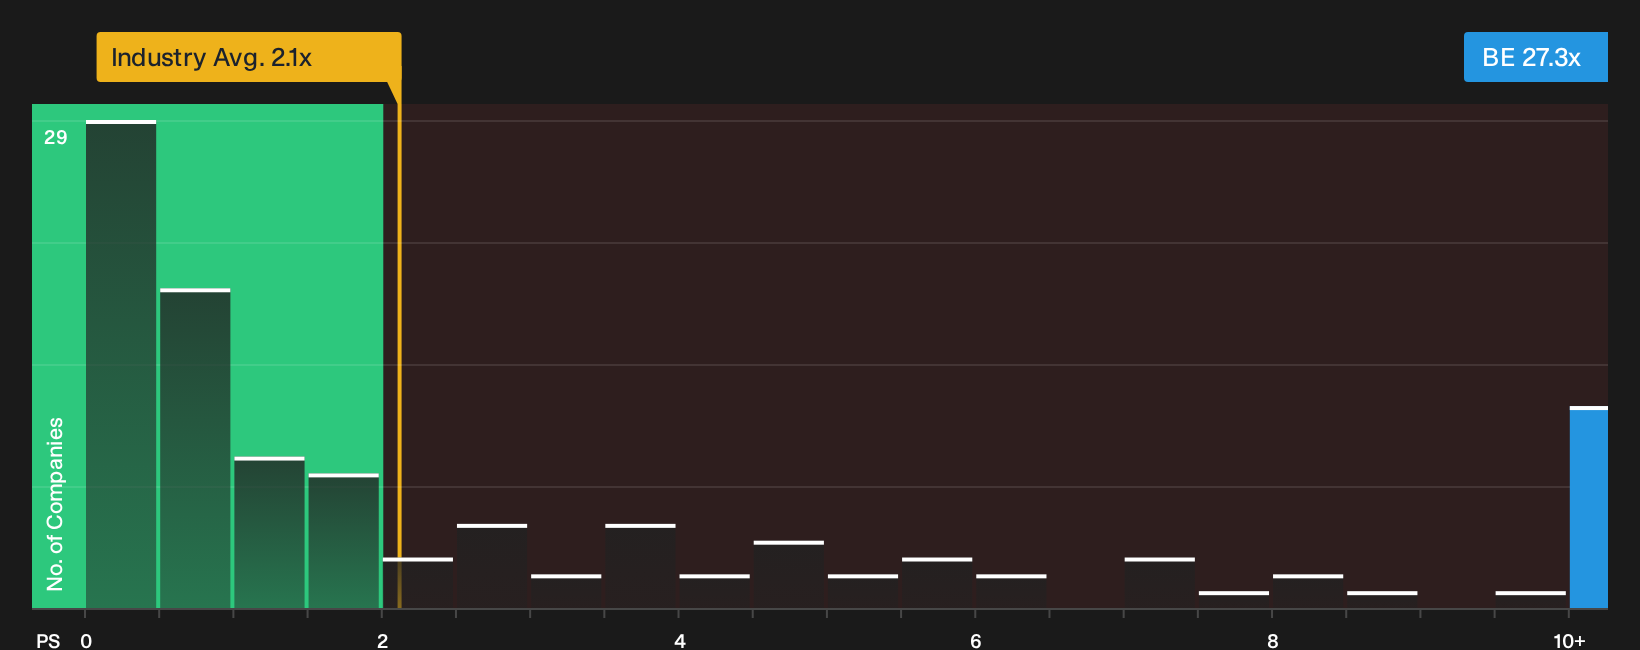
The story looks very different when you switch to simple sales-based pricing. Bloom Energy trades on a P/S of 27.3x, while the US Electrical industry sits at 2.1x and close peers average 11.8x. The fair ratio is 16.4x, which hints at considerable valuation risk if sentiment cools.
That kind of gap means even strong execution might not protect you from sharp swings if investors rotate toward companies priced nearer that fair ratio. The question is whether you see Bloom Energy as special enough to justify staying this far ahead of both its industry and its own fair ratio.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the data, with both risk and upside in play, mean you should move quickly, review the details yourself, and then weigh the 3 key rewards and 4 important warning signs.
Looking for more investment ideas beyond Bloom Energy?
If Bloom Energy has sharpened your interest in AI power and high growth stories, it makes sense to widen your watchlist before the next big move surfaces.
- Target potential mispricings across the market and spot stronger risk reward setups by reviewing the 32 high quality undervalued stocks.
- Prioritise resilience by focusing on companies with sturdy finances and dependable balance sheets through the list of solid balance sheet and fundamentals (24 results).
- Hunt for under-the-radar opportunities that others might be ignoring by scanning the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com