
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
China Communications Construction (SEHK:1800) Following Its Slide Looks Cheap On 4x P E
China Communications Construction (SEHK:1800) has drawn fresh attention after its recent share performance, with the stock down about 9% over the past month and roughly 9% over the past 3 months.
For context, China Communications Construction’s share price return is down 34.22% year-to-date, while the 1-year total shareholder return has declined 30.24%. However, the 3-year and 5-year total shareholder returns of 6.72% and 7.83% suggest longer-term holders have seen modest gains, and that recent momentum has been fading as investors reassess both growth prospects and risk around the stock.
Compare China Communications Construction’s recent pullback with other infrastructure heavyweights and see which ones are showing stronger momentum by screening for 40 power grid technology and infrastructure stocks in one place.
China Communications Construction looks like a substantial infrastructure operator on paper, yet after this sharp share price slide the real issue is simpler. Are you paying a fair price for that business today?
Price-to-Earnings of 4x: Is It Justified For China Communications Construction?
On simple earnings terms, China Communications Construction trades on a P/E of 4x, which is low relative to peers and sets up a valuation gap for investors to weigh against the recent share price slide to around HK$3.36.
The P/E ratio compares the current share price with the last twelve months of earnings per share. For a heavy infrastructure contractor like China Communications Construction, this yardstick often reflects how the market is pricing future profitability and project risk, since cash flows can be tied to long project cycles and government related contracts.
Here, the stock is described as trading at good value versus the Hong Kong Construction sector average P/E of 12.9x and also against a peer group on 6.1x. That is a steep discount. Relative to an estimated fair P/E of 8.9x, the market is assigning less than half the multiple that regression analysis suggests could be more typical for this earnings profile. That gap indicates investors are pricing in meaningful concerns around growth, returns or balance sheet pressure that sit against the company’s low P/E.
Against the industry, the comparison is stark. China Communications Construction’s 4x P/E is roughly one third of the broader Hong Kong Construction industry on 12.9x, which points to a much cheaper earnings valuation than sector peers of similar type. Versus the 8.9x fair P/E estimate, the current multiple also looks compressed, implying the market could move closer to that level if sentiment or fundamentals improve over time.
Explore the SWS fair ratio for China Communications Construction.
Result: Price-to-Earnings of 4x (UNDERVALUED)
Still, the low P/E for China Communications Construction could reflect concerns around project risk, government related exposure, or the sheer scale of its HK$94.3b market value.
Find out about the key risks to this China Communications Construction narrative.
Another View On China Communications Construction’s Valuation
The P/E picture looks cheap, yet the SWS DCF model tells a different story. On that framework, China Communications Construction at around HK$3.36 is trading above an estimated future cash flow value of HK$1.98, which screens as overvalued rather than a bargain on earnings alone.
This gap between a low 4x P/E and an SWS DCF value below the current share price raises a simple question for you: are reported profits sending a stronger signal than long term cash generation, or is the cash flow model being too harsh on this infrastructure giant?
Look into how the SWS DCF model arrives at its fair value.
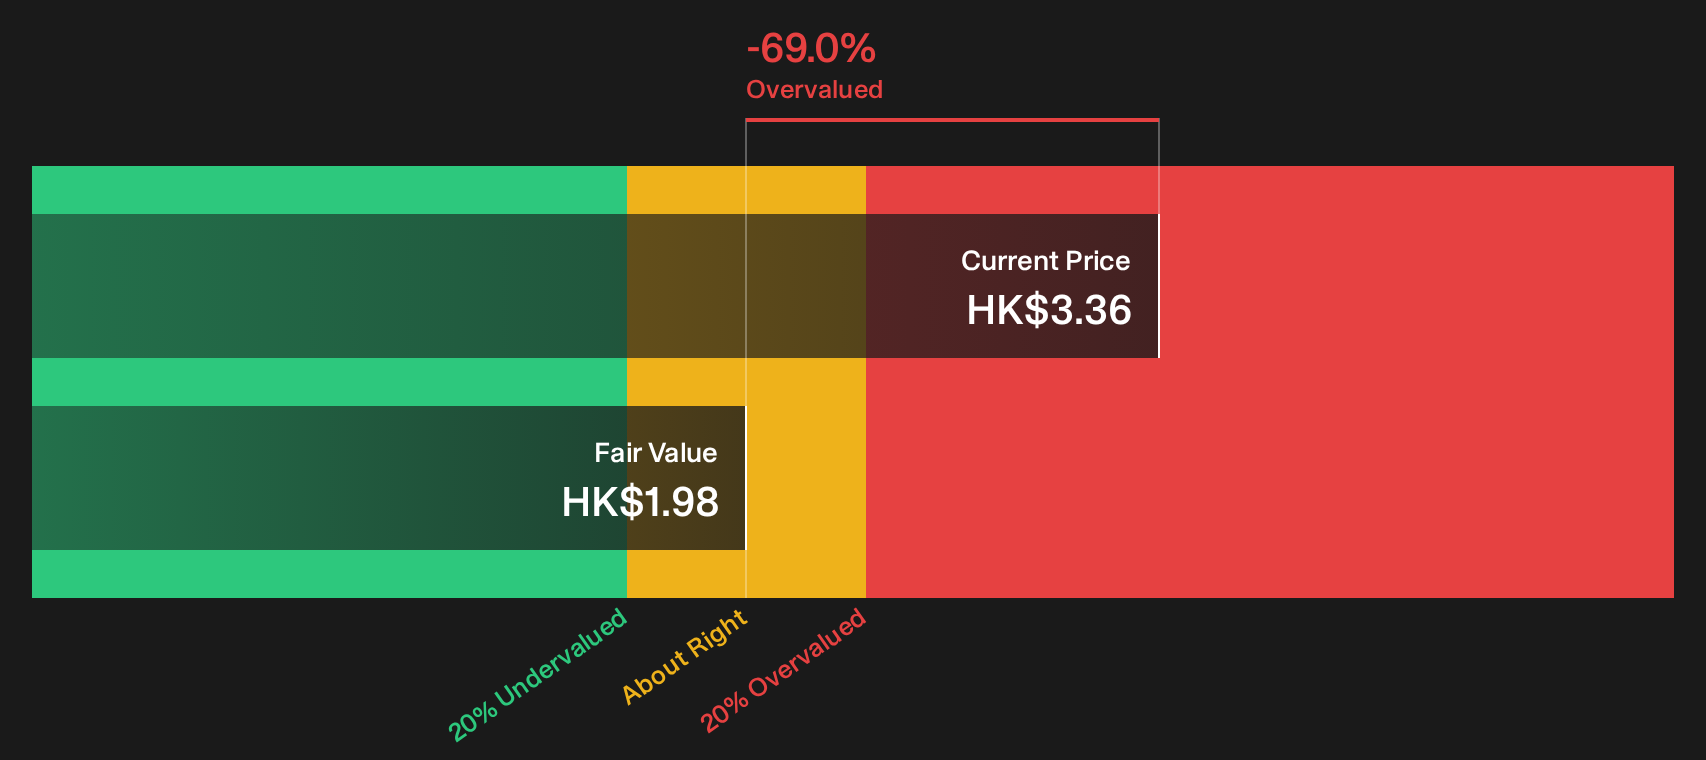
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out China Communications Construction for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 182 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of low P/E and higher DCF value feels conflicted, take it as a prompt to examine the figures yourself and make a decision. The balance of concerns and potential upside around China Communications Construction is already reflected in the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond China Communications Construction?
Do not stop your research with one infrastructure giant. A broader watchlist gives you more options if China Communications Construction is not the right fit for your portfolio today.
- Target income resilience by focusing on businesses that combine yield with staying power through the 162 dividend fortresses.
- Hunt for quality at a discount by filtering companies that pair strong fundamentals with appealing valuations through the 182 high quality undervalued stocks.
- Prioritize peace of mind by concentrating on resilient businesses that carry lower overall risk scores using the 227 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com