
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Rural 5G Deal Might Change The Case For Investing In Ericsson Stock
- Nex-Tech Wireless and Ericsson announced in September 2026 a four-year agreement to modernize roughly 85% of Nex-Tech Wireless' rural Kansas RAN, deploy a cloud-native 5G Standalone core, and introduce Ericsson Telco DataOps Platform for more advanced 5G services and revenue management.
- The deal reinforces Ericsson's role as a key vendor for rural 5G rollouts, linking its AI-capable radio systems and cloud-native core software directly to long-duration infrastructure spending by a regional carrier.
- We will now assess how Ericsson's deeper role in Nex-Tech Wireless' rural 5G Standalone build could shape the broader investment narrative.
Scan beyond Telefonaktiebolaget LM Ericsson and this Nex-Tech Wireless deal to see other infrastructure players that might benefit from similar 5G buildouts by reviewing the curated 40 power grid technology and infrastructure stocks.
Telefonaktiebolaget LM Ericsson Investment Narrative Recap
To own Ericsson, you need to believe its 5G and enterprise connectivity products can turn steady, low single digit revenue growth into durable cash generation even as earnings are expected to decline 3.4% a year over the next three years. The Nex Tech Wireless deal fits that view by tying Ericsson equipment and software directly to long contract cycles.
In the short term, the key swing factor is execution in high margin software and services while keeping restructuring and compliance costs under control. The biggest risk remains pressure on pricing and volumes if operators in key markets slow spending or push harder on contract terms.
The Nex Tech Wireless agreement is a clear recent example of Ericsson leaning into 5G Standalone, cloud native core and AI capable RAN in a single package. For you as a shareholder, the operational test is whether similar multi year projects can offset softness where large emerging markets have paused spending.
Each deal that extends the installed base for Ericsson’s dual mode 5G Core and Telco DataOps tools also matters for the catalyst many investors focus on: higher quality recurring software and support revenue. The risk is that if software uptake or monetization tools underperform, the business could remain more exposed to cyclical hardware orders than investors might like.
Ericsson Forecasts and What Analysts Are Baking In
Telefonaktiebolaget LM Ericsson's consensus story from here is built on relatively flat revenue, thinner profit margins and a smaller earnings base by the end of the decade. Analysts as a group assume the business holds the top line broadly steady over the next three years while net margin steps down from 10.8% today to 8.6%.
On earnings, the starting point in the models is SEK 24.6b today and a central forecast of SEK 19.8b by 2029. That implies an earnings decline of SEK 4.8b over the period, even before considering the spread between the most optimistic forecast of SEK 26.2b and the most cautious view at SEK 14.8b. The range shows how much disagreement still exists around Ericsson's ability to convert 5G and software opportunities into consistent profit.
Telefonaktiebolaget LM Ericsson's narrative projects SEK 230.8b revenue and SEK 19.8b earnings by 2029. This implies broadly flat yearly revenue and an earnings decline of SEK 4.8b from SEK 24.6b today.
For those estimates to line up with current analyst targets, the market would need to value the stock on a P/E of 19.4x those 2029 earnings, compared with 12.9x today and slightly above the GB Communications sector on 19.3x. That kind of rerating would rest on investors accepting lower margins yet still paying more for each krona of profit, because they view Ericsson as a higher quality, more software heavy telecom vendor over time.
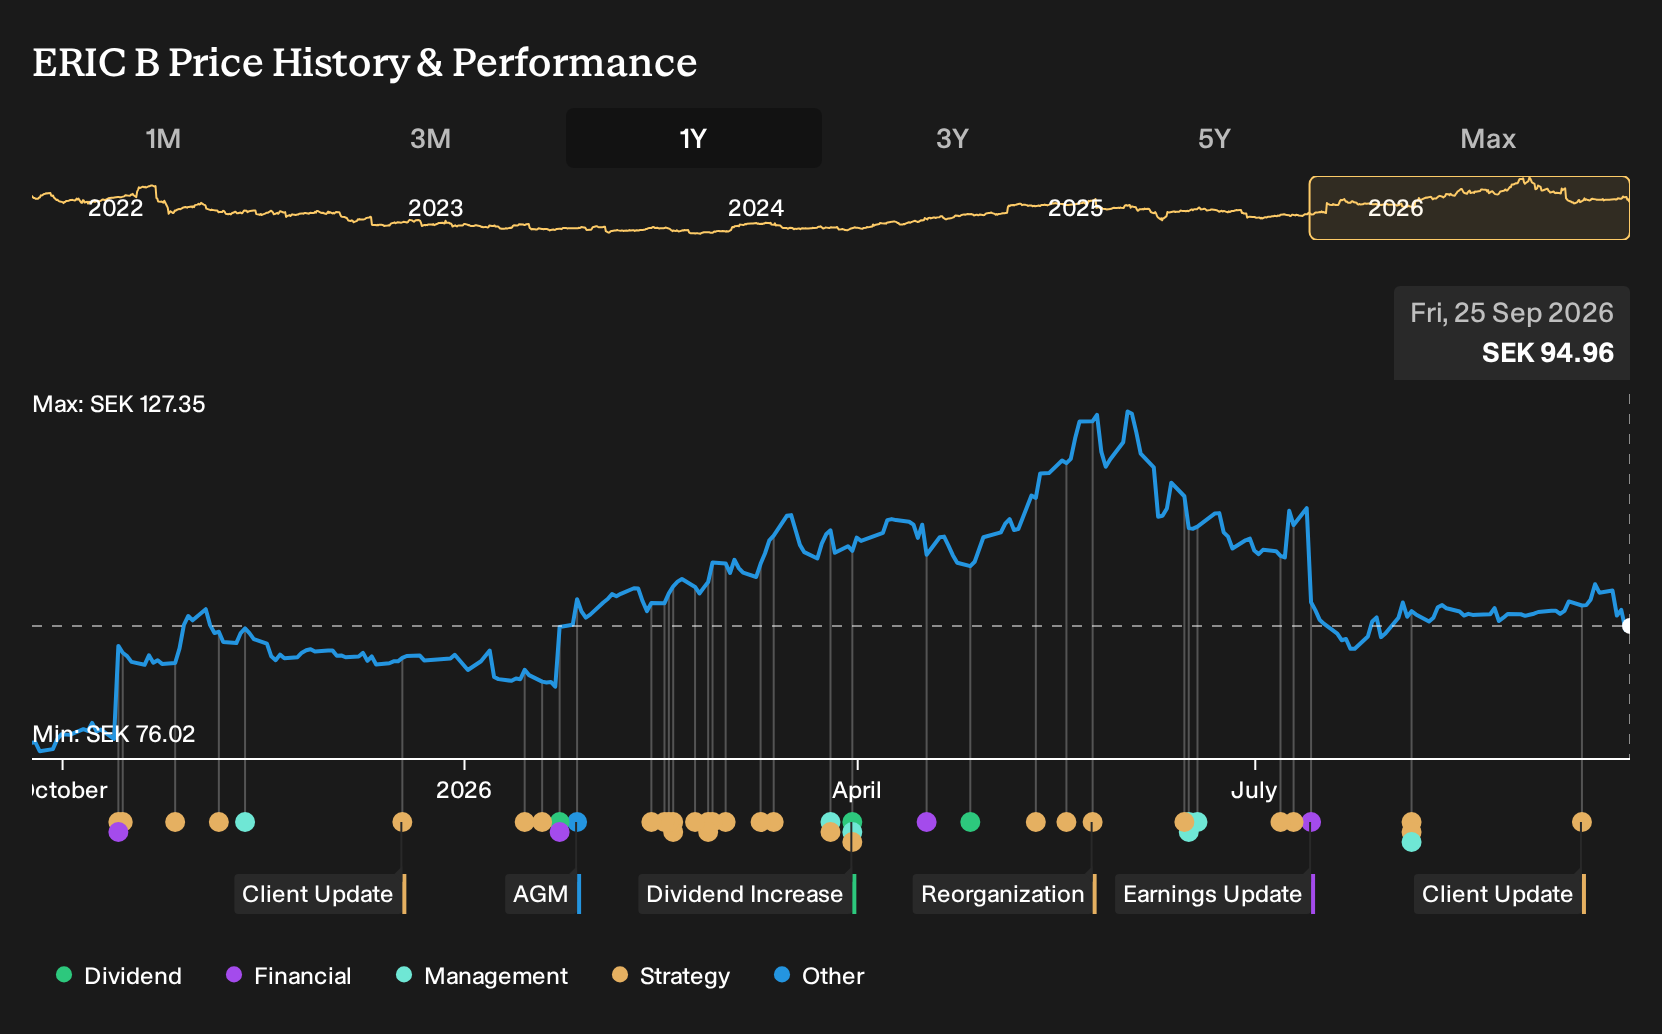
Analysts link those assumptions to a consensus price target of SEK 96.58, almost identical to the current share price of SEK 96.52. The narrow 0.1% gap suggests that on these inputs, the stock is viewed as roughly fairly priced rather than obviously cheap or expensive. For you as an investor, the real question is whether you agree that mostly flat revenue, lower margins and a higher future P/E are the right anchors for Ericsson over the next several years.
Uncover why Telefonaktiebolaget LM Ericsson's fair value indicates that it is in line with its current price.
Exploring Other Perspectives
One alternate view on Ericsson focuses on AI driven margin expansion as the real swing factor. Before this Nex-Tech Wireless deal, the most optimistic analysts were pencilling in SEK 251.6b revenue and SEK 25.9b earnings by 2029, with a P/E of 20.6x. That is far more upbeat than consensus. Use this news as a prompt to compare those scenarios and decide which story feels closer to your own view.
Explore 3 other Telefonaktiebolaget LM Ericsson fair value estimates, including one that suggests as much as 37% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Telefonaktiebolaget LM Ericsson research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Telefonaktiebolaget LM Ericsson. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Telefonaktiebolaget LM Ericsson's overall financial health at a glance.
Looking For More Investment Ideas Beyond Ericsson?
Once you have a handle on Telefonaktiebolaget LM Ericsson, it can help to compare the story with other opportunities that fit different risk and income profiles. The Simply Wall St Screener is built for that kind of side by side review so you can stress test your thesis against a broader set of listed businesses.
- If you want income to do more of the heavy lifting in your portfolio, consider high yield candidates by checking out 162 dividend fortresses that combine regular payouts with sizeable cash distributions.
- For investors who care most about resilience, focus on balance sheet strength and cash support by scanning the list of solid balance sheet and fundamentals (202 results) to see which companies might better handle tougher conditions.
- Those hunting for mispriced quality can widen their search beyond Ericsson through a curated 620 high quality undiscovered gems that highlight businesses with strong fundamentals that are not widely followed yet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com