
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Higher Payout Might Change The Case For Investing In Permian Basin Royalty Trust (PBT)
- Argent Trust Company, as trustee of Permian Basin Royalty Trust, previously declared a September 2026 cash distribution of $0.019593 per unit, payable on October 15, 2026. The increase was tied mainly to lower Trust expenses and was partly offset by softer Texas Royalty Properties oil and gas volumes and oil pricing, alongside firmer natural gas pricing.
- The higher payout highlights how Permian Basin Royalty Trust’s monthly cash flow can be heavily influenced by cost movements at the Trust level, even when underlying production and oil pricing from Texas Royalty Properties come under pressure.
- We will now look at how this expense driven distribution bump could shape the investment narrative around Permian Basin Royalty Trust.
What Is Permian Basin Royalty Trust's Investment Narrative?
To own Permian Basin Royalty Trust, you need to be comfortable owning a pure royalty vehicle that depends on production, commodity pricing and a largely fixed cost structure rather than active drilling decisions. The recent cash distribution of $0.019593 per unit, helped by lower Trust expenses despite softer Texas Royalty Properties oil and gas volumes and oil pricing, underlines how cost control can support payouts even when operating trends are mixed. That reinforces the appeal for investors who care most about monthly cash flow, but it does not remove exposure to volume or pricing swings on the underlying assets.
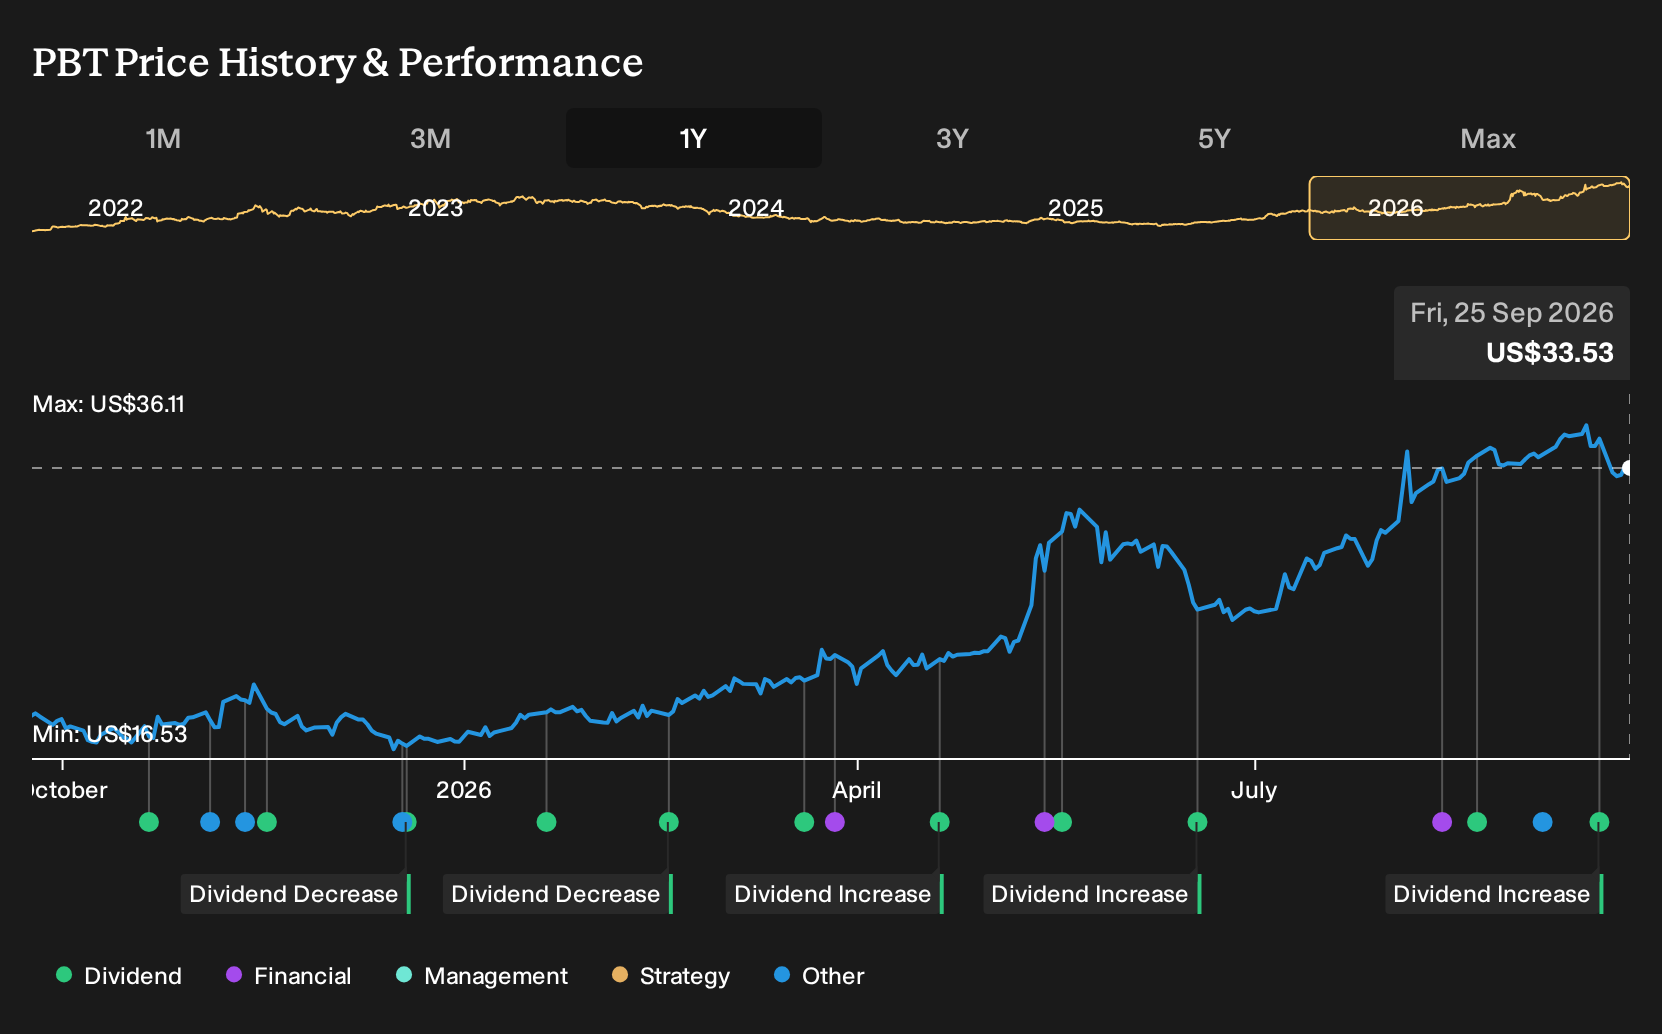
In the short term, the key swing factors remain realized oil and gas prices from the Waddell Ranch and Texas Royalty properties, plus any changes in Trust level charges that feed directly into distributable income. Earnings have declined by 2.6% per year over the past 5 years and PBT trades on a 96.4x P/E, while also sitting well above an estimated future cash flow value of US$7.98 per unit. As a result, the story is less about rapid growth and more about how long the existing royalty stream can support current expectations.
Yet there is a less comfortable part of the Permian Basin Royalty Trust story that hinges on ...
There's only one way to know the right time to buy, sell or hold Permian Basin Royalty Trust. Head to Simply Wall St's company report for the latest analysis of Permian Basin Royalty Trust's Fair Value.
The Verdict Is Yours
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Permian Basin Royalty Trust research is our analysis highlighting 1 important warning sign that could impact your investment decision.
- See our latest analysis for Permian Basin Royalty Trust. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easy to evaluate Permian Basin Royalty Trust's overall financial health at a glance.
Looking For More Investment Ideas Beyond Permian Basin Royalty Trust?
If this latest payout has sharpened your focus on income and valuation, it can help to line Permian Basin Royalty Trust up against other opportunities. You can use the Simply Wall St Screener to quickly surface stocks that match the kind of profile you are looking for and stress test your thesis before committing fresh capital.
- For investors who want potential value on their side, consider a curated set of companies trading below many investors' expectations by scanning the 32 high quality undervalued stocks.
- If capital preservation and steadier profiles matter most to you, filter for businesses with lower risk characteristics using the 30 resilient stocks with low risk scores.
- For those hunting for under followed opportunities with solid fundamentals, broaden your watchlist through the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com