
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What Nordson (NDSN)'s Product Launch And Acquisition Means For Shareholders
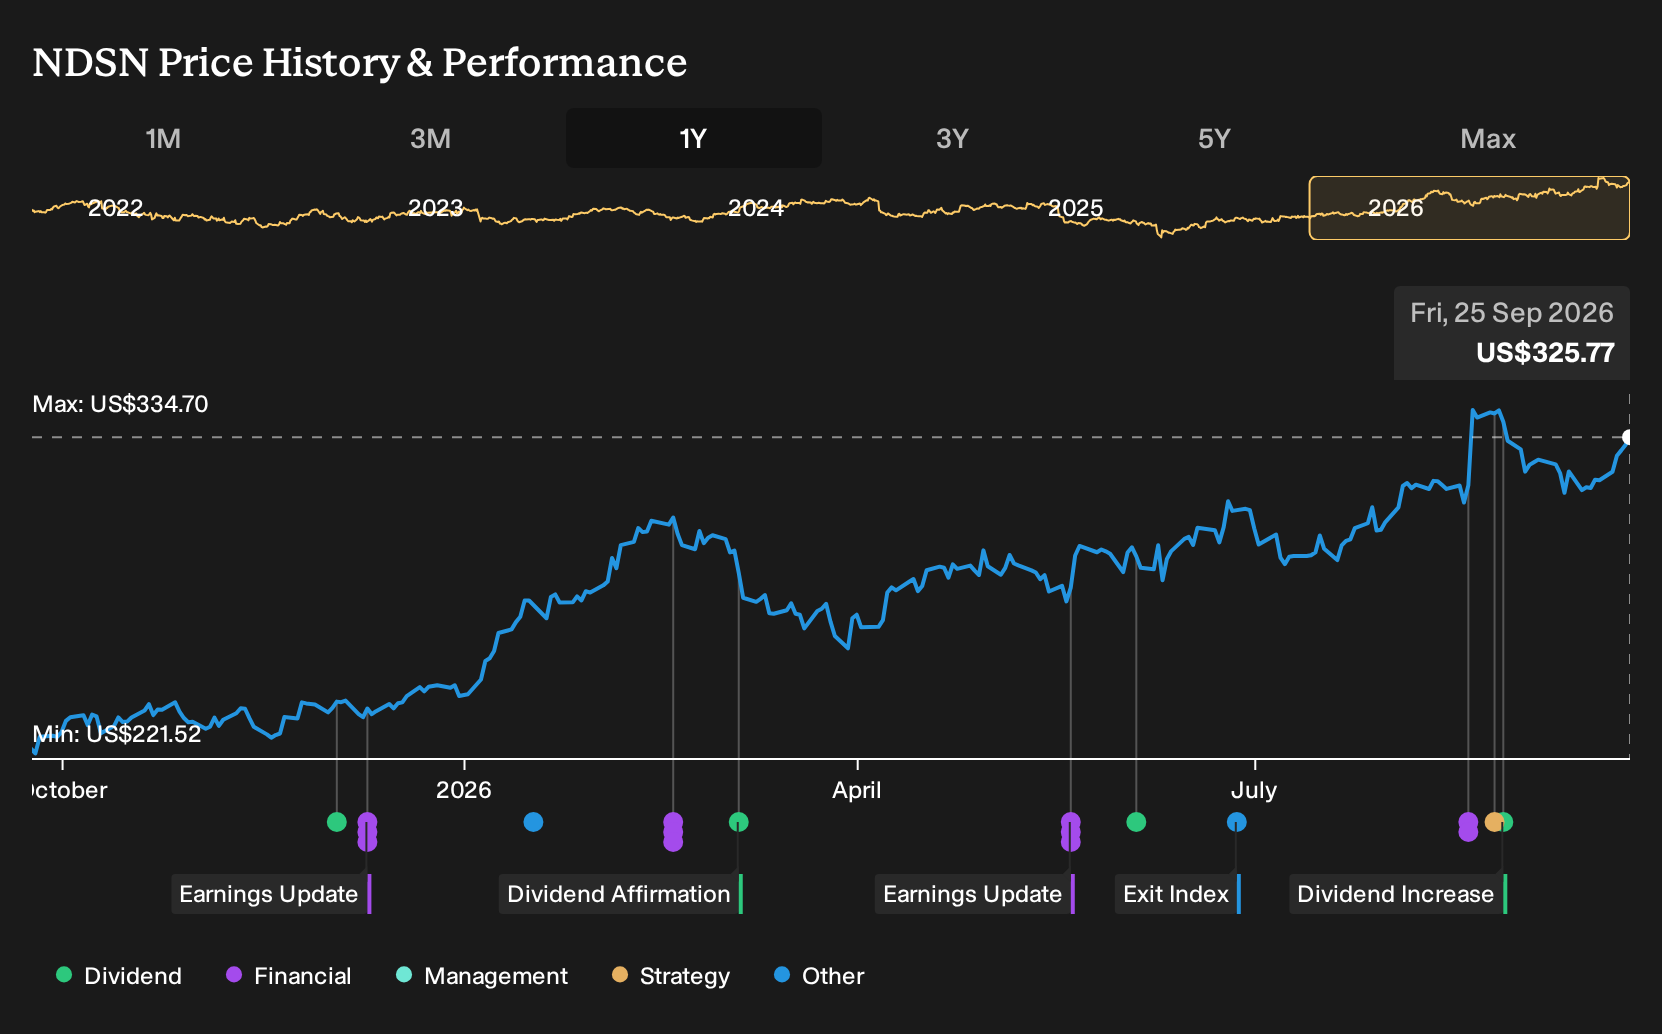
- Nordson has been reinforcing its long-term growth plan through the completed acquisition of CapstanAG in March 2026, the launch of the ASYMTEK Vantage XL for advanced semiconductor packaging, and ongoing dividend increases and share repurchases.
- The combination of precision agriculture expansion, a new high-end semiconductor dispensing platform, and consistent cash returns to shareholders highlights how Nordson is leaning into higher value, technology-driven niches while still prioritizing capital discipline.
- We will look at how Nordson's investment narrative is shaped by this mix of acquisitions, new semiconductor tools, and shareholder returns.
Scan other precision manufacturing and semiconductor suppliers riding similar themes to Nordson with our curated list of 93 robotics and automation stocks for your next round of ideas.
Nordson Investment Narrative Recap
To own Nordson, you need to be comfortable with a story built around niche industrial tools tied to semiconductor packaging, medical components, and now precision agriculture. The recent focus on advanced packaging gear and CapstanAG fits that script. The key near term swing factor remains how capital spending from chip customers and industrial buyers holds up. If ordering stays hesitant, growth in large systems could be lumpier.
The biggest operational risk still sits in end markets that recover slowly and in acquisitions that do not deliver the revenue and margin lift Nordson is paying for. Higher R&D and SG&A also need to translate into commercially successful products. Otherwise, expense levels could start to pinch profitability even as demand pockets look healthy.
The launch of the ASYMTEK Vantage XL is the clearest operational announcement tied to this thesis. It directly targets advanced semiconductor packaging work linked to AI infrastructure and automotive electrification. For shareholders, the question is how quickly this platform converts into shipped units and recurring aftermarket demand rather than staying a technical showcase.
That tool also brings concentration risk back into focus. If major chipmakers slow capital spending or shift to competing solutions, Nordson could see order timing become more erratic. Executing on service, reliability, and process performance for Vantage XL customers will be central to whether the product supports smoother cash generation or adds another cyclical layer to results.
Nordson's narrative projects US$3.5b revenue and US$726.7m earnings by 2029. This assumes 6.9% yearly revenue growth and about US$198.6m earnings increase from US$528.1m today.
Uncover why Nordson's fair value indicates Nordson is valued roughly in line with its current price.
Exploring Other Perspectives
The lowest Nordson analysts fixate on order delays and backlog risk. They assume revenue rises only 5.1% a year and still model earnings of US$774.9m by 2029 from US$555.2m, but on a lower 25.8x P/E. That is a more cautious script. Use it as a counterweight and compare several narratives before reacting to this week’s news.
Explore another Nordson fair value estimate, including one that suggests as much as 10% downside from the current price.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Nordson research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Nordson. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Nordson's overall financial health at a glance.
Looking For More Investment Ideas Beyond Nordson?
If the Nordson story has sharpened your thinking about quality, risk, and where you want growth to come from, you can use that same filter across the wider market with the Simply Wall St Screener.
- For investors who want mispriced quality rather than hype, start with a curated set of 32 high quality undervalued stocks that pair fundamentals with more reasonable valuations.
- If capital preservation sits high on your checklist, focus on a 30 resilient stocks with low risk scores that screens for resilient balance sheets and steadier risk profiles.
- To widen your watchlist with less crowded opportunities, scan a 16 high quality undiscovered gems that filters for strong business traits before the crowd arrives.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com