
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
New Factory Build Might Change The Case For Investing In Yamaichi Electronics (TSE:6941)
- Yamaichi Electronics Co. Ltd. has approved construction of a three story, 30,000 m² Factory 4 at its Philippine subsidiary Pricon Microelectronics, investing about ¥6.5b to expand assembly capacity for semiconductor test sockets, connectors, and related products, with operations planned to begin in the second half of fiscal 2028.
- The project concentrates production growth in the Philippines while pushing for higher automation, greater in house component output, and on site solar power, which tightens cost control and supply resilience across semiconductors, automotive, AI server communications, and industrial equipment demand streams.
- Attention now turns to how Yamaichi Electronics' investment narrative absorbs this sizeable Philippine factory build, especially the automation led capacity expansion.
What Is Yamaichi ElectronicsLtd's Investment Narrative?
To stay in Yamaichi ElectronicsLtd, you need to buy into a fairly simple idea. This is a picks and shovels business for chips, connectors, and high speed transmission hardware, with earnings that have been growing and a P/E of 14.9x that sits below both peer and industry averages. The new Philippine Factory 4 fits that story cleanly. Management is leaning into capital intensive capacity, automation, and more in house production to keep quality, cost, and delivery under tighter control across semiconductors, automotive, AI server communications, and industrial equipment customers.
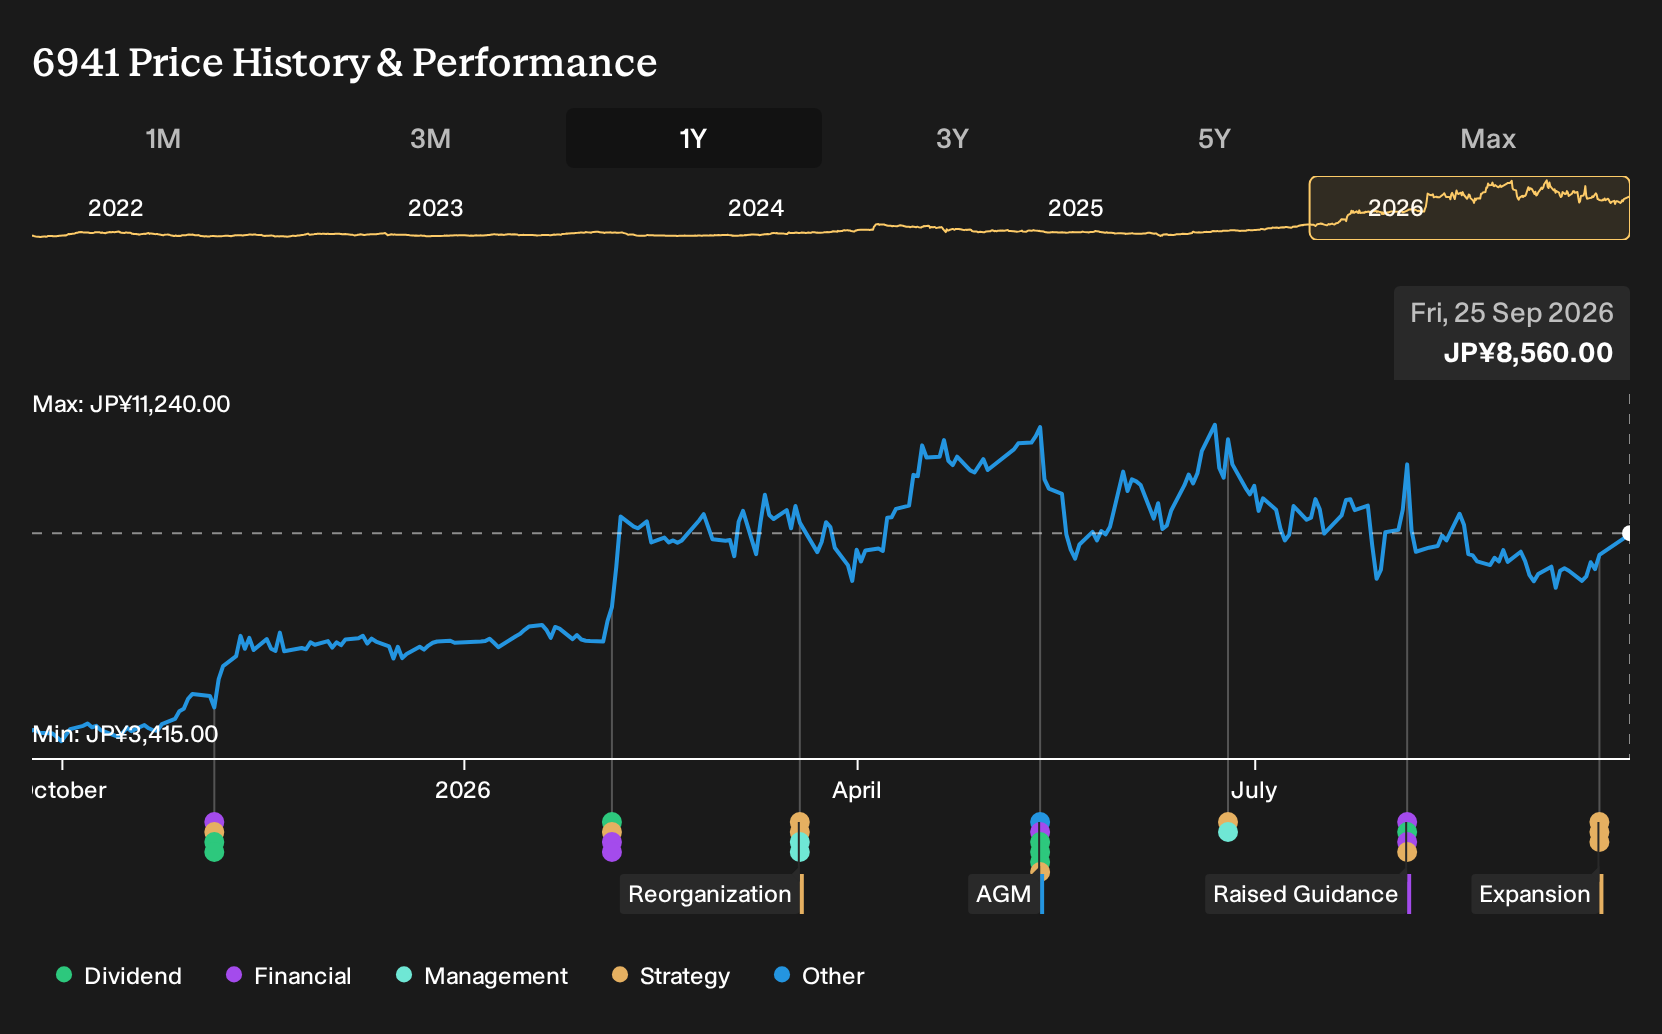
The near term question is less about demand and more about execution and return on that ¥6.5b spend. Construction running from 2027 to late 2028 means cash goes out well before the plant contributes, so you are tying the thesis to management’s ability to run big projects on time and on budget while handling any relocation expenses that sit outside the headline figure. Layer in a share price that has been volatile over the past three months and an unstable dividend record, and short term catalysts can swing quickly around sentiment to capital allocation and any updates on this build.
Even so, there is a less obvious pressure point that could matter a lot once you look closely at how this expansion is being funded and ...
There's only one way to know the right time to buy, sell or hold Yamaichi ElectronicsLtd. Head to Simply Wall St's company report for the latest analysis of Yamaichi ElectronicsLtd's Fair Value.
Reach Your Own Conclusion
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so consider your own analysis and judgment.
- A great starting point for your Yamaichi ElectronicsLtd research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Yamaichi ElectronicsLtd. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Yamaichi ElectronicsLtd's overall financial health at a glance.
Looking For More Investment Ideas Beyond Yamaichi ElectronicsLtd?
If you want to cross check Yamaichi ElectronicsLtd against other opportunities, it helps to scan a wider field of companies with different strengths. The Simply Wall St Screener lets you focus on the traits that matter most to you, whether that is income potential, balance sheet resilience, or mispriced quality.
- For investors who prize stability and want businesses with robust finances, start with a list of solid balance sheet and fundamentals (22 results) that can help you stress test your portfolio against tougher conditions.
- If you are hunting for quality at a sensible price, use a 18 high quality undervalued stocks to spot companies where fundamentals and current pricing look out of sync.
- Income focused investors who care about cash returns can scan a 14 dividend fortresses that screens for higher yielding payers with the potential to anchor long term compounding.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com