
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How New Germany Hub Will Impact Expeditors International of Washington (EXPD) Investors
- L.B. Foster Company has expanded its European distribution through a deeper partnership with Expeditors International of Washington. The company has appointed the logistics provider as its strategic distribution partner for mainland Europe and established a new hub in Germany to improve delivery, resilience, and customer service.
- The German hub concentrates Expeditors International of Washington’s logistics network in a central European location. This centralisation can support higher utilisation of its supply chain capabilities and strengthen relationships with customers that manage critical transport infrastructure.
- The next area of focus will be how this German distribution hub with L.B. Foster could reshape Expeditors International of Washington's investment narrative.
Expeditors International of Washington Investment Narrative Recap
To own Expeditors International of Washington, you need to believe the business can keep turning solid logistics capabilities into consistent fee based earnings, even while overall revenue growth expectations sit in the low single digits. The key near term swing factor remains execution on higher value services and AI enabled productivity gains, which underpin margins when freight markets soften.
The L.B. Foster Germany hub and broader critical logistics rollout give Expeditors more touchpoints with complex, time sensitive customers, which can support that services mix shift. The biggest risk stays the same. Any cooling in airfreight volumes, customs work, or disruption from ongoing restructuring could pressure earnings that many investors already view as fully valued.
The most relevant recent development for this story is the appointment of Mr. Blake Bell as Senior Vice President, Professional Services from October 1, 2026. Expeditors International of Washington is effectively putting dedicated senior leadership over a part of the portfolio that ties directly into Aircraft on Ground support, Critical Logistics Services and customs advisory work.
For catalysts, that matters. Professional services sit alongside AI tools, monitoring platforms and compliance support that can deepen relationships with customers who rely on premium response times. The operational risk is execution. Restructuring, workforce changes and higher expectations around service levels raise the bar for delivery, at a time when the stock already trades on a relatively rich P/E multiple.
What The Current Expeditors International of Washington Forecasts Assume
Expeditors International of Washington's narrative projects US$13.3b revenue and US$1.0b earnings by 2029. That scenario rests on 3.5% yearly revenue growth and an earnings increase of about US$81.2m from the current US$918.8m base.
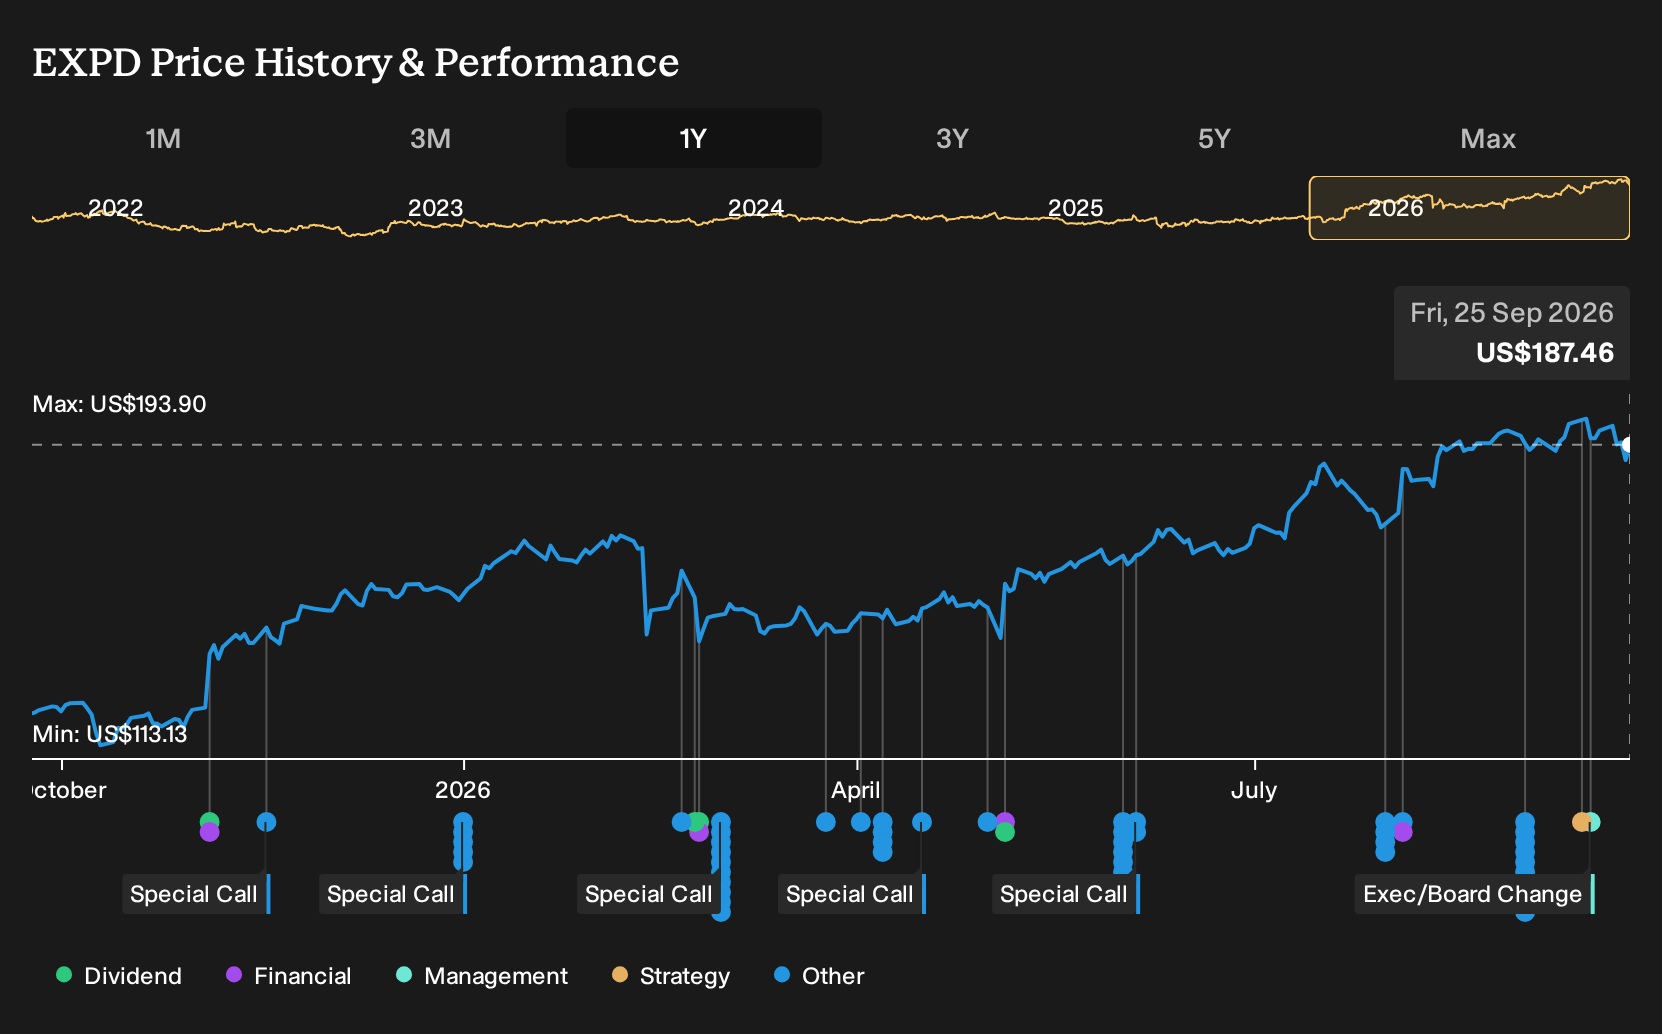
Uncover why Expeditors International of Washington's fair value indicates a 5% potential downside to its current price, creating a valuation premium that leaves little room for error.
Exploring Other Perspectives
Fair value estimates for Expeditors International of Washington from three members of the Simply Wall St Community cluster tightly between US$171.33 and US$177.71, yet those private models still diverge from the current share price. Consider this in the context of the new German hub and refreshed professional services leadership, and you can see why opinions differ sharply. Explore several of these viewpoints before deciding how much growth and execution risk you are willing to accept.
Explore 2 other Expeditors International of Washington fair value estimates, including one that suggests as much as 9% downside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- See our latest analysis for Expeditors International of Washington. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Expeditors International of Washington's overall financial health at a glance.
Looking For More Ideas Beyond Expeditors International of Washington?
If you want to stress test your view on Expeditors International of Washington, compare it with other companies that share strong balance sheets, different risk profiles, or higher income potential. The Simply Wall St Screener lets you scan across these angles quickly so you can build a watchlist that fits how you like to invest.
- For investors who care most about financial resilience and cash flow support, start with a list of solid balance sheet and fundamentals (24 results) that already meet tough balance sheet and quality standards.
- If you are hunting for quality at a discount, use the screener focused on valuation to spot 32 high quality undervalued stocks that may warrant a closer look.
- Income focused readers can zero in on dependable cash payouts by filtering for 8 dividend fortresses that combine yield with underlying fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com