
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Fifth Third Bancorp (FITB) A Bargain After Its Debt Redemption And Exchange Offer?
Fifth Third Bancorp (FITB) has been busy reshaping its liabilities. The bank is redeeming its 1.707% senior notes due 2027 and has just wrapped up a large registered exchange offer.
Recent liability moves come after an active stretch for Fifth Third Bancorp, which has mixed short term share price weakness with stronger long run returns. The stock has slipped over the past month and quarter, with the 30 day share price return down 5.44% and the 90 day share price return down 7.48%. Yet the year to date share price return is still 9.20% and the 1 year total shareholder return is 18.57%. Longer term investors have seen a very large 3 year total shareholder return of around 7x and a 5 year total shareholder return of 42.91%. Against that backdrop, the recent preferred and common dividend declarations, the naming rights deal for the Detroit Tigers’ ballpark and the senior note redemption and exchange activity help explain why sentiment has focused less on near term share price softness and more on how Fifth Third’s capital structure, funding costs and brand reach might influence risk and reward over time at a current share price of US$52.10.
Spot 30 resilient stocks with low risk scores that, like Fifth Third Bancorp, aim to balance funding strength, dividend income and share price swings.Fifth Third Bancorp now trades at a clear discount to both analyst targets and some fair value estimates, even as it tidies up its debt stack. Is that gap market prudence or mispricing that valuation math can clarify next?
Most Popular Narrative: 17% Undervalued
Fifth Third Bancorp’s most followed valuation view pegs fair value at $62.90 versus the recent $52.10 share price, which places the current discount in the spotlight and links it directly to how well the business uses deposits, technology and Comerica to drive earnings.
Expansion and densification in fast growing Southeast and Southwest markets is being extended through the Comerica footprint and an accelerated de novo program, with the recent outperformance of de novo deposit goals and sizeable Southwest consumer deposit inflows supporting potential future revenue and market share growth.
See why 22 investors see Fifth Third Bancorp as 17% undervalued.
Result: Fair Value of $62.90 (UNDERVALUED)
Still, the bullish Fifth Third Bancorp story can crack if Comerica integration glitches keep irritating customers, or if rising deposit competition squeezes funding costs harder than expected.
Find out about the key risks to this Fifth Third Bancorp narrative.
Another View: Fifth Third Bancorp Through The P/E Lens
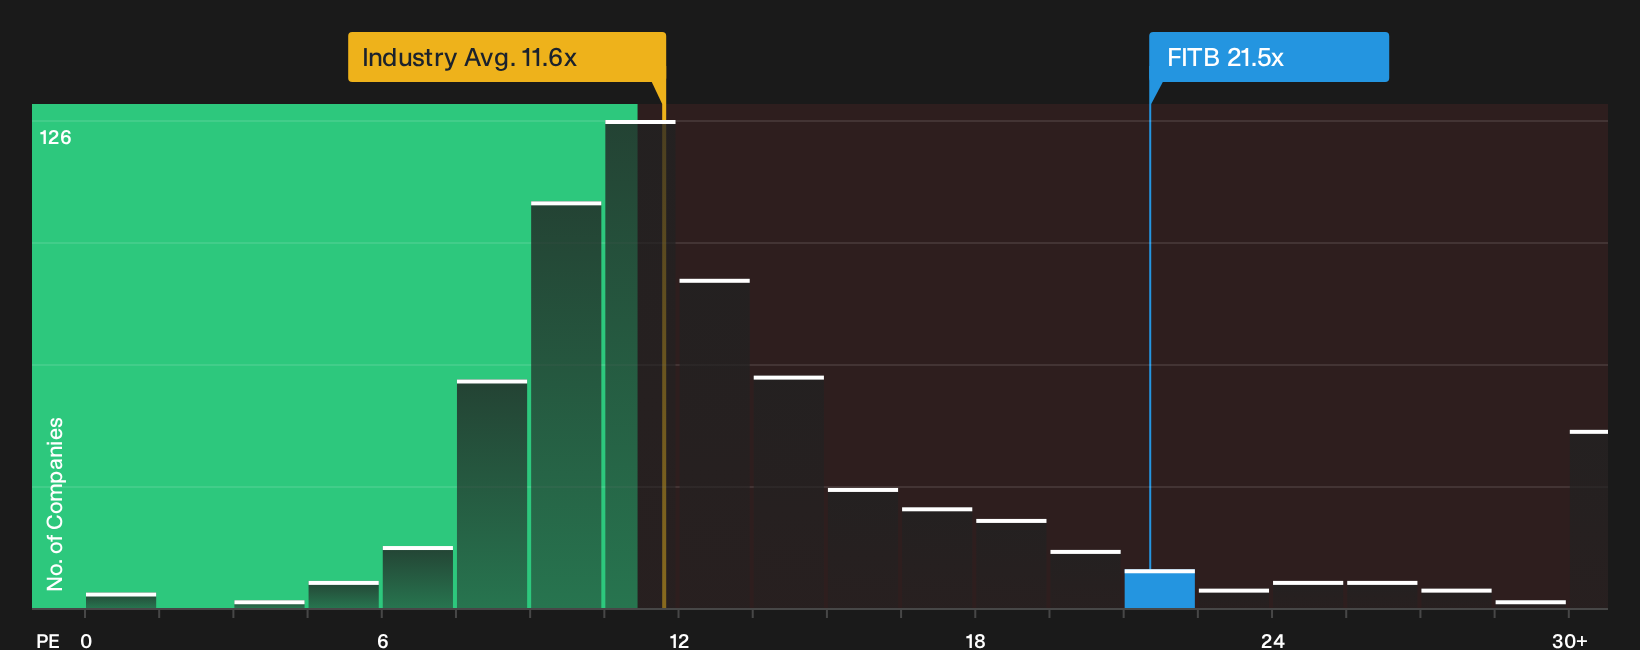
The story shifts when you swap fair value models for a simple earnings multiple. Fifth Third Bancorp trades on a P/E of 21.5x, while the estimated fair ratio is 18x and peers sit closer to 12.5x. That richer tag can signal quality or just valuation risk. Which side do you think it reflects?
See what the numbers say about this price in more detail with See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of risks and rewards around Fifth Third Bancorp leaves you undecided, review the details yourself and weigh both sides using the 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Fifth Third Bancorp?
If Fifth Third Bancorp has sharpened your focus on valuation and risk, broaden your watchlist now so you do not miss the next opportunity hiding in plain sight.
- Target resilient payers that prioritize income stability by checking companies we group as 8 dividend fortresses.
- Zero in on potential value opportunities by scanning our curated set of 32 high quality undervalued stocks.
- Prioritize capital preservation by reviewing a list of solid balance sheet and fundamentals (24 results) that can better handle shocks and funding pressure.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com