
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
IQVIA Holdings (IQV) Looks Fairly Valued As AI And Data Momentum Builds
IQVIA Holdings (IQV) has been drawing attention after recent trading left the shares at US$270.37, with the move coming alongside steady reported annual revenue of US$16.98b and net income of US$1.38b.
The short term picture for IQVIA Holdings has been mixed, with the share price slipping 1.69% on the day even after a 3.39% gain over the past month and a 41.45% share price return across 90 days that points to strong momentum. Over a longer horizon, investors who held through recent swings have seen a 50.57% total shareholder return over the past year and a 37.42% total shareholder return over three years. The 11.93% total shareholder return across five years indicates that most of the payoff has arrived more recently as sentiment around the stock has shifted.
Scan for other IQVIA Holdings style momentum stories in healthcare and data by reviewing the 38 healthcare AI stocks that have been hand picked for strong participation in this theme.
IQVIA Holdings now trades at a discount to both analyst targets and estimated fair value after a sharp rise in the share price. Is that a cautious market misread, or a clear signal to treat the valuation carefully?
Most Popular Narrative: 2% Undervalued
IQVIA Holdings closed at $270.37 against a widely followed fair value estimate of about $275. This leaves a small valuation gap that hinges on how persistent its AI and data strengths prove to be.
Accelerated adoption of AI-driven analytics and data solutions supported by strong client demand and high-profile industry partnerships like NVIDIA positions IQVIA for improved operational efficiency, faster project execution, and differentiation, which should support future revenue growth and eventual margin expansion as AI capabilities scale.
See why 19 investors see IQVIA Holdings as 2% undervalued.
Result: Fair Value of $275 (UNDERVALUED)
Still, the IQVIA Holdings story can be knocked off course if CRO pricing remains under pressure or if high leverage starts to restrict future investment flexibility.
Find out about the key risks to this IQVIA Holdings narrative.
Another View on IQVIA Holdings Valuation
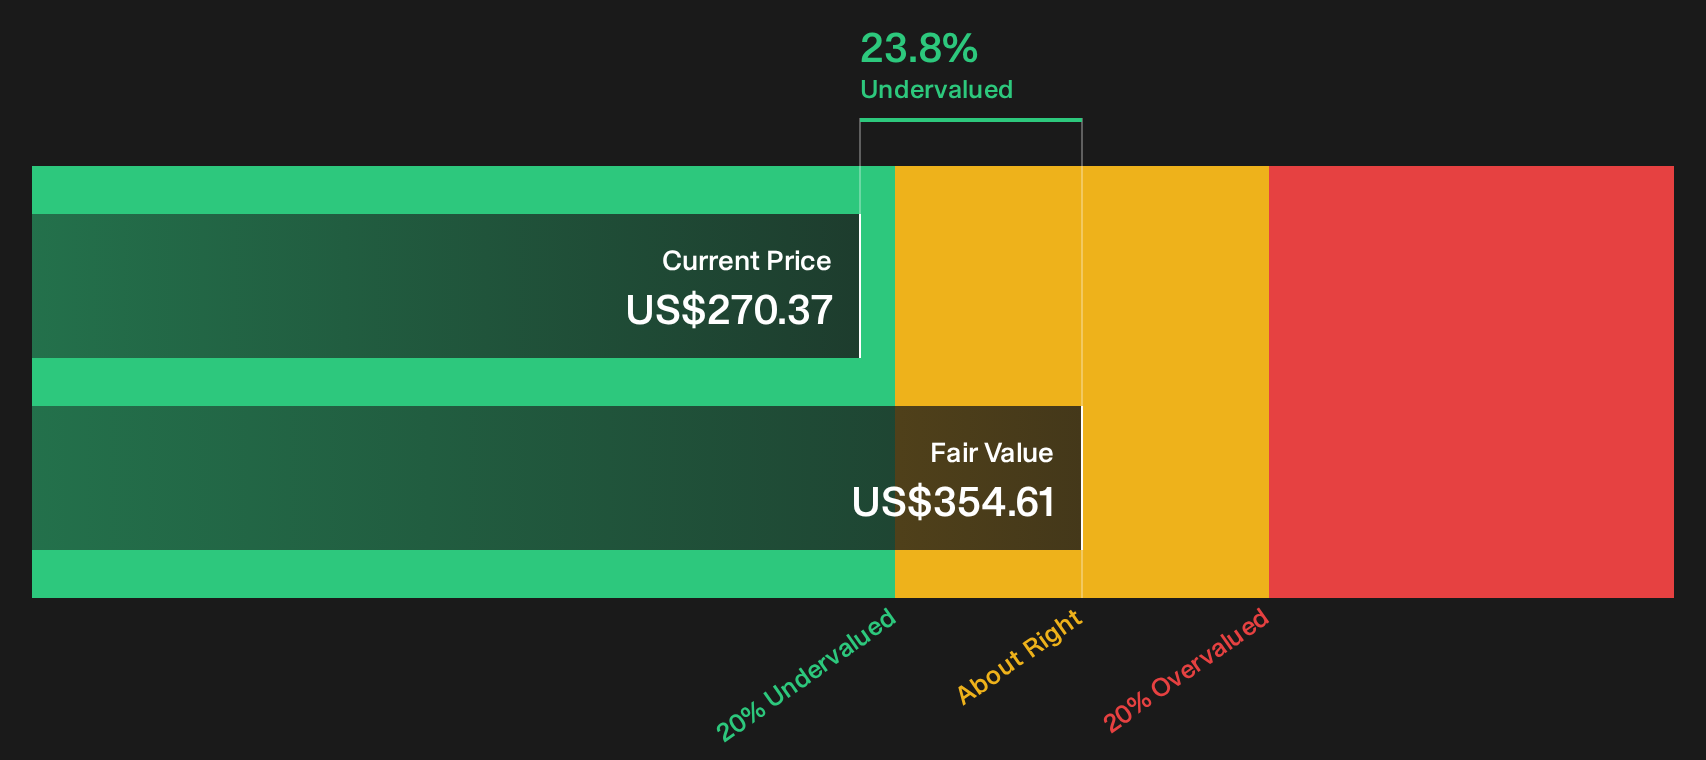
IQVIA Holdings appears inexpensive on the SWS DCF model, which estimates a future cash flow value of about $354.61 a share compared with the current $270.37 price. That indicates a relatively wide gap versus the narrower analyst fair value estimate of around $275. The question is which signal should carry more weight in your own assessment.
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals on IQVIA Holdings valuation and sentiment are clear, so move quickly, pressure test the numbers yourself, then weigh up the 3 key rewards and 2 important warning signs.
Looking for more IQVIA-style investment ideas?
If IQVIA Holdings has sharpened your appetite for focused opportunities, do not stop here. Broaden your watchlist and keep fresh candidates on your radar.
- Target potential mispricings by scanning the 32 high quality undervalued stocks that combine solid fundamentals with prices that may not fully reflect their underlying strength.
- Build a steadier income stream by reviewing the 8 dividend fortresses that offer higher yields while still keeping an eye on balance sheet resilience.
- Reduce portfolio stress by concentrating on the 30 resilient stocks with low risk scores that score well on financial health and volatility filters.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com