
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Did Phase 3 Trial Success Just Shift Celldex Therapeutics' (CLDX) Investment Narrative?
- Celldex Therapeutics reported positive topline data from its Phase 3 EMBARQ-CSU1 and EMBARQ-CSU2 trials of barzolvolimab in chronic spontaneous urticaria, with both studies meeting the primary UAS7 endpoint and all key secondary measures, and showing a safety profile consistent with earlier Phase 2 work.
- The trials included a large population of antihistamine inadequate responders and omalizumab refractory patients, where barzolvolimab produced rapid, sustained efficacy and higher complete response rates than placebo. This underscored Celldex’s focus on difficult-to-treat CSU segments with limited treatment options.
- The next area of attention is how Celldex Therapeutics' investment narrative could shift in light of barzolvolimab’s Phase 3 results in refractory CSU.
Scan how Celldex Therapeutics' CSU readout compares with other potential breakout healthcare stories by checking our handpicked 38 healthcare AI stocks that are also targeting complex, high-need conditions.
What Is Celldex Therapeutics' Investment Narrative?
For Celldex Therapeutics, the central question is whether barzolvolimab can move from a promising clinical asset to a real product franchise in mast cell driven diseases. The Phase 3 CSU data goes straight to that issue. It reflects execution on large, global trials in a hard to treat group, but it does not yet address regulatory review, pricing, or payer behavior. This is still a business with very limited current revenue, an ongoing loss profile, and a model that leans heavily on external funding rather than cash from customers.
In the near term, the key operational catalysts now cluster around regulatory interactions, longer term safety data from the CSU program, and management’s prioritization of other indications in the barzolvolimab pipeline. Those decisions affect capital needs, particularly for a company where analysts do not expect profitability over the next three years. The Phase 3 success in CSU may reshape those funding discussions and how investors assess the current market value. Yet one issue still hangs over the Celldex Therapeutics story.
There's only one way to know the right time to buy, sell or hold Celldex Therapeutics. Head to Simply Wall St's company report for the latest analysis of Celldex Therapeutics's Fair Value.
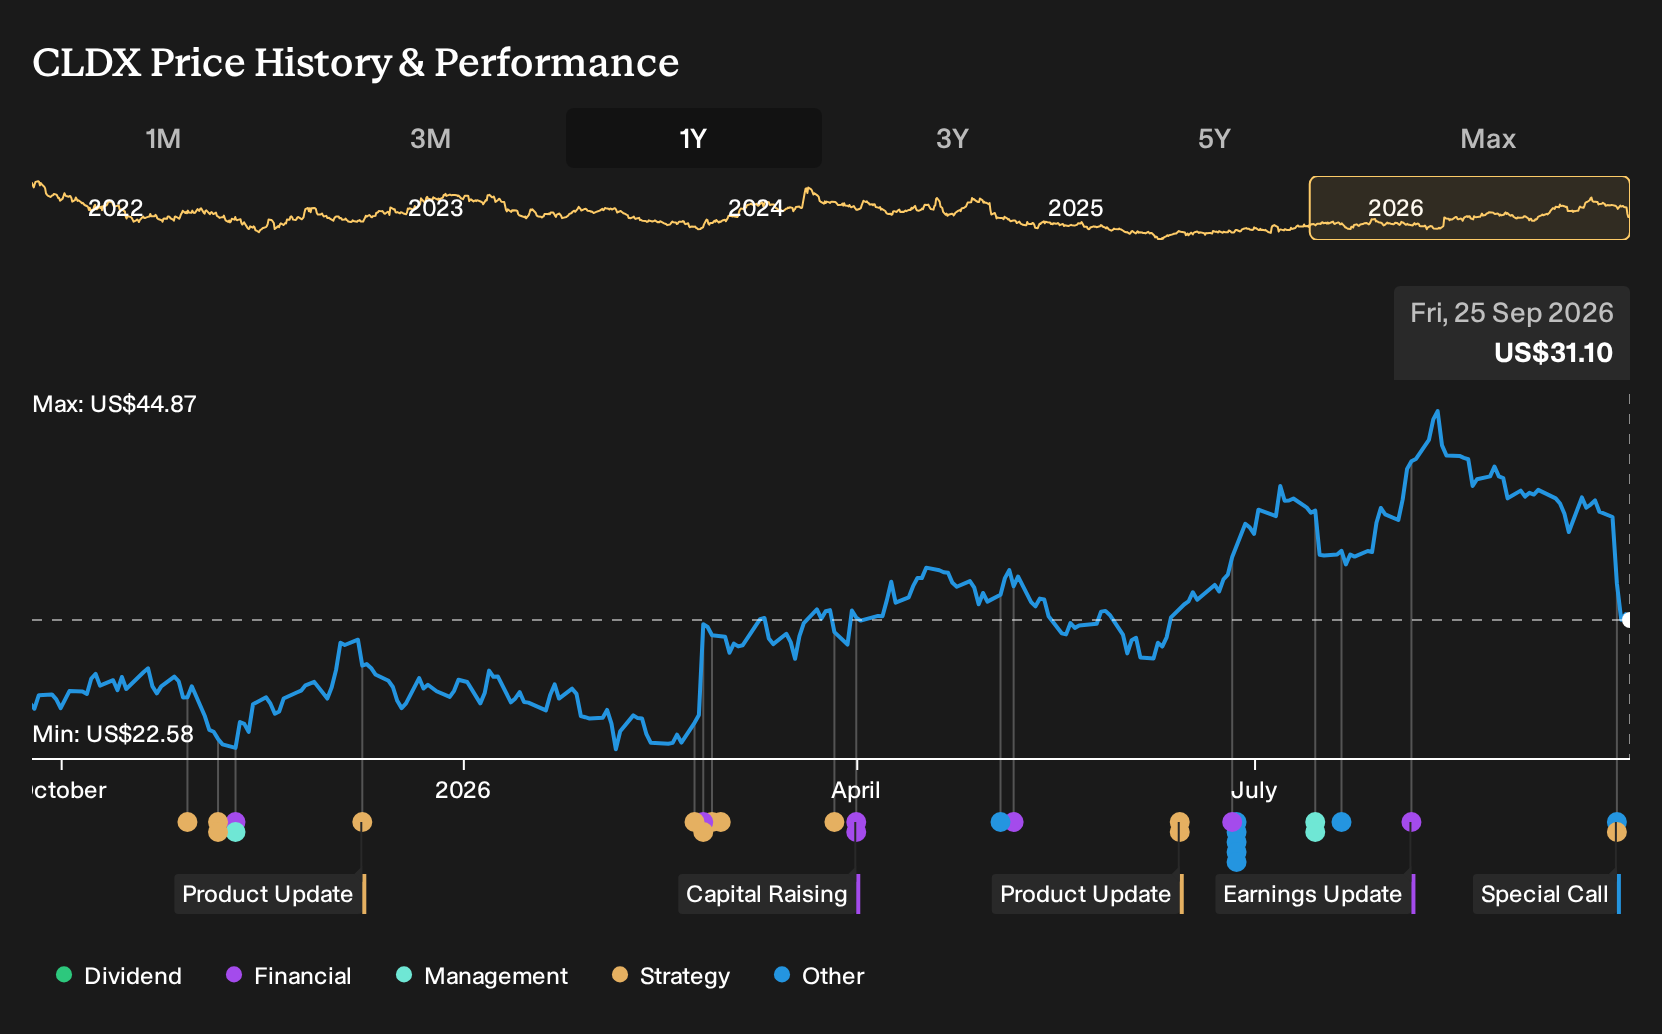
Exploring Other Perspectives
One big swing factor for Celldex Therapeutics is how far barzolvolimab can really carry a mast cell franchise. Before this CSU news, the most optimistic analysts were modeling revenue climbing very sharply, with projections reaching about US$372.4 million and earnings of US$64.2 million by 2029. That is a much more hopeful setup than consensus. Use it as a reminder that forecasts can differ widely and may shift again as new data lands.
Explore another Celldex Therapeutics fair value estimate, including one that suggests potential upside of up to 242% from the current price.
Decide For Yourself
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so you may wish to rely on your own judgment.
- A useful starting point for your Celldex Therapeutics research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Celldex Therapeutics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which can help you evaluate Celldex Therapeutics' overall financial health at a glance.
Looking For More Investment Ideas Beyond Celldex Therapeutics?
If the Celldex Therapeutics story has you thinking about what else might be under the radar, it can help to scan a broader watchlist using the Simply Wall St Screener. That way you can compare CSU exposure with very different setups in terms of balance sheet strength, valuation and income focus.
- If capital preservation matters most to you, start with a basket of companies that score well on stability and risk using our 30 resilient stocks with low risk scores.
- For investors hunting for potential mispricings, filter for businesses that combine quality fundamentals with what looks like a discounted share price through the 32 high quality undervalued stocks.
- If steady cash payouts are a priority, focus on companies that offer meaningful yields and aim for resilience in their distributions with the help of our 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com