
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Top Dividend Stocks With At Least 3% Yield
Energy prices have been swinging as the conflict around the Strait of Hormuz disrupts key shipping routes and pushes transport costs higher. Income focused investors are again paying close attention to companies that pay solid cash dividends, with yields above 3% and payouts that look both covered and steady. This article highlights three stocks from this high income screener that aim to combine regular cash flow with resilience.
The three dividend stocks you will see next are only a small sample from this high income idea. The full screen surfaced 2,266 more companies with similarly strong income stories that are not covered here. To widen your options and analyze which high yielders best fit your portfolio, head straight to the Dividend Powerhouses (3%+ Yield) screener.
Chevron (CVX)
Overview: Chevron is a large, integrated energy group that primarily explores for, produces, refines, and markets crude oil and natural gas worldwide.
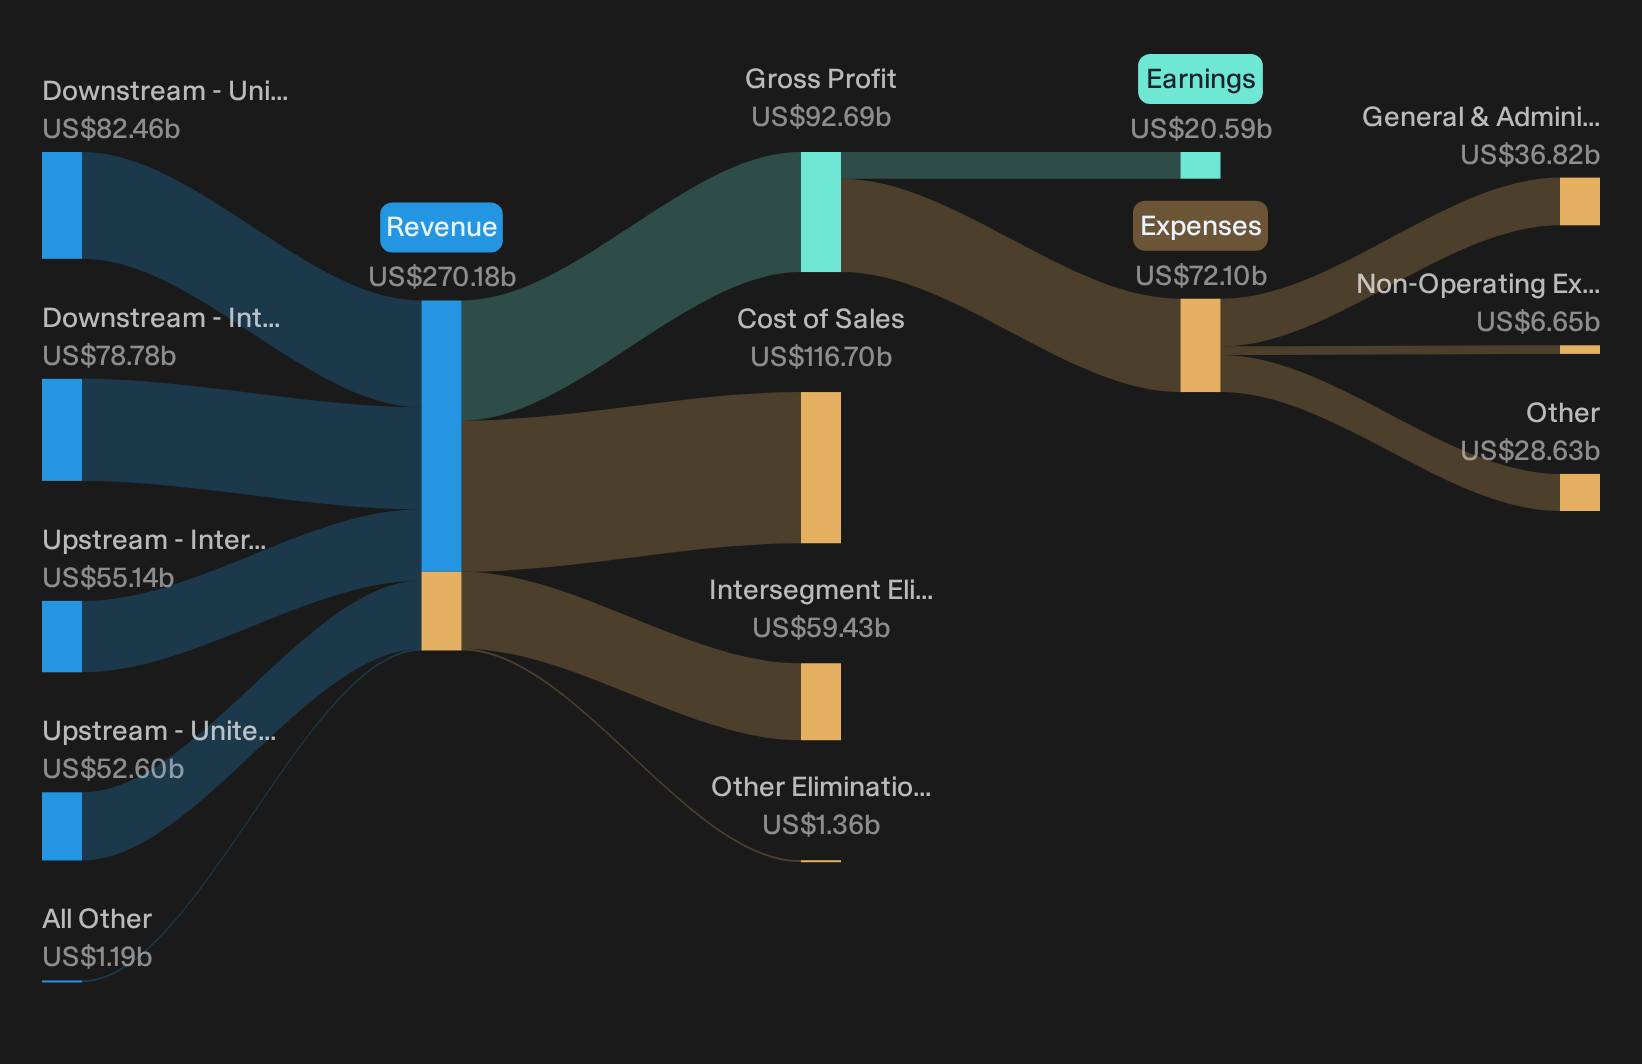
Operations: Chevron generates most of its revenue from Downstream in the United States and internationally at about US$82.5b and US$78.8b, with sizeable Upstream contributions.
Market Cap: US$401.0b
For dividend hunters, Chevron matters because its integrated oil and gas engine has long produced the kind of steady cash flows that can support a sizeable, recurring payout. This is exactly what this high yield screen is built to surface.
"Record production growth, especially in the Permian and from the Hess acquisition in areas such as Guyana and the Bakken, now sits on top of capital and drilling programs that aim to keep Permian volumes around 1 million barrels per day with lower CapEx per barrel, which supports future revenue and free cash flow."
The real test for Chevron’s dividend strength comes from how one evolving cost pressure shapes future margins and the cash available for payouts.
That margin pressure is exactly what Chevron’s full narrative for Chevron unpacks, including how capital discipline, portfolio shifts and payout priorities could be decoupling faster than headlines suggest.
NIKE (NKE)
Overview: NIKE designs and sells athletic footwear, apparel, and related gear, with its dividend primarily supported by NIKE Direct and wholesale cash flows.
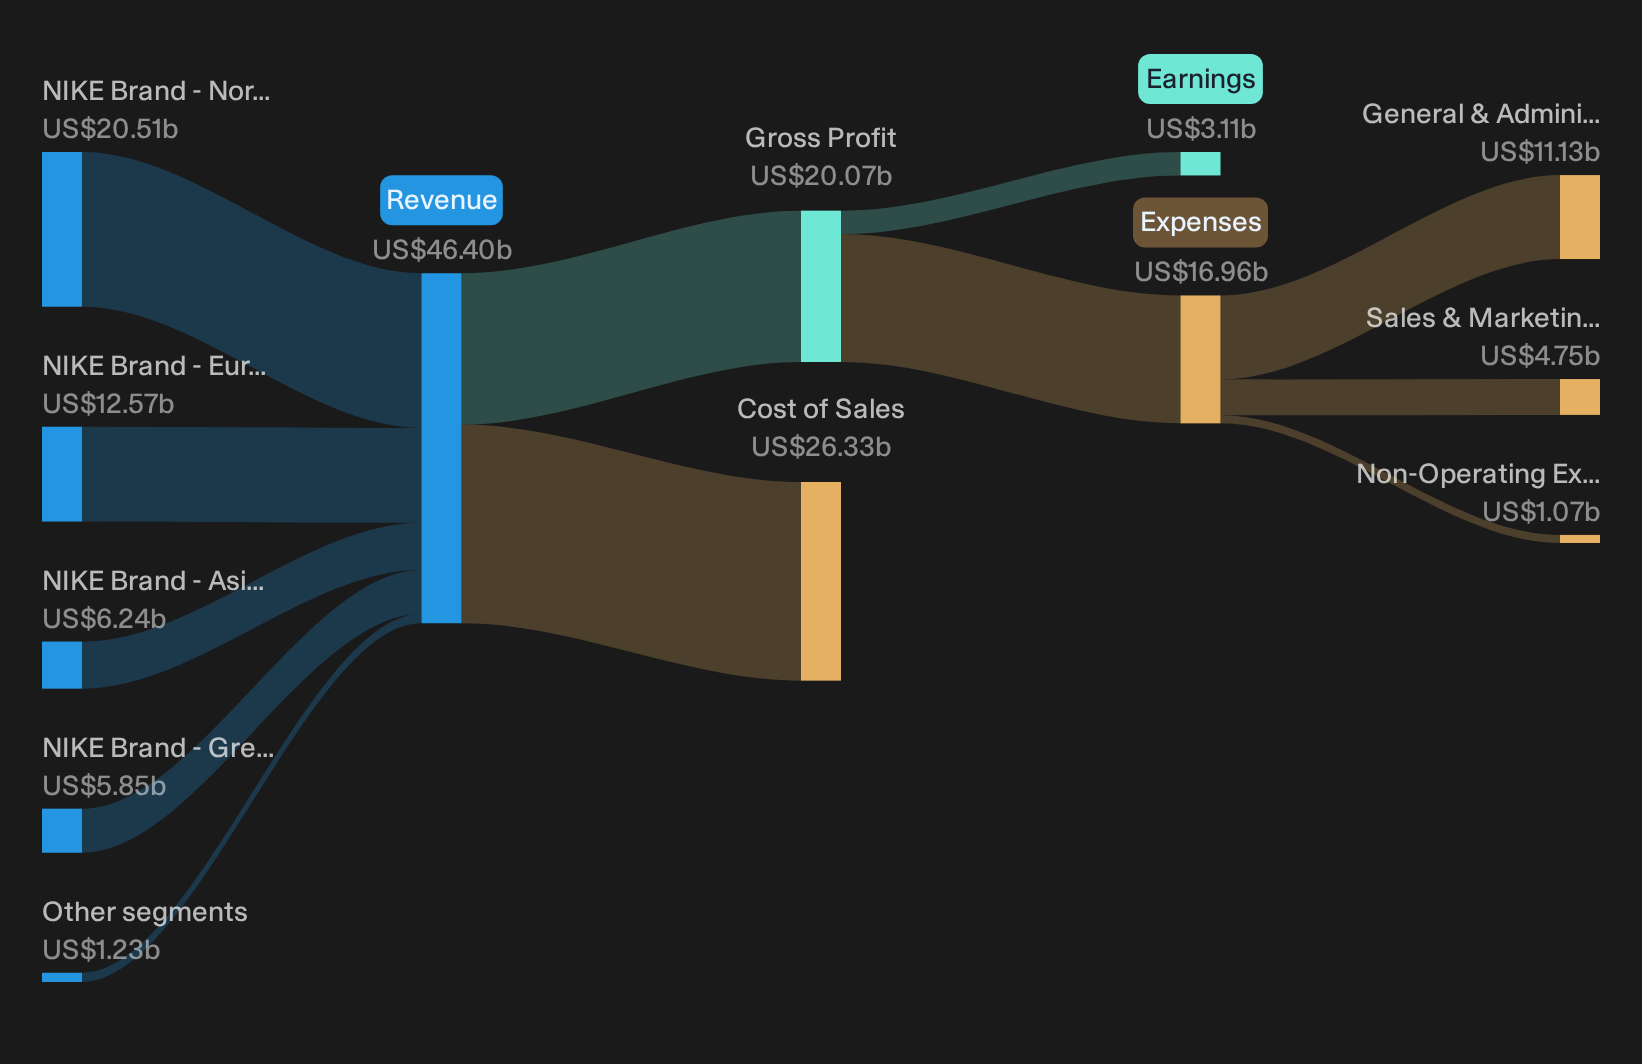
Operations: NIKE generates most of its revenue from NIKE Brand regions, led by North America at US$20.5b and EMEA at US$12.6b.
Market Cap: US$53.0b
For income seekers, NIKE offers a twist on the dividend powerhouse idea. A 3%+ yield is backed by cash flows from everyday sneakers, team kits, and digital checkouts rather than commodities or utilities.
"However, there are some risks for the company, represented by the High uncertainty rating, showing that Nike, despite having a history of success, needs to keep reinventing itself providing, as always, great products to its clients."
The real hinge for NIKE’s dividend appeal is whether one stubborn pressure on its cash engine loosens before investors lose patience.
If that pressure on NIKE’s cash engine is what you care about, the full narrative for NIKE shows how reinvention, margins and dividend ambitions could still accelerate.
Accenture (ACN)
Overview: Accenture helps large organisations modernise and run their technology and operations through long-term consulting, cloud and outsourcing services that generate recurring cash flows and support a high, covered dividend.
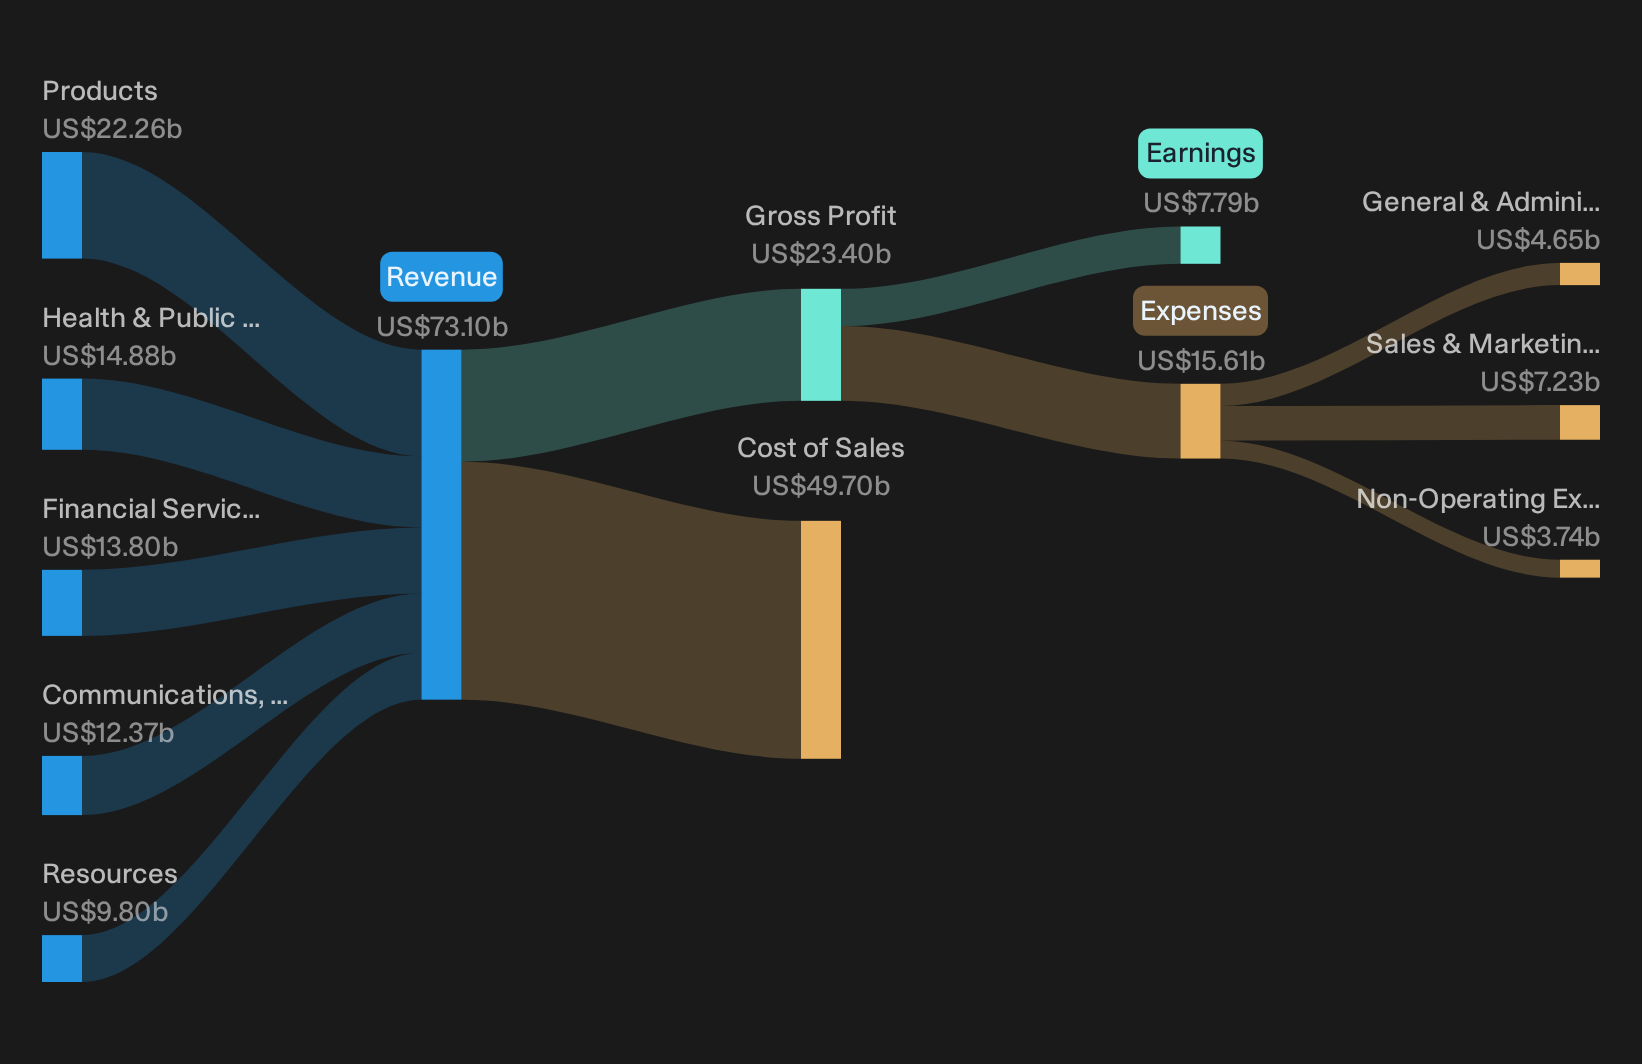
Operations: Accenture earns most revenue from Products at US$22.3b, followed by Health & Public Service, Financial Services, Communications, Media & Technology and Resources.
Market Cap: US$107.8b
Accenture matters in a dividend screen because its consulting work increasingly feeds into long-term outsourcing and managed services, which can smooth cash generation and help keep a 3%+ payout feeling more dependable across cycles.
"The market is asking whether Accenture can convert AI from a threat into a growth engine."
The answer depends on how one quiet shift in its long-term contract mix reshapes pricing power, client stickiness and dividend headroom.
That quiet contract shift is exactly what the full narrative for Accenture unpacks, revealing where Accenture’s AI work could accelerate cash generation while keeping dividend risk contained.
Seeking Alternatives Before The Crowd
Fresh income ideas can pick up momentum fast, with under the radar stocks flying once attention catches up. Scan new breakouts before information goes stale and act now.
- Spot resilient cash generators early and sift through the list of solid balance sheet and fundamentals (24 results) that keep funding dividends even when weaker balance sheets start dropping away.
- Ride potential upside from small caps tied to real-world AI demand and track where profits already matter using the 37 profitable AI stocks that aren't just burning cash while it still feels under the radar for now.
- Position ahead of the next power shift and review the 40 power grid technology and infrastructure stocks that could benefit if grid spending builds momentum faster than many investors expect.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com