
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Interim Dividend Hike Change The Bull Case For Toho Stock (TSE:9602)?
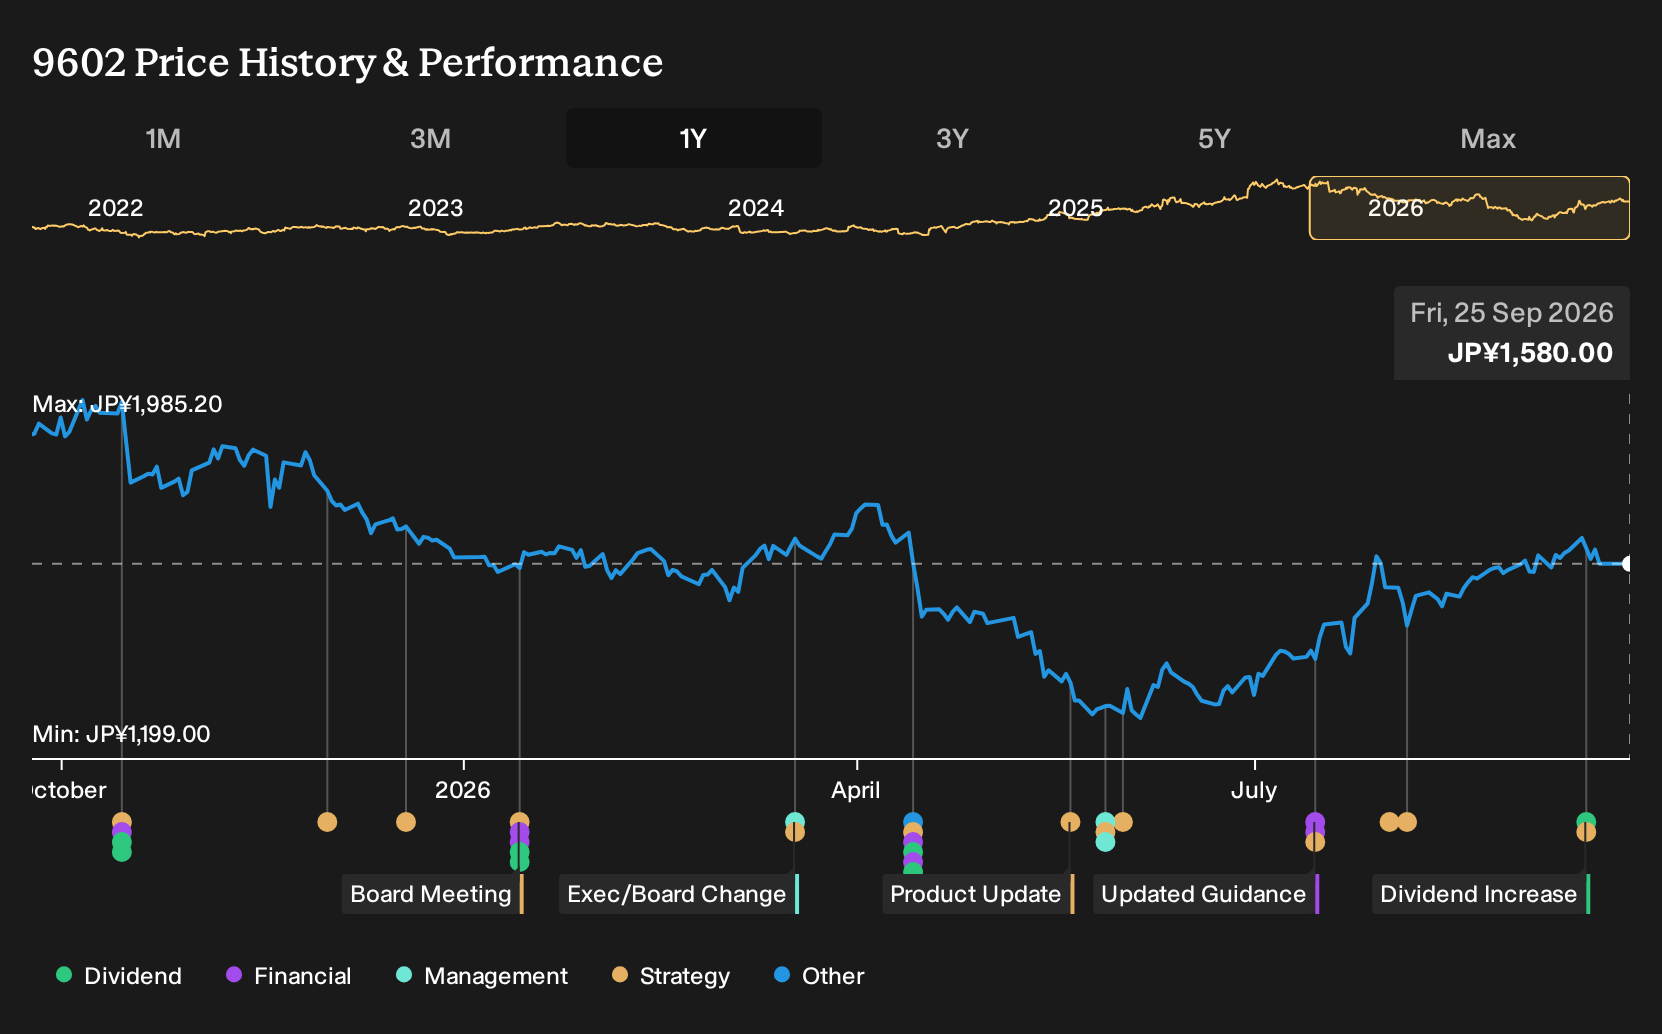
- Toho Co., Ltd. held a board meeting on September 15, 2026 and approved an interim dividend from surplus of ¥11 per share for the period ended August 31, 2026, with a total payout of ¥9,151 million, a record date of August 31, 2026 and an effective payment date of November 20, 2026.
- This higher interim dividend relative to the prior ¥8.5 per share indicates Toho's current preference for returning surplus cash directly to shareholders instead of retaining it on the balance sheet.
- The decision to raise the interim dividend also draws attention to Toho's capital allocation approach and how it may influence the broader investment narrative around the company.
Scan how Toho's dividend move compares with other companies returning cash to shareholders by reviewing our hand picked list of 14 dividend fortresses.
What Is Toho's Investment Narrative?
Toho appeals to investors who believe in a fairly steady entertainment ecosystem built on film production, IP like Godzilla, cinemas, anime and a sizable real estate arm rather than a single hit driven story. The business is generating revenue of ¥364,527.0 and net income of ¥48,399.0, with earnings growth in recent years and improving profit margins. The core question is whether that mix of content, venues and property can keep pulling in cash efficiently.
The higher interim dividend fits into that story as a signal that management is comfortable returning more surplus capital instead of hoarding liquidity for heavy new projects. In the near term, the move matters less for box office trends, anime demand or leasing conditions and more for how you view discipline around capital intensity and funding, especially given the higher P/E multiple and still modest Return on Equity.
Yet the real tension in the Toho story starts when you look at how that richer multiple interacts with...
There's only one way to know the right time to buy, sell or hold Toho. Head to Simply Wall St's company report for the latest analysis of Toho's Fair Value.
Reach Your Own Conclusion
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Toho research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Toho. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Toho's overall financial health at a glance.
Looking For More Investment Ideas Beyond Toho?
If Toho's dividend decision has you rethinking how you want income, quality and risk to fit together in your portfolio, it can help to scan a wider field of stocks that share some of the traits you care about most.
- If capital preservation sits high on your checklist, start with a group of shares that score well on stability and balance sheet strength through the 21 resilient stocks with low risk scores.
- For readers hunting for strong fundamentals that the market may not be fully pricing in, sort through a curated pool of potential bargains via the 74 high quality undiscovered gems.
- If dependable income is your priority and Toho's payout has caught your eye, compare it with companies screening for higher yields in the 14 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com