
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Should High NA EUV Orders Require Action From ASML Stock Investors?
- Recent news highlights ASML Holding's central role in advanced semiconductor equipment, with High-NA EUV systems gaining commitments from Intel, Samsung, and TSMC, alongside a long-term 12-inch EUV photomask collaboration with TSMC targeting pilot use by 2031 and wider production by 2033.
- The same set of announcements ties ASML Holding more tightly to AI infrastructure spending, as European AI-linked suppliers benefited from Anthropic's multi year US$11.6b compute deal and from customer roadmaps that increasingly rely on ASML tools to manage chip complexity and manufacturing costs.
- We will now look at how ASML Holding's push into High-NA EUV systems could reshape the company's longer term investment narrative.
Scan beyond ASML Holding and see which peers could also benefit from the AI compute buildout by checking our curated list of 87 AI infrastructure stocks.
ASML Holding Investment Narrative Recap
To own ASML Holding, you essentially need to believe that chipmakers keep pushing into more complex manufacturing and that ASML’s EUV and High-NA tools stay central to that process. The key near term swing factor is how quickly customers move High-NA from R&D into volume lines. Recent High-NA orders and AI-related demand headlines help sentiment but do not fundamentally change that pacing risk yet.
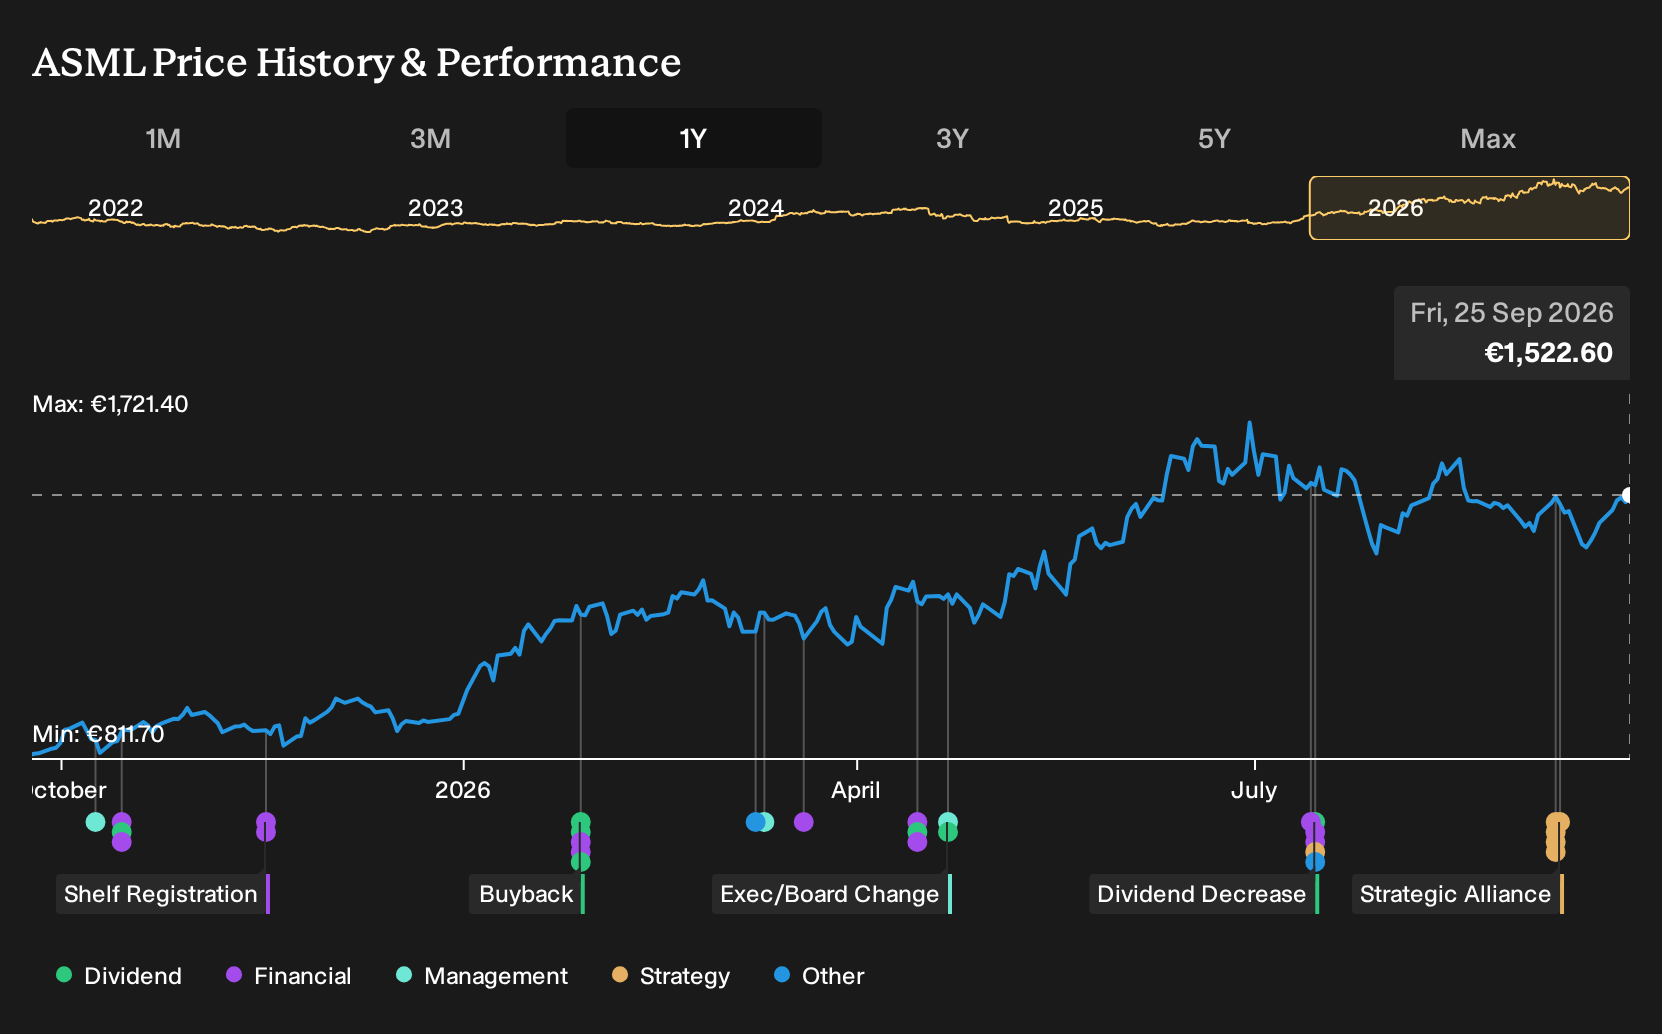
The biggest operational risk right now is still execution and timing. Tool maturity, customer fab readiness, export controls and tariff policy can all affect delivery schedules and bookings volatility. Short term share price moves have also been choppy, which can amplify any hiccups in orders or product rollout.
The most relevant recent announcement for this story is ASML Holding’s expanded High-NA EUV commitments from Intel, Samsung and TSMC, paired with the 12 inch EUV photomask roadmap with TSMC. That combination provides more concrete visibility into where High-NA sits in customer roadmaps and how it could support productivity gains over the next decade.
For catalysts, that High-NA and 12 inch mask path ties directly into AI compute buildouts and potential future demand for leading edge tools, while also concentrating execution risk. Any delay in getting these systems production ready, or any shift in geopolitical rules around advanced equipment shipments, could affect orders and installed base service revenue growth for ASML Holding.
ASML Holding's current analyst narrative points to revenues of €65.7b and earnings of €25.3b by 2029, based on a projected 23.0% yearly increase in sales and a move from €10.6b in earnings today, which implies an earnings uplift of about €14.7b over that period.
Uncover why ASML Holding's fair value indicates a 34% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One bullish twist on the ASML Holding story leans heavily on AI and service revenues. Those analysts already pencilled in revenue growth of 31.9% a year and earnings of €32.2b by 2029, compared with the €25.3b consensus view. The new High-NA and 12 inch mask news could nudge these narratives in very different directions, so it may be worth exploring both before deciding what you believe.
Explore 25 other ASML Holding fair value estimates, including one that suggests as much as 64% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your ASML Holding research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for ASML Holding. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ASML Holding's overall financial health at a glance.
Looking for more investment ideas beyond ASML Holding?
Once you have formed a view on ASML Holding, it can help to cross check that thesis against other opportunities using the Simply Wall St Screener.
- For investors hunting for potentially mispriced quality, scan our 182 high quality undervalued stocks that pair solid fundamentals with more modest valuations.
- If resilience matters most to you, focus on companies with stronger financial footing by reviewing the list of solid balance sheet and fundamentals (202 results).
- For those who want income alongside potential capital gains, zero in on reliable payers with the 162 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com