
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Strong Travel Demand Altering The Investment Case For JetBlue Stock?
- JetBlue Airways raised its third-quarter revenue per available seat mile outlook to 17% to 20% year-over-year growth, citing strong travel demand and healthy bookings. The company also updated guidance to reflect higher fuel and non fuel unit costs and lower capital expenditure, including the planned sale of an Airbus A321neo XLR.
- The combination of stronger unit revenue expectations, rising operating costs linked to weather and air traffic control issues, and a pullback in planned spending provides a clearer view of how JetBlue is balancing demand strength against operational and cost pressure in its day to day business.
- We will now see how JetBlue Airways' higher revenue forecast, driven by strong travel demand, could reshape the broader investment narrative.
Scan how JetBlue Airways' updated revenue outlook compares with other airlines juggling demand strength and cost pressure by reviewing our list of solid balance sheet and fundamentals (24 results).
JetBlue Airways Investment Narrative Recap
To own JetBlue Airways, you need to be comfortable with a story built on leisure demand, operational fixes and tight cost control. The higher revenue per available seat mile outlook leans on that demand holding up. The most important short term catalyst remains execution in the operation, especially on-time performance, as disruptions can quickly erode the benefit of stronger unit revenue.
The biggest risk still sits with cost pressure and demand visibility. JetBlue is exposed to fuel price swings and rising labor costs, while relying heavily on close in bookings. The updated guidance, with higher fuel and non fuel unit costs, reinforces that risk rather than changing it.
The planned sale of an Airbus A321neo XLR ties directly into this update. JetBlue is trimming capital expenditure and adjusting fleet plans while it leans on returning aircraft for capacity. This can help preserve cash but also caps long term growth if demand remains solid.
For you as a shareholder, that move keeps the focus on near term utilization, cost per seat and reliability instead of rapid expansion. The key execution question is whether JetBlue can translate strong travel demand and a leaner capex profile into more stable earnings while still contending with competition, fuel volatility and an unprofitable starting point.
JetBlue Airways' current analyst blueprint points to revenue reaching US$12.6b and earnings of US$45.6 million by 2029, based on forecast yearly top line growth of 9.9% and an earnings swing of roughly US$932 million from a loss of US$886.0 million today to the projected profit level.
Uncover why JetBlue Airways' fair value indicates a 24% potential upside to its current price that could close sooner than many investors expect.
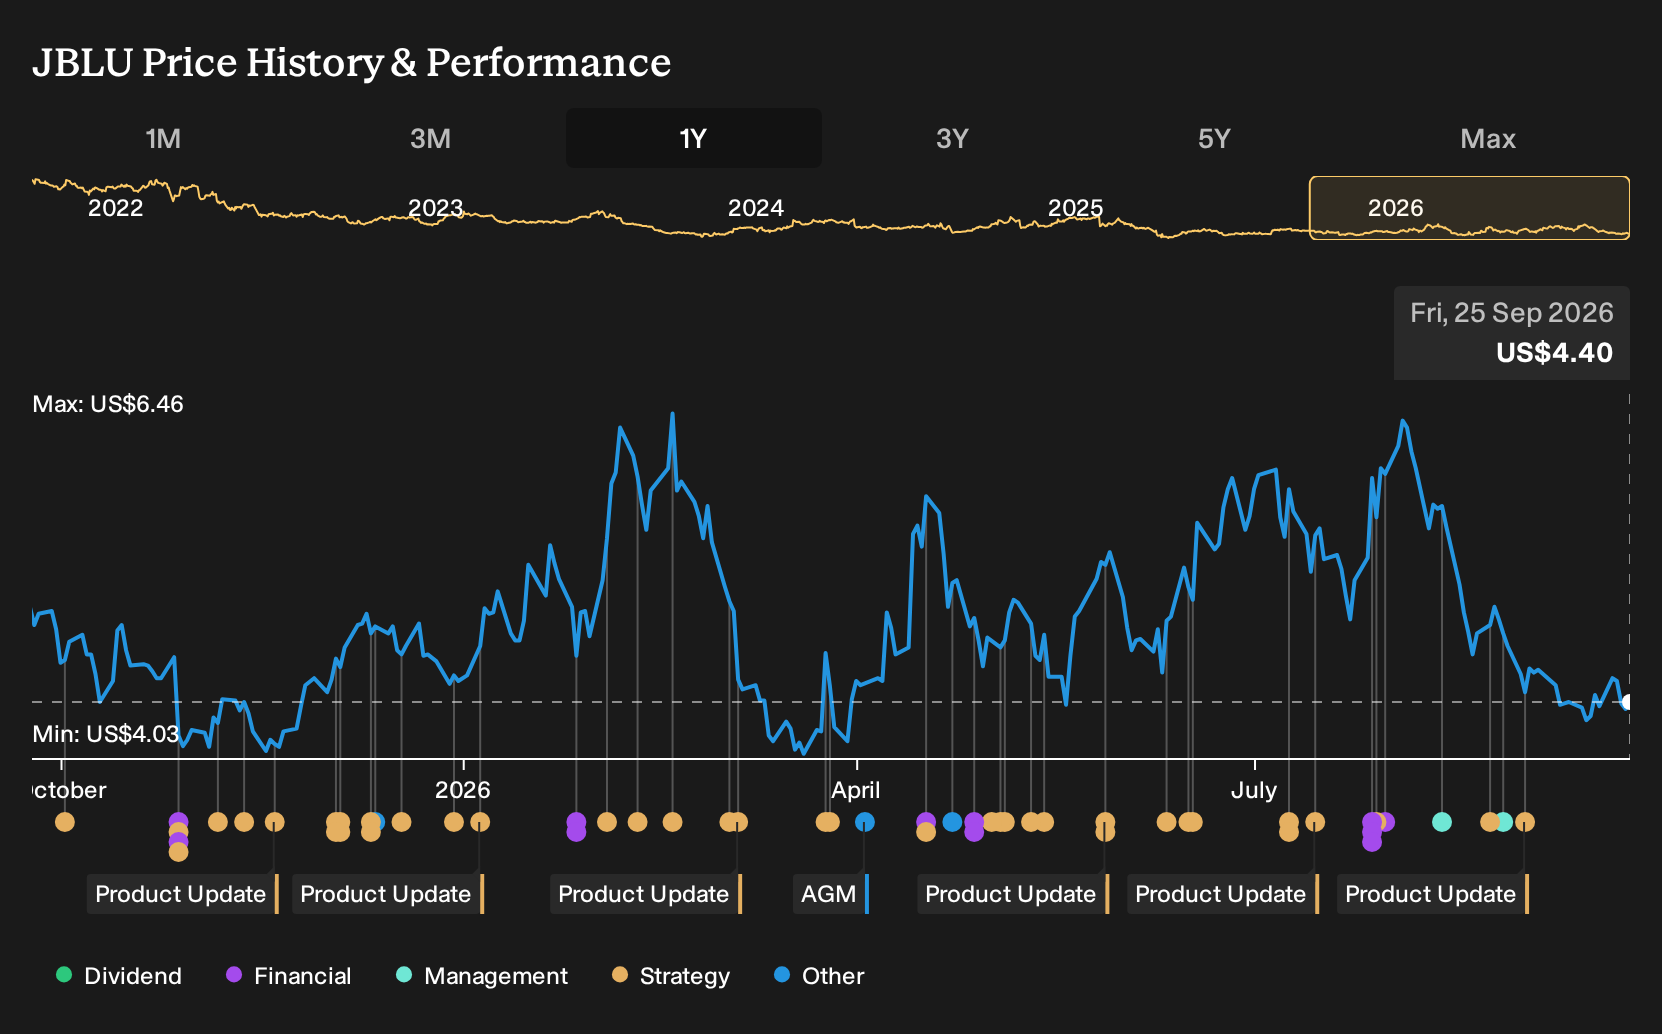
Exploring Other Perspectives
One alternate view puts regulatory and environmental costs at the center of the JetBlue Airways debate. On that more cautious track, analysts were only penciling in revenue of about US$11.6b and earnings of roughly US$254.4 million by 2029. That is far more pessimistic than consensus, and this fresh guidance may push some of those expectations to shift.
Explore 2 other JetBlue Airways fair value estimates, including one that suggests it could be worth just $5.47!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your JetBlue Airways research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for JetBlue Airways. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate JetBlue Airways' overall financial health at a glance.
Looking For More Investment Ideas Beyond JetBlue Airways?
Once you have formed a view on JetBlue Airways, it can help to line it up against other opportunities that match your risk tolerance, income needs, or preference for balance sheet strength. The Simply Wall St Screener can quickly surface groups of stocks that share similar qualities so you can compare JetBlue against a broader watchlist.
- If you want potential value ideas with strong fundamentals, start by scanning a curated set of 32 high quality undervalued stocks that meet strict quality checks.
- If stability matters more to you than rapid expansion, consider reviewing a 30 resilient stocks with low risk scores to see which businesses have lower risk scores.
- If you prefer steady balance sheets and resilient financial profiles, broaden your search using a list of solid balance sheet and fundamentals (24 results) that could sit alongside or instead of JetBlue in your portfolio.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com