
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Why Everyone Is Watching EastGroup Properties (EGP) Again
EastGroup Properties (EGP) has scheduled its next major check-in point for investors, with management set to review third-quarter 2026 results on an October 22 earnings call and webcast.
Recent trading has been softer, with the share price slipping over the past quarter even as the year-to-date share price return of 12.02% and 1-year total shareholder return of 23.86% point to momentum that has been building over a longer stretch for EastGroup Properties.
Compare EastGroup Properties with a curated group of industrial-focused REITs and other income ideas by scanning the 8 dividend fortresses, which could complement this type of earnings-driven story.
After a strong 1-year run and a softer recent patch, EastGroup Properties now sits at a level where the next question is simple: Does the current price still compensate you for the risk you are taking?
Most Popular Narrative: 11.6% Undervalued
On the most followed view, EastGroup Properties screens as undervalued, with a narrative fair value of $227.90 against a last close of $201.52. This puts the upcoming October earnings call in sharper focus for anyone weighing risk against potential upside.
Sector leading low leverage with debt to EBITDA of 3x, strong interest coverage and substantial undrawn revolver and forward equity capacity, backed by a Baa1 rating and a long record of dividend payments, gives EastGroup Properties room to fund additional development and acquisitions that can contribute to future NOI and earnings.
See why 7 investors see EastGroup Properties as 12% undervalued.
Result: Fair Value of $227.90 (UNDERVALUED)
Still, the narrative around EastGroup Properties can crack if easing re leasing spreads persist or if the larger 2026 development push runs ahead of tenant demand.
Find out about the key risks to this EastGroup Properties narrative.
Another View on EastGroup Properties Valuation
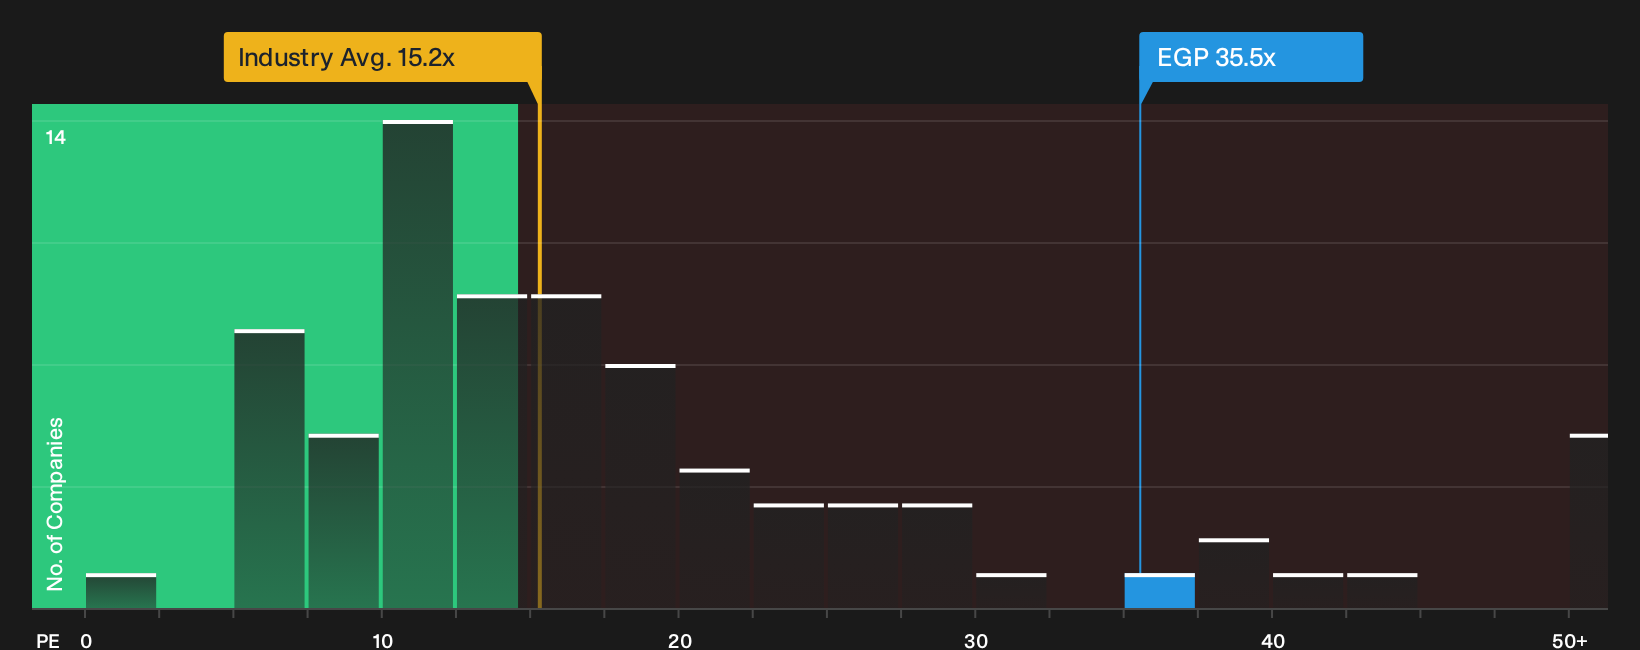
There is a catch with EastGroup Properties. On a P/E basis, the stock looks expensive at 35.5x compared with both the US Industrial REITs peer average of 32.8x and the global industry at 15.2x, and even above its own 33.4x fair ratio. That gap suggests less margin for error if future growth or rental assumptions disappoint.
For investors who prefer to lean on earnings multiples rather than narrative fair value, the key question is simple: Is paying a premium multiple for EastGroup Properties worth the potential reward if conditions shift away from the current script or if sentiment cools from today’s optimistic setting?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and concern around EastGroup Properties feels familiar, use it as a prompt to move quickly and stress test the story against your own thresholds. To weigh the upside against the risks in one place, review the 4 key rewards and 1 important warning sign.
Looking For More Investment Ideas Beyond EastGroup Properties?
If EastGroup Properties has sharpened your thinking, do not stop here. A broader watchlist can help you spot fresh opportunities before they become crowded trades.
- Target potential mispricings early by scanning the 32 high quality undervalued stocks that align with solid fundamentals and clear upside narratives.
- Strengthen your downside protection by focusing on businesses from the list of solid balance sheet and fundamentals (24 results) that can better handle tougher conditions.
- Get ahead of the crowd by combing through the 16 high quality undiscovered gems before interest and expectations catch up.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com