
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Oil Transport Stocks Retail Investors Are Watching After The Strait Of Hormuz Shift
Stocks tied to oil production, refining, and tanker shipping just hit an interesting crossroads. Equities moved higher even as long-term Treasury yields touched fresh 52-week highs, while crude prices dropped after reports of a possible plan to reopen the Strait of Hormuz eased supply fears. That mix of stronger rates, softer oil and shifting inflation expectations could reshape how investors view risk. This article walks through 3 stocks from the Global Oil & Refined Products Trade and Transport screener that appear most directly exposed to these headlines, and explains how this backdrop might influence their stories.
The three stocks in focus below are only a starting sample from this theme, and the full screen surfaced 55 more companies with similarly detailed stories that are not covered here. To go broader and identify your own highest conviction ideas in this trade and transport space, head straight into the Global Oil & Refined Products Trade and Transport screener.
SK Innovation (KOSE:A096770)
SK Innovation links directly into the Global Oil & Refined Products Trade and Transport theme through its integrated refining and petrochemical network, while its growing exposure to batteries and new energy projects gives this stock a different twist within a largely traditional fuel cohort.
SK Innovation generates most of its top line from Energy and Chemicals at about ₩160,687,350 million, with smaller contributions from E&S on roughly ₩16,567,367 million and Batteries and Materials on about ₩13,018,986 million, and carries a market value near ₩25,302,004 million.
"Intensifying global decarbonization policies and the ongoing shift away from fossil fuels will steadily erode demand for SK Innovation's core refining and petrochemical segments, resulting in sustained revenue declines and long-term pressure on group-wide margins as legacy business lines become increasingly uncompetitive."
What happens to SK Innovation’s long term margin story depends heavily on how one less obvious pressure inside its newer energy businesses plays out.
That pressure point is exactly what the full narrative for SK Innovation unpacks, including how SK Innovation’s battery push could decouple future cash flows from legacy fossil exposure.

Aegis Logistics (NSEI:AEGISLOG)
Aegis Logistics plugs into the Global Oil & Refined Products Trade and Transport theme through its role as an oil, gas, and chemical logistics specialist, running shore based tank farms and LPG solutions that link import flows, storage, and last mile distribution across India.
Aegis Logistics generates most of its revenue from the Gas Terminal Division at about ₹82.9b, with the Liquid Terminal Division contributing roughly ₹6.8b, and the business carries a market value near ₹479.3b.
Aegis Logistics provides exposure to the logistics side of energy flows rather than pure commodity prices. This can be relevant when investors are reassessing trade routes, storage demand, and pricing power across the entire oil supply chain.
"The company's heavy focus on aggressive terminal and capacity expansion, with targeted aggregate capital expenditure of 5 billion USD by 2030, exposes it to a serious risk of overcapacity, especially as long-lived assets may face diminishing demand due to global acceleration toward renewables and electrification."
Whether that expansion turns into a long term tailwind or a drag depends on how one quiet shift in customer demand ultimately lands.
That quiet shift starts with contract quality and how it could reshape where returns land along the chain. This is exactly what the full narrative for Aegis Logistics unpacks, including how Aegis Logistics might turn today's capacity risk into optionality for future flows.

Buana Lintas Lautan (IDX:BULL)
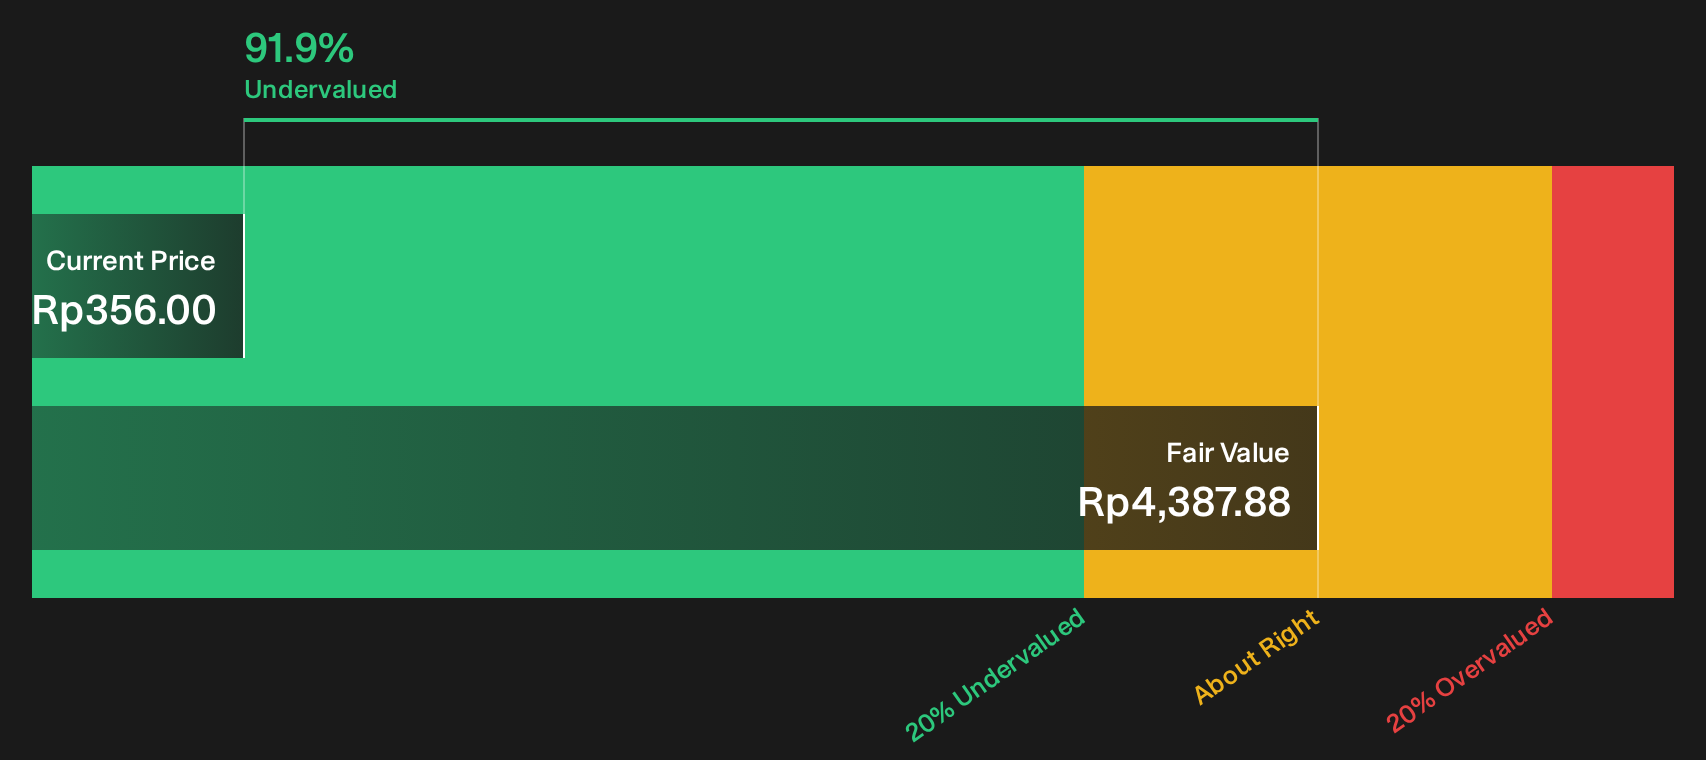
Buana Lintas Lautan runs oil and gas tankers that move crude, refined products, and liquefied gases through key sea lanes, giving direct exposure to the Global Oil & Refined Products Trade and Transport theme. Most revenue comes from Oil and FPSO/FSO services at about US$193 million, with Gas at roughly US$7 million and Others at US$4 million, and the stock carries a market value near IDR5.5t.
For investors who want pure shipping exposure to crude and refined product flows rather than refinery or production risk, Buana Lintas Lautan is a focused transport play. The price-to-earnings ratio sits well below many shipping peers, and the key issue now is what happens if a single pressure point in its funding mix tightens further.
If that funding pressure has your attention, the analysis report for Buana Lintas Lautan shows where Buana Lintas Lautan's balance sheet risk might be masking potential future upside.
Seeking Fresh Alternatives Before They Fly
Fresh ideas often move first, and strong momentum can build before the broader market pays attention. Scan under the radar now, before entries start dropping, and aim to position early.
- Identify cash generative outliers with sturdy balance sheets by focusing on a curated list of solid balance sheet and fundamentals (202 results) that screens for resilience while it may still be overlooked.
- Explore early upside potential in high quality miners by tracking a hand picked group using the 36 elite gold producer stocks before renewed interest draws more attention.
- Monitor structural demand shifts in key materials by scanning a focused 17 top copper producer stocks while the market is still catching up to the story.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com