
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Our Pick Of The Best Canadian Uranium Stocks In September 2026
Energy supply has become a political pressure point again as the closure of the Strait of Hormuz disrupts global oil and liquefied natural gas flows and pushes energy prices around. That puts steady, low carbon nuclear power in the spotlight for Canadian investors looking beyond fossil fuels. This article walks through three nuclear energy stocks from our Canada focused screener to help you research this theme in more detail.
The three Canadian nuclear energy stocks covered below are just a sample, and the full screen surfaced 57 more businesses with equally detailed narratives that are not included here. To identify, compare, and analyze the highest conviction nuclear opportunities, go straight to the Nuclear Energy Stocks screener.
Cameco (TSX:CCO)
Cameco is one of the largest pure plays on the nuclear fuel chain, with uranium mining at the centre of its role in the Nuclear Energy Stocks theme and additional exposure through refining, fuel fabrication and reactor technology services.
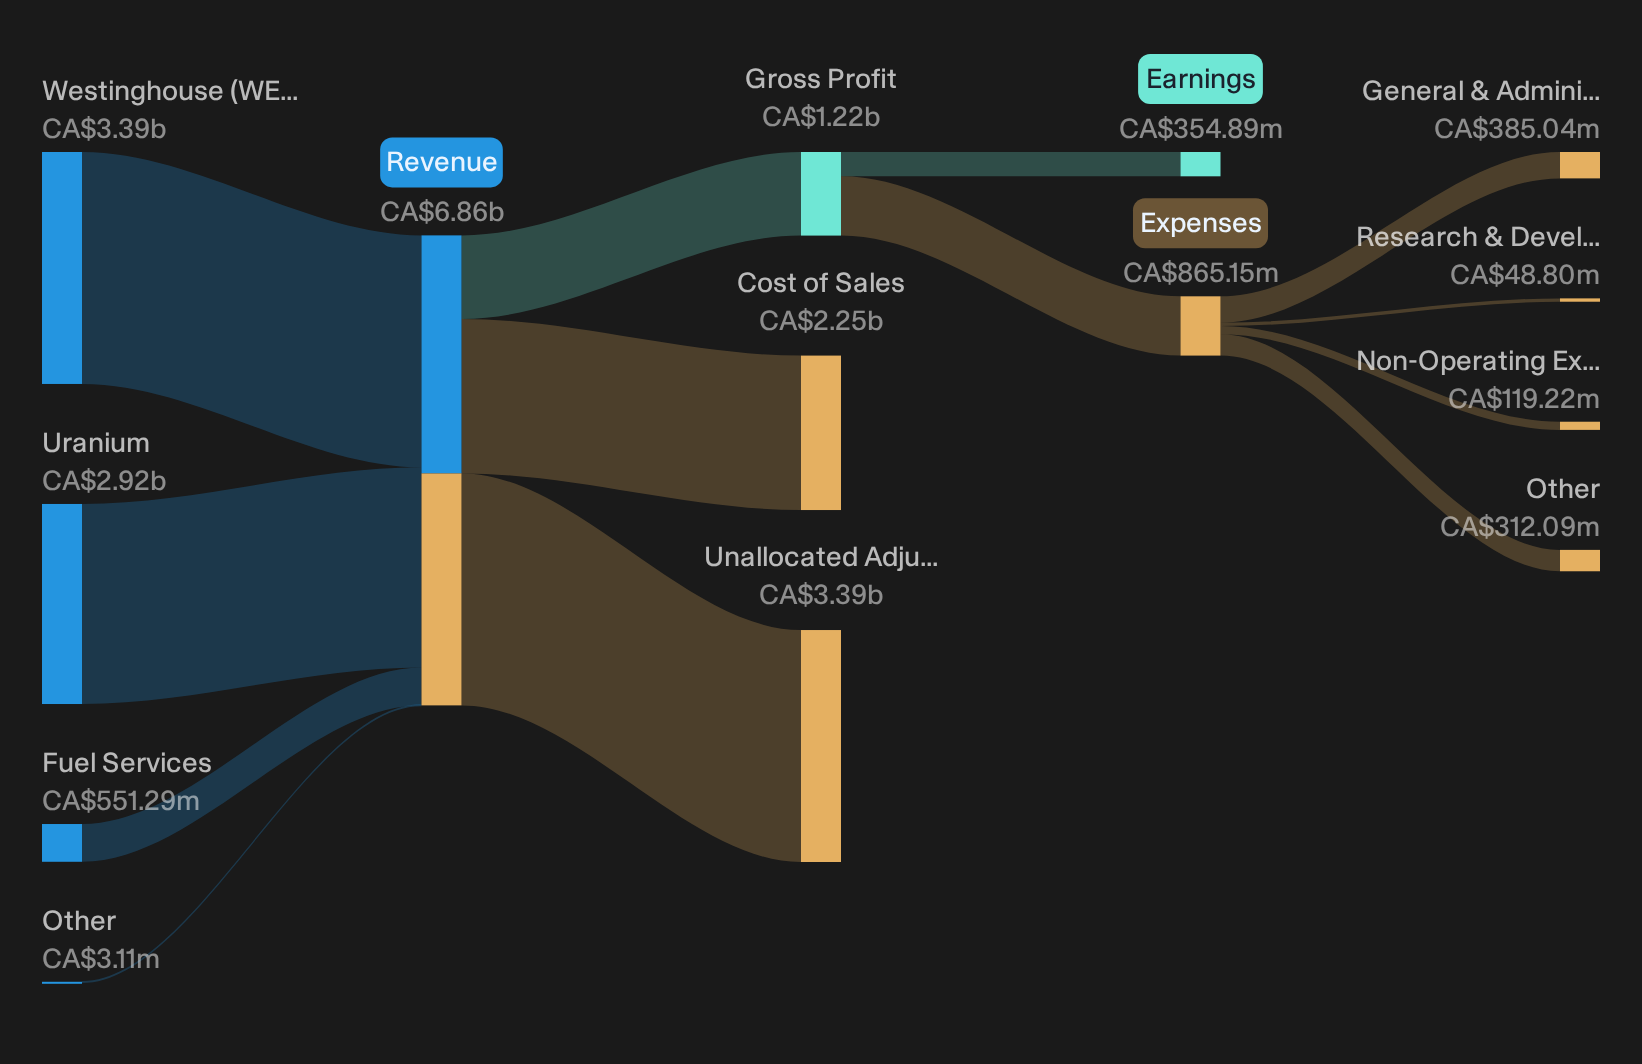
Cameco generates about CA$2.9b of revenue from Uranium, CA$551 million from Fuel Services, and around CA$3.4b from its Westinghouse segment, with a small Other line and unallocated adjustments. The stock has a market value of roughly CA$54.2b.
For investors tracking nuclear energy, Cameco ties together uranium mining, fuel processing and reactor technology in a way few peers can match. This is why expectations around its future demand and pricing power attract so much attention.
"Cameco stands to benefit from a global wave of new nuclear construction, driven by heightened government policy support, net-zero emission mandates, and growing energy security concerns, factors likely to accelerate demand for uranium and nuclear fuel, directly supporting higher long-term revenues."
The real swing factor is how one sustained shift in utility contracting and fuel pricing ultimately flows through to Cameco’s margins and cash generation.
That margin story is where Cameco gets interesting, and the full narrative for Cameco shows how shifting fuel contracts, pricing power, and execution risks could reshape the whole investment case.
Denison Mines (TSX:DML)
Denison Mines is a uranium developer focused on supplying nuclear fuel, centred on its 95% owned Wheeler River project in Saskatchewan’s Athabasca Basin, with current mining revenue of about CA$4 million and a market value around CA$3.4b.
For investors tracking nuclear fuel supply rather than just existing reactors, Denison Mines offers exposure to high grade uranium resources that are still being built out. This is one reason its progress attracts attention from those leaning into the Nuclear Energy Stocks theme.
"With major projects such as the Wheeler River uranium project, Denison is positioned as one of the faster-growing uranium developers in North America."
What happens when the next phase of development spending, financing terms, and uranium pricing all pull on this story at the same time?
Those moving parts all pull in different directions, and the full narrative for Denison Mines shows how Denison Mines could balance financing risk against accelerating uranium demand and project execution.

Energy Fuels (TSX:EFR)
Energy Fuels is a uranium producer at the nuclear fuel front end, earning about US$106 million from its Uranium segment, alongside rare earth elements and heavy mineral sands, and carries a market value of roughly CA$4 billion.
For investors focused on nuclear fuel supply, Energy Fuels links U.S. uranium production with a growing rare earth platform that could shift how Western utilities and manufacturers source key materials.
"Completion and commissioning of the White Mesa Mill rare earth separation Phase 2 expansion (potentially increasing monazite processing to 60,000 tonnes/year and enabling commercial-scale heavy rare earth production such as Dy/Tb) could establish Energy Fuels as a major western supplier, capturing price premiums driven by western supply chain security and increasing electrification demand, which could support long-term revenue and margin upside."
What really moves the needle for Energy Fuels will be how one funding and execution swing factor plays out for its broader growth plans.
That swing factor is exactly what the full narrative for Energy Fuels unpacks, showing how Energy Fuels could turn execution risk into accelerating leverage on uranium and rare earth pricing power.

Curious About What Else You Might Be Missing?
Fresh ideas move first. By the time momentum is flying, early entry points are already dropping away. Scan these under the radar lists before the crowd.
- Spot resilient businesses investors often overlook by running the list of solid balance sheet and fundamentals (7 results). This filters for sturdier financial foundations while prices still reflect past worries.
- Target stronger cash generation with the 5 high quality undervalued stocks, which highlights companies where current pricing lags underlying fundamentals.
- Track where critical metals are gaining attention through the curated 36 best rare earth metal stocks, focused on producers tied to electrification and advanced manufacturing trends.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com